



Bright Spots in Chinese Data Overshadow Trumps Threats
After two downbeat sessions investors are once again in a buying mood showing immunity to a whole host of reasons to remain bearish.
Share this:
After two downbeat sessions investors are once again in a buying mood showing immunity to a whole host of reasons to remain bearish.
Following on from a higher close on Wall Street, European bourses are pointing to a stronger start as investors brush off rising US – Sino geopolitical tensions instead focusing on the bright spots in mixed Chinese data which provided further insight int the post-lockdown economic recovery.
Data from China was a mixed bag. A better than forecast industrial production reading showed that heavy industry was rebounding in the world’s second largest economy. However, the same cannot be said for retail sales, which declined a worse than forecast -7.5% in April. Although, this as a significant improvement on last month’s -15.8% decline. The improvement in industrial production indicates that stimulus measures are working. However, this will take longer to trickle down to improving consumer confidence and lifting sales.
What we can take away from the Chinese data and apply to other economies is that improvements in economic activity will be gradual.
Concerns over a second wave of infections which have weighed on sentiment over much of the week, continued to play out in China and South Korea where clusters of outbreaks are causing a problem. Fears of infections rising in Germany have also weighed on risk appetite as the economy gradually reopens.
Trump threatens to cut ties with China
The markets have largely brushed off Trump threatening to cut off relations with China. The flare up in US – Sino tensions come amid Trump’s efforts to pint the blame of the coronavirus outbreak on China. Whilst traders are sweeping these comments under the carpet today, it is highly unlikely that we have heard the end of this. The US – Sino relations theme could well hamper market sentiment across Q2.
The markets have largely brushed off Trump threatening to cut off relations with China. The flare up in US – Sino tensions come amid Trump’s efforts to pint the blame of the coronavirus outbreak on China. Whilst traders are sweeping these comments under the carpet today, it is highly unlikely that we have heard the end of this. The US – Sino relations theme could well hamper market sentiment across Q2.
German GDP & US Retail Sales
German GDP is expected to show -2.2% decline in the first quarter, a level last seen in 2009. However, this will only capture the start of lockdown with a 10% contraction forecast for the second quarter of the year.
German GDP is expected to show -2.2% decline in the first quarter, a level last seen in 2009. However, this will only capture the start of lockdown with a 10% contraction forecast for the second quarter of the year.
Investors will turn their attention to US retail sales. Expectations are for sales to decline-12.5% month on month in April the month of lockdown. This comes after a 8.7% decline in March. With the US economy gradually starting to reopen, today’s data should represent the bottom for retail sales. This news will be largely priced in. Only a significant beat or miss could provoke a movement in the market.
Dax levels to watch:
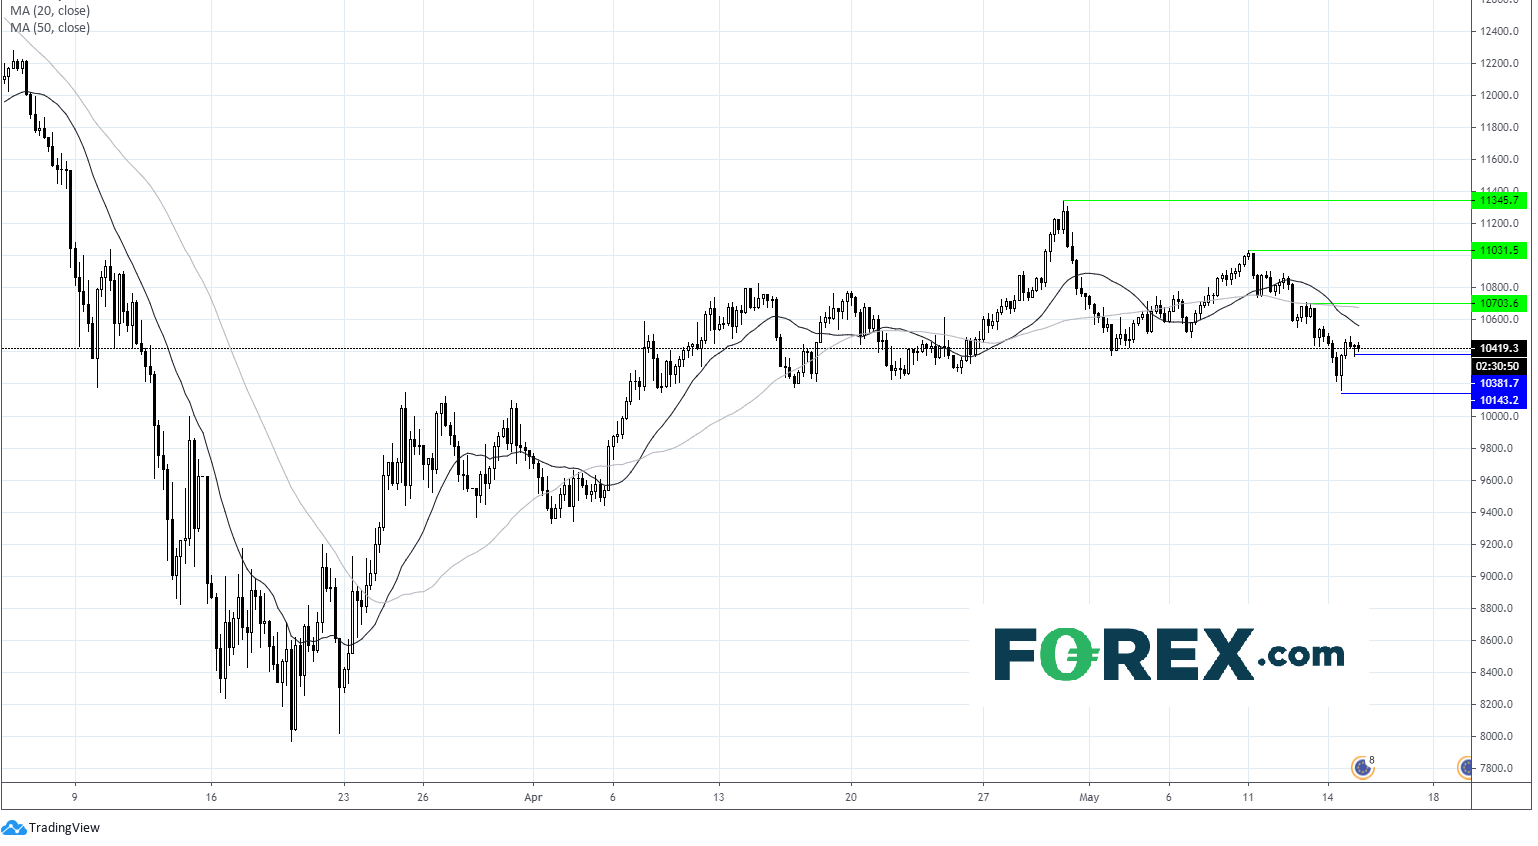
After two days of losses, the Dax is trading below its 20 & 50 sma on 4 hour chart. Immediate support can be seen at 10372 (overnight low) prior to 10141 (yesterday’s low).
Resistance can be seen at 10560 (20 sma) prior to 10685/10700 (50 sma & high 13th May) and 11030 (high 11th May).
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.