



China’s manufacturing and services sectors expanded in June
Data from NBS (National Bureau of Statistics) expanded for the first month in four as lockdown restrictions were eased.
Share this:
- China’s manufacturing and service sectors expanded for the first month in four in June
- NBS manufacturing rose to 50.2 in June (below 50.5 expected)
- NBS services expanded at 54.7 (above 52.5 expected)
- The composite PMI rose to an 11-month high of 54.2
China’s economy expanded in June according to the official PMI data released by the NBS (National Bureau of Statistics). The composite PMI, which includes both services and manufacturing sectors expanded slightly by 50.2, although it was held back by the manufacturing sector which also rose to 50.2 (versus 50.5 forecast). It was the services PMI which made up the baulk the baulk of expansion in June by rising at its fastest rate in 13-months at 54.7, beating expectation of 52.5.
Today’s NBS numbers were encouraging to see, even if manufacturing slightly underwhelmed and expectations were for an improvement with the easing of lockdown restrictions. In fact, I’d argue that the market reaction would have been more noticeable today’s PMI’s not expanded. Attention now shifts to Caixin’s manufacturing PMI data tomorrow - which is a privately run survey - to see if they back up or even better the data from the NBS.
The China A50 has made a solid recovery over the past 7-weeks. Earlier this month the government unveiled a 33-point stimulus package to help ease that pain that they may miss their growth target of ‘around 5.5%’. Premier Li has applied further pressure on local governments to help prevent an economic slowdown, and (renewed) lockdown restrictions eased in Shanghai.
Yet producer prices continue to disinflate, consumer prices remain benign and growth is likely to remain below target. And that leaves the door open for further stimulus which is usually a net-positive for equities.
The China A50 is on track for its best month over 3-years
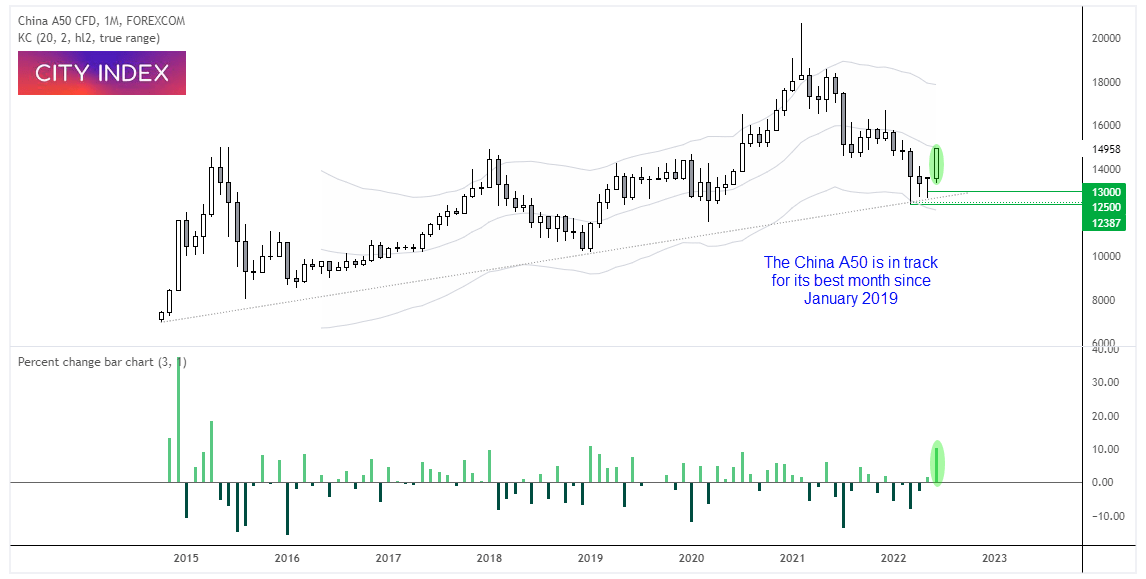

Chinese equity markets have responded well to today’s PMI figures, and bulls aren’t pulling any punches today with the index on track for its best month in 3-years. Given it endured a 13-month correction from the 2021 peak and there’s hope that the worst of Covid is in the rear-view mirror, dare I say… the market may have bottomed in March. Note how it found support at the long-term trendline and momentum is pointing firmly higher.
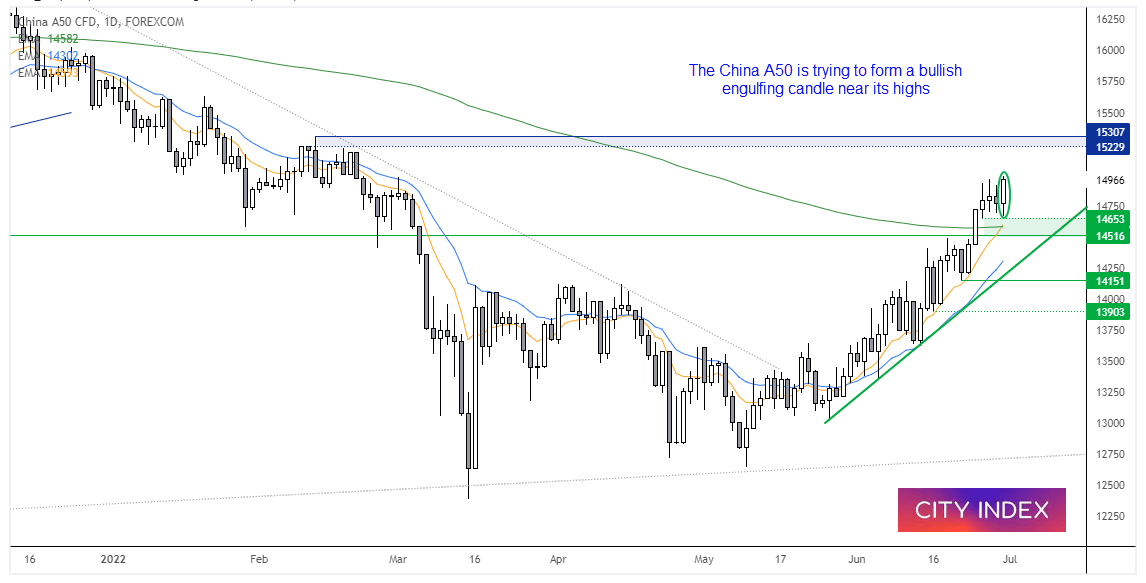

The daily chart has formed a strong trend, and its recent consolidation held above the 200-day eMA. Today’s rally saw it touch its highest levels since March and, whilst the day is yet to close, the market is trying to form a bullish engulfing candle at the highs. The market now looks like it wants to rally towards the 15,300 resistance zone, and our bias remains bullish above the 14,516 low.
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.