



Commodity prices forecast to be strong in 2023
The StoneX Metals and Energy Markets Annual Outlook forecasts double digit percentage increases for seven out of twelve commodities tracked.
Share this:
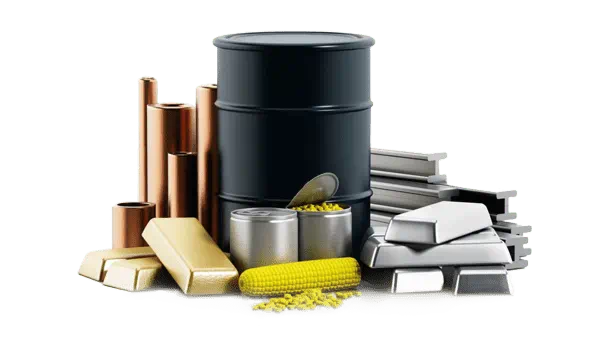
The StoneX Metals and Energy Markets Annual Outlook forecasts double digit percentage increases for seven out of twelve commodities tracked.
Last year’s big winners included Zinc (17% price increase), Aluminium (up 16%), and Copper (up 15%) – which our team’s forecasts suggest might continue to be the case – while Platinum is projected to see a turnaround.
Last year, the big losers were Nickel (down -44%), Platinum (-12%) and Oil (-11%). It’s interesting to note that overall, commodities lagged equity returns, with the S&P Composite index up 19%.
Uncertainty on the interest rate path, reflecting inflation concerns, weigh on the outlook for economic growth and so the industrial demand for commodities.
Mid-December US GDP growth moderated in Q4 2022, and recent monthly data has been far less encouraging. Europe faces the same inflation headwinds plus the impact of the Russia-Ukraine conflict. However, consumer and manufacturing sentiment, and the labour market, have all been resilient. That might change if the Fed raises interest rates more aggressively, as markets now project.
China, the swing player in economic growth and commodity demand, despite its post-Covid lock down rebound, could still see subdued growth rates in its historical context.
StoneX Commodity Forecasts
| Commodity | End 2022 | End 2023 Forecast | Change |
| Gas (Dutch TTF) | €76.32 | €110 | 44% |
| Zinc | $2,973 | $3,890 | 31% |
| Copper | $8,372 | $9,800 | 17% |
| Platinum | $1,065 | $1,240 | 16% |
| Aluminium | $2,378 | $2,750 | 16% |
| Gold | $1,812 | $2,070 | 14% |
| Silver | $23.95 | $27.25 | 14% |
| Palladium | $1,788 | $1,830 | 2% |
| Tin | $24,808 | $25,250 | 1% |
| Lead | $2,293 | $2,325 | 1% |
| Oil (Brent crude) | $85.91 | $85.00 | -1% |
| Nickel | $30,048 | $29,000 | -3.5% |
Source: StoneX Financial Ltd. These forecasts represent the views of the StoneX Metals and Energy teams and not necessarily those of FOREX.com or City Index analysts.
Commodity review
Natural gas: Our year-end price forecast of €110/MWh accounts for the additional seasonal pressure we envisage next winter due to depletion rate concerns. We believe this winter’s mild beginnings may depress prices throughout 2023 on a year-by-year basis, as Europe already looks considerably better placed to survive the next cold season. Significantly reduced supply-side vulnerability might reduce volatility until the autumn, when weather conditions may contain substantial upside price risk as we approach 2024.
Copper: The recovery in the copper price could be prolonged well into 2024. On the demand side, we forecast that copper may encounter a year of moderate demand in 2023, rising by 2.4%, with growth led by China and Asia, while western demand might be constrained by potential recessions. On a global scale, copper’s use in green technologies could continue to outpace other end uses.
Platinum: The demand looks bright as the global vehicle industry recovers, as over 40% of platinum demand is in automotive exhaust emissions control, including diesel vehicles. The European Commission’s proposal for aligning diesel and gasoline vehicle emissions favour platinum. In addition, the effective life of the catalysts is to be doubled – although the technology here may mean retooling rather than raising loadings. Add to this the continued substitution of platinum for palladium in the sector, and platinum might well be the best performing precious metal this year.
Aluminium: Risks to the supply side could arise from the implementation of US sanctions on Russian material, which accounts for 6% of global aluminium supply. Moreover, the growing move towards natural resource protectionism in countries like Indonesia could result in increased export tariffs for key materials.
Gold: Gold is reasserting its role as a risk hedge and attracting investment activity in the face of geopolitical risk, some bearish dollar views and continued economic uncertainty, while views are also mixed over the equity markets’ prospects. Overall, tailwinds outweigh headwinds, and we are expecting a test of then $2,100 gold price before year-end – unless the Fed turns more hawkish on rates, which would be bearish for gold.
Silver: We expect silver to outperform a bullish gold market, but with its usual volatility, and the overall trend might be only marginally higher than that of gold. The beta is normally 2.0-2.5 to the gold price, but we are expecting nothing like that level this year. We are looking for a silver price average of $25.30 this year, a gain of 14% over last year’s ending value of $23.95.
Palladium: While there could be a recovery this year as the auto sector, typically 82% of demand, comes back to life with the easing in the microchip supply chain and the re-opening of China, and relatively low dealer inventories in North America, palladium would be likely to run behind the underlying auto numbers as it competes with the substitution threat from platinum, which is now entrenched. For the longer term, the electrification of the fleet and the ban on new ICE vehicles from 2035 onwards in a few regions will take its toll on the palladium market.
Tin: We forecast tin demand from construction and industrial sectors to remain muted, with China taking the lead as it reopens. Our outlook for supply in 2023 however, is brighter, with refined output is expected to return to growth, rising by 2% year-on-year, as improving supply chains provide easier shipments of material from the West to East.
Lead: We forecast 2023 to mark a universal production rebound for refined lead for both primary and secondary supply, with the fees paid to smelters by mines for converting copper concentrate to copper cathode (known as TC/RCs) set to remain elevated on plentiful material, although energy prices with be pivotal to smelter profitability.
Oil: We think the year might end in a supply surplus that should could onsequently ease the inventory pressure that we expect to build from March. Our year-end price forecast of $85 does not mean we think the road ahead should be entirely smooth. Indeed, upside risk factors ranging from the dollar to resurgent Asian demand could push prices above $95 in Q2 2023, threatening another bout of non-core inflationary pressure across much of the globe.
Nickel: The fundamental picture for nickel is turning less supportive, with a forecast second (and increasing) year of surpluses, driven by ongoing capacity expansions within Indonesia for both Nickel pig iron (NPI) and ex-NPI production, solidifying Indonesia as the world’s largest nickel producing country for a third year.
Taken from analysis by Rhona O’Connell, Head of Commodity Market Analysis for EMEA & Asia ([email protected]); Natalie Scott-Gray, Senior Base Metals Analyst ([email protected]) ; and Harry Altham, Energy Analyst ([email protected]).
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Analysis: Rising Yields and Dollar Strength Weigh on XAU/USD
The trading week continues, and for now gold remains under notable pressure in the short term. This can be seen in the performance of XAU/USD over the last three trading sessions, where the metal has declined by more than 2.00%, bringing a bearish bias back into focus after it had lost momentum in recent weeks.
Gold, silver shrug off a brutal macro stress test
A hawkish Fed, surging short-dated Treasury yields and a firmer dollar failed to deliver the kind of damage usually seen in precious metals.

Gold Analysis: XAU/USD Remains Under Pressure After Fed Rate Decision
Gold continues to face challenging conditions in the short term, with the precious metal already recording three consecutive losing sessions and posting a decline of nearly 2.3%. This price action continues to highlight a bearish bias that has become increasingly relevant within the market.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.