



Crude oil unwind hits a hurdle
The headlines remain overwhelmingly bearish for crude, yet repeated tests of the 200-day moving average have failed to deliver a decisive break lower. That makes the level a crucial gauge of sentiment in the sessions ahead.
Share this:
- Hormuz optimism continues to pressure crude prices
- Repeated 200DMA tests fail to deliver breakdown
- Stretch indicators warn squeeze risk remains
Good news keeps coming
Bears have had it all their own way in crude recently. An improving outlook for relations between the United States and Iran has helped fuel an abrupt unwind in prices, encouraging traders to contemplate a return to levels seen before the war erupted.
But after such a sharp decline, it's worth remembering we've seen plenty of false dawns during this conflict. Periods of optimism have repeatedly been followed by renewed escalation, and while everything appears fantastic right now, history and commonsense suggests another setback can't be ruled out.
Given how extended the move has become, any development that derails hopes for a lasting agreement could easily spark a squeeze. That's why I'm watching the 200-day moving average closely in the near term.
200DMA the line in the sand
Source: TradingView
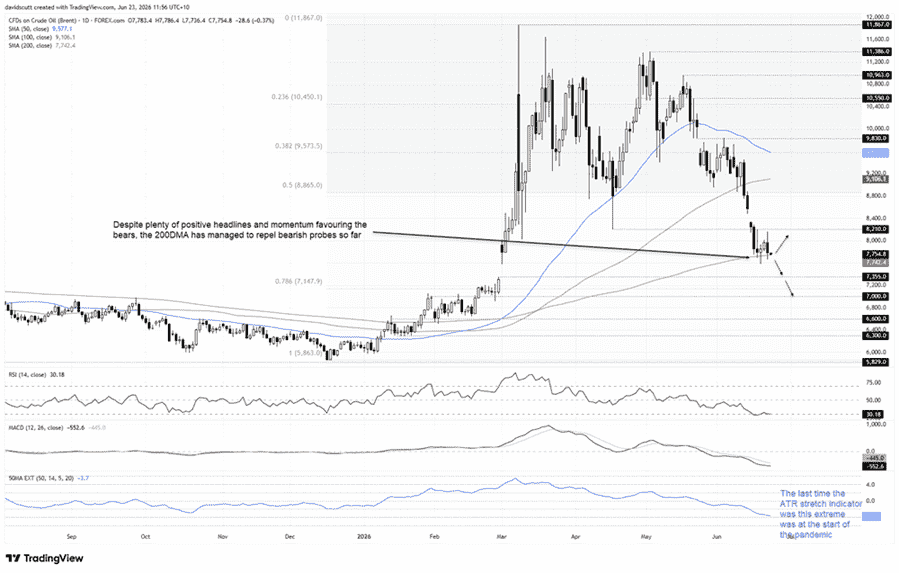
Crude continues to gravitate towards it, acting like a magnet as optimism surrounding the peace process builds. However, it's been tested repeatedly in recent sessions, but none of the breaks have stuck, reinforcing its importance as the downside level to watch.
For bears looking for an extension of the downside move, it's not enough to see crude probe beneath the 200-day moving average; they need to see one of those breaks stick, preferably accompanied by a close beneath the recent low near $76 a barrel. If that were to occur, attention would likely shift towards $73.55, where crude settled on the Friday before fighting erupted in late February.
Should the gap be filled, $70 a barrel becomes an obvious downside target, having repeatedly acted as both support and resistance over the past year. Below there, $66 warrants attention, having capped rallies and provided support on multiple occasions earlier this year.
Given the selloff has been driven by the removal of geopolitical risk premium, a return to those levels would suggest the market believes the impact on supply has been neutralised, which comes across as optimistic given ongoing downstream supply disruptions and need to replenish strategic reserves.
From a momentum perspective, the oscillators continue to favour downside. RSI (14) is trending lower and sits near 30, while MACD remains in negative territory below its signal line. The one note of caution is how rapid crude's unwind has become, with the ATR stretch indicator in blue sitting at levels not seen since the start of the pandemic in early 2020.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.