



DAX Struggles at Key Level as Tariff Fears Mount
Markets face rising volatility as weak US data and Trump’s tariff threats stir stagflation fears. The DAX is testing critical resistance at 24,000 after rebounding from recent lows, while US stocks slipped on weaker ISM data. Traders eye Fed cuts, global earnings, and geopolitical developments. Bitcoin hits record July close; Ethereum sees record ETF inflows. Apple and xAI drive AI innovation; NASA climate satellites face shutdown.
Share this:

Market Overview
- US Stocks Dip
- Tariff concerns weighed on sentiment.
- Companies like Yum Brands and Caterpillar flagged cost pressures.
- US Services Sector
- ISM Services PMI fell to 50.1 in July.
- Firms report higher input costs and weaker hiring.
- Rising tariffs contribute to stagflation fears.
- US Manufacturing & Labor
- ISM Manufacturing Index dropped to 48.0 – lowest since Oct 2024.
- Employment subindex fell to 43.4; indicates job market weakness.
- New orders stagnate; prices hit highest since Oct 2022.
- Tariff/trade policy uncertainty impacting planning.
- Fed Expectations & Treasuries
- Markets price in 94% chance of a September rate cut.
- 10-year yields near multi-month lows before $42bn auction.
- Earnings Season
- ~80% of S&P 500 beat Q2 expectations.
- Focus now shifts to upcoming Disney and McDonald’s results.
Geopolitical & Policy Updates
- Tariff Rhetoric Escalates
- Trump threatens new tariffs on semiconductors and pharmaceuticals.
- Possible trade deal with China hinted.
- New Fed governor nomination expected by weekend.
- UK Monetary Policy
- BoE likely to cut rates from 4.25% to 4.0%.
- Growth/inflation forecasts to guide future rate paths.
- Financial conditions remain tight despite prior cuts.
- Fiscal policy under scrutiny – bond yields stay elevated (~4.5%).
- Next budget test in November from Finance Minister Rachel Reeves.
Global Markets
- Asia
- Mixed equity performance.
- Japan and Australia outperformed.
- Brent oil edged up 0.1% to $67.78.
- Gold remained near 1-week high.
- China’s Bank Sector
- MSCI China Banks Index +12% YTD, outperforming broader market.
- Boosted by:
- Fiscal support for real estate and local government finances.
- Lower credit risks and stronger capital buffers.
- Rising loan demand (+5% YoY in June).
- Valuations remain attractive (P/E 5.91 vs 12.1 market average).
Corporate & Tech News
- xAI Launches Grok Imagine
- Generates videos from text/images.
- “Spicy mode” allows suggestive content for premium users.
- Reflects Elon Musk’s push for fewer AI restrictions.
- Raises ethical concerns over deepfakes and misuse.
- Apple’s AI Plans
- Building ChatGPT-style “answer engine” under new internal team.
- Aims to reduce reliance on Google search tools.
- Could integrate into Siri, Safari, and other Apple products.
- May reshape Apple’s assistant and search experience.
- NASA Satellite Shutdown
- Trump admin orders termination of two CO₂-monitoring missions.
- No official reason, but linked to climate change skepticism.
- Could harm climate tracking, forecasting, and science.
Crypto & Digital Assets
- Bitcoin Milestone
- Closed July at $115,644 – highest monthly close ever.
- Absorbed $9B transfer from a Satoshi-era wallet.
- IMF-led update to SNA includes crypto in national wealth data.
- Crypto now counted as “non-produced nonfinancial assets.”
- Ethereum Treasury Surge
- 20 straight days of net ETF inflows in July, $5.4B total.
- 1.26 million ETH (~1% supply) bought by corporates since June.
- BitMine is the largest public ETH holder (833k ETH).
- Institutional focus on ETH’s staking, DeFi, and programmability.
- Standard Chartered forecasts ETH treasury share to grow to 10%.
DAX Technical Analysis 4 hour
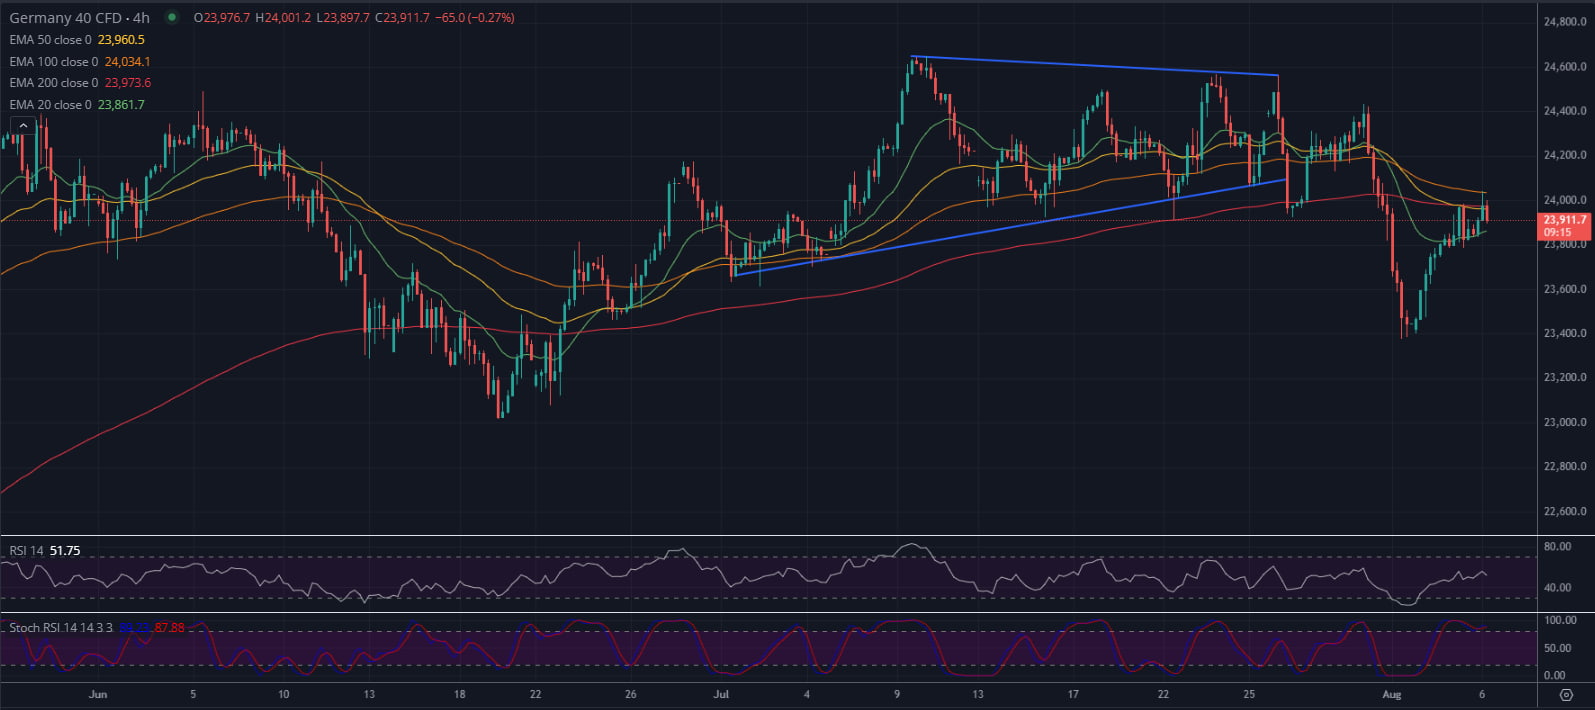
The DAX has bounced back after a deep pullback, recovering above the 200 EMA and re-entering the former ascending channel. However, the price remains below the confluence of the 50 EMA and prior horizontal resistance at 23,950–24,000, which continues to act as a key pivot zone. The latest candle suggests rejection from this area, keeping near-term momentum uncertain.
The RSI has returned to neutral territory near 50, while the Stochastic RSI is approaching overbought levels, suggesting potential slowing in bullish momentum. Bulls will want to see a break and close above 24,000 to confirm a continuation of the rebound, while failure to hold above the 23,860 zone could trigger another leg lower. Price action remains caught between the moving averages and the boundaries of the previous consolidation structure, making the next breakout direction crucial for short-term bias.
--Written by Philip Papageorgiou – Market Analyst
-Follow me on X ex Twitter: PhilipForexCom
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


GBP/USD, DAX Forecast Two trades to watch 220926
GBP/USD struggles as UK government borrowing exceeds forecasts, putting pressure on Healey ahead of the Budget. DAX eases back after yesterday's gains as oil prices and political headwinds rise.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.