





ECB What did we learn today EURUSD
Pandemic Emergency Purchase Program (PEPP) purchases over the next quarter will be significantly faster.
Share this:
The ECB had their March Interest Rate Decision meeting earlier. Expectations ranged across the board; however, nothing was too significant. The main takeaway from the meeting and the press conference was as expected, not too significant. The ECB said that given the uptick in inflation and inflation expectations recently, Pandemic Emergency Purchase Program (PEPP) purchases over the next quarter will be significantly faster. In addition, PEPP will run at least through the end on March 2022. ( This did not change, though some expected them to increase the duration.) Recall that one of the main benefits of PEPP is that the ECB is not tied to any specific amount they need to purchase at one time. The ECB has 1.85 trillion Euros to spend, at their discretion, to keep yields low. This differs from the FED, which is committed to buying $80 billion of Treasuries and $40 billion of MBS per month. Christine Lagarde said PEPP is not Yield Curve Control. (However, it essentially is. The ECB will buy bonds in the part of the yield curve where yields are rising the most.)
Theoretically, buying more bonds should decrease yields, which should bring down the value of the Euro. If the ECB is now buying MORE bonds than they were previously, and the Fed is buying the SAME amount, EUR/USD should move lower.
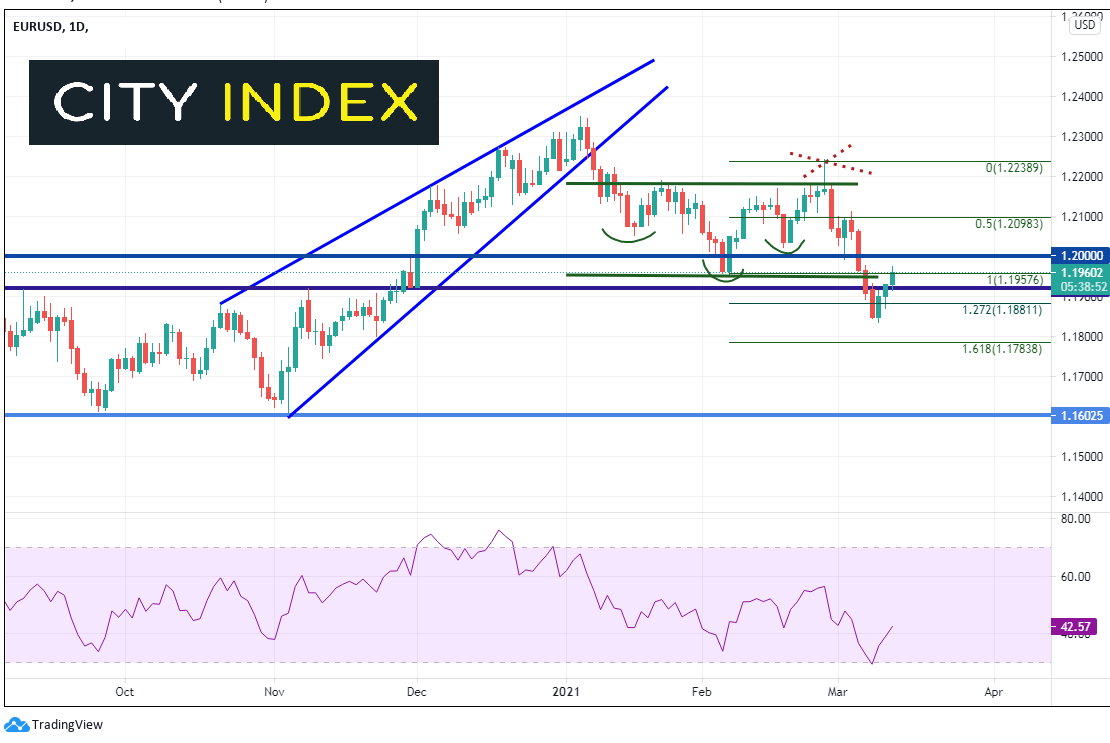
EUR/USD has been moving lower since February 25th, when the US 7-year note action went poorly. The pair moved to the 127.2% Fibonacci extension from the February 5th lows to the February 25th highs near 1.1840, and bounce to today’s highs near 1.1975. Resistance sits just above at 1.1990 and the psychological round number resistance at 1.2000.
Source: Tradingview, City Index
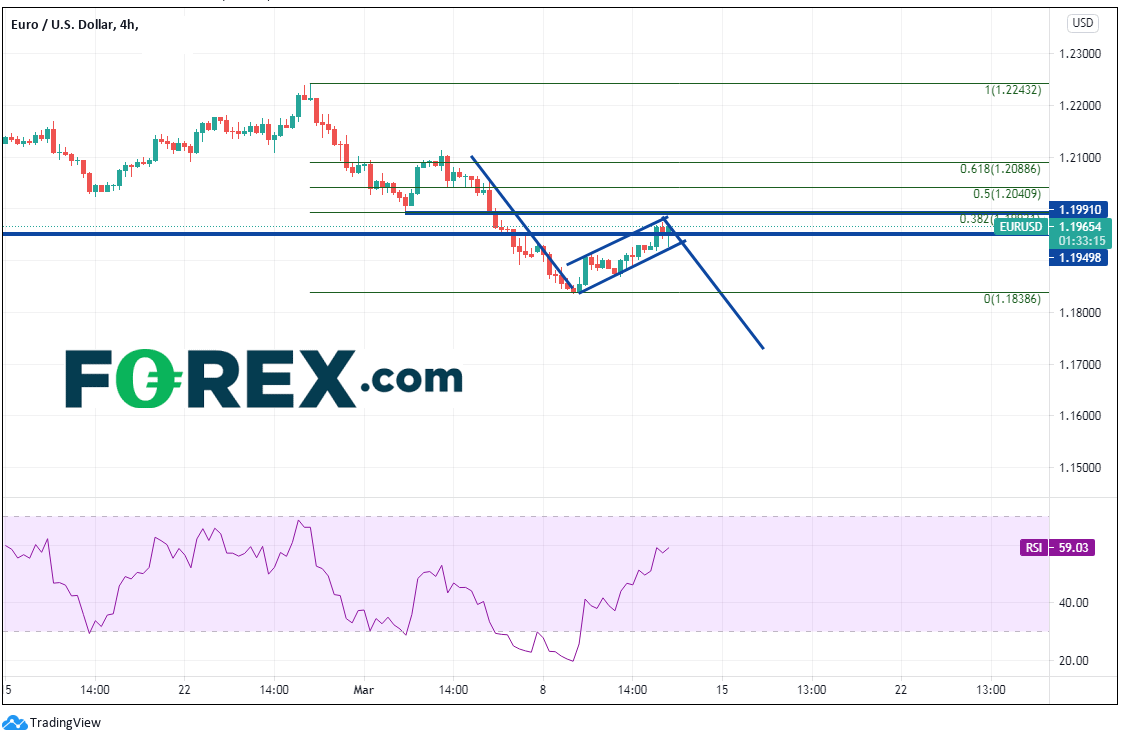
On a 240-minute timeframe, EUR/USD has formed a flag pattern. Notice that the top trendline of the flag pattern confluences with horizontal resistance (from the daily) and the 38.2% Fibonacci retracement from the highs of February 25th to the lows of March 9th near 1.1990. The target for flag pattern is the length of the flagpole added to the breakout point, which is currently near 1.1730. First support is back at the March 9th lows near 1.1838. Below there is the 161.8% Fibonacci extension from the timeframe mentioned on the daily chart neat 1.1738, and then the November 4th lows near 1.1602.
Source: Tradingview, City Index
The FOMC meets next week. If the ECB accelerates the pace of their bond purchases and the FOMC continues its bond buying program at $80 billion in Treasuries and $40 billion in MBS per month, it should cause European yields (bunds) to move lower relative to those from the US. This would cause the Euro to move lower relative to the US Dollar.
It’s time to start thinking about the FOMC meeting results on March 17th!
Learn more about forex trading opportunities.
The ECB had their March Interest Rate Decision meeting earlier. Expectations ranged across the board; however, nothing was too significant. The main takeaway from the meeting and the press conference was as expected, not too significant. The ECB said that given the uptick in inflation and inflation expectations recently, Pandemic Emergency Purchase Program (PEPP) purchases over the next quarter will be significantly faster. In addition, PEPP will run at least through the end on March 2022. ( This did not change, though some expected them to increase the duration.) Recall that one of the main benefits of PEPP is that the ECB is not tied to any specific amount they need to purchase at one time. The ECB has 1.85 trillion Euros to spend, at their discretion, to keep yields low. This differs from the FED, which is committed to buying $80 billion of Treasuries and $40 billion of MBS per month. Christine Lagarde said PEPP is not Yield Curve Control. (However, it essentially is. The ECB will buy bonds in the part of the yield curve where yields are rising the most.)
Theoretically, buying more bonds should decrease yields, which should bring down the value of the Euro. If the ECB is now buying MORE bonds than they were previously, and the Fed is buying the SAME amount, EUR/USD should move lower.
EUR/USD has been moving lower since February 25th, when the US 7-year note action went poorly. The pair moved to the 127.2% Fibonacci extension from the February 5th lows to the February 25th highs near 1.1840, and bounce to today’s highs near 1.1975. Resistance sits just above at 1.1990 and the psychological round number resistance at 1.2000.
Source: Tradingview, FOREX.com
On a 240-minute timeframe, EUR/USD has formed a flag pattern. Notice that the top trendline of the flag pattern confluences with horizontal resistance (from the daily) and the 38.2% Fibonacci retracement from the highs of February 25th to the lows of March 9th near 1.1990. The target for flag pattern is the length of the flagpole added to the breakout point, which is currently near 1.1730. First support is back at the March 9th lows near 1.1838. Below there is the 161.8% Fibonacci extension from the timeframe mentioned on the daily chart neat 1.1738, and then the November 4th lows near 1.1602.
Source: Tradingview, FOREX.com
The FOMC meets next week. If the ECB accelerates the pace of their bond purchases and the FOMC continues its bond buying program at $80 billion in Treasuries and $40 billion in MBS per month, it should cause European yields (bunds) to move lower relative to those from the US. This would cause the Euro to move lower relative to the US Dollar.
It’s time to start thinking about the FOMC meeting results on March 17th!
Learn more about forex trading opportunities.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.