



Equities November reign SP500
For equity portfolios, it’s been an incredible month. European equities have been the standout, currently up ~15%, overshadowing both our personal favourite the S&P500 (+11.25%) and the high beta Nasdaq (+10.90%).
Share this:
After an equity rally of such magnitude and as bonds are set to finish the month flat there has been an expectation that asset managers who run balanced funds that consist of a 60:40 split between stocks and bonds would rebalance/reduce equity exposure into month-end.
Some of the world’s largest pension funds including the Japanese GPIF and the Norwegian Oil fund are thought to use the 60:40 asset allocation split. In all, balanced funds are thought to manage over $7tr.
Of course, asset managers don’t leave all their rebalance until the last day of the month. Rather the flows are spread out over several days. Which means that more likely than not the lion’s share of this month’s rebalance has already gone through without leaving even the faintest footprint.
When looking for reasons as to how the market has been able to absorb such sizeable selling, the answer is thought to come from the staggering amount of equity inflows following the U.S. election and the announcement of successful COVID19 vaccine trials.
Over the past three weeks, it is estimated there has been over $100bn worth of equity inflows, the largest ever amount over a three week period that only partially reverses almost two years of outflows.
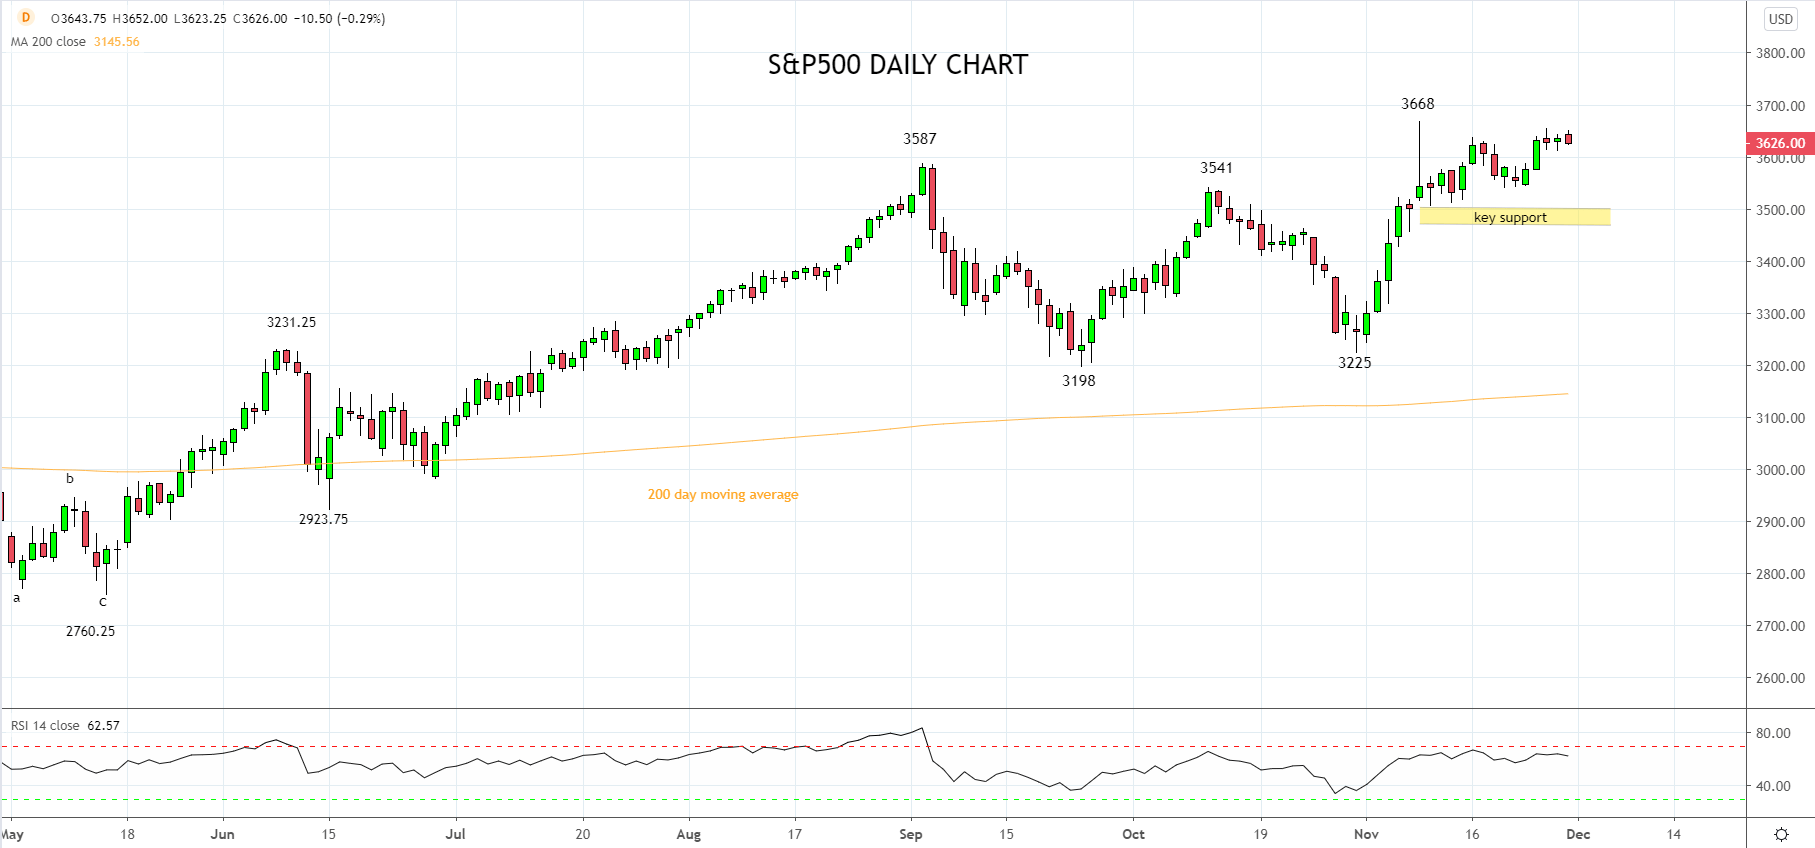
Returning to the S&P 500, following its new all-time high at 3668, the S&P500 has spent the past three weeks consolidating the gains of early November.
In the process it has worked off overbought readings and providing the current period of consolidation/corrective price action extends no lower than wave equality support 3480/70 area, the uptrend is expected to resume into year-end towards 3750/3800.
Aware that a move much below 3470ish would warn that a deeper correction is underway towards the bottom of the range, 3200ish.
Source Tradingview. The figures stated areas of the 30th of November 2020. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.