



EUR/USD forecast: Technical Tuesday | August 25, 2026
The relative calm in the energy and bond markets have allowed the US dollar and equities to make a slightly positive start to the week. America’s economic war on Iran also failed to trigger any panic, leaving investors with little to chew over until the release of US inflation data on Wednesday and Kevin Warsh’s speech at the Jackson Hole Symposium on Friday.
Share this:

The relative calm in the energy and bond markets have allowed the US dollar and equities to make a slightly positive start to the week. America’s economic war on Iran also failed to trigger any panic, leaving investors with little to chew over until the release of US inflation data on Wednesday and Kevin Warsh’s speech at the Jackson Hole Symposium on Friday. For now, consolidation is the name of the game but the risks to the near term EUR/USD forecast remains tilted to the upside.
Could Pakistan help revived US-Iran talks?
Oil prices fell yesterday after the US announced new sanctions on Iran and threatened economic penalties against countries that fail to cut ties with Tehran. China is the obvious focus. A serious revival of US-China trade tensions would be negative for the dollar, consistent with the currency’s relationship with the trade dispute last year.
Markets are hoping that the new wave of sanctions could bring Tehran back to the negotiating table, which partly explains why the price of oil has fallen back in the last couple of days.
Apparently, there is also a fresh push from Pakistan to try and re-start the stalled talks. Al-Arabiya reported that Pakistan’s Asim Munir is carrying an offer to Tehran to halt the siege and lift sanctions under the memorandum of understanding. Oil fell by an additional 3% on the back of this MF Albright it remains to be seen whether the losses will hold and whether this will lead to anything significant between the two sides.
German economy continues to surprise: Ifo rises to 1-year high
One of Germany’s most important leading indicators, the Ifo index, which is based on surveyed manufacturers, builders, wholesalers, services and retailers, once again came out stronger than expected this morning. Despite everything that’s going on right now, most worryingly in the energy market, the Ifo increased to 88.8 in August, from 86.6 in July. The index has now risen for the fourth consecutive month to a one-year-high. Not only did the surgery’s current assessment improved, but so too did the expectations component.
The latest data shows Germany’s economy and sentiment has become immune to the oil shock to some degree, which explains why the DAX is trading close to record highs and why the euro refuses to succumb to pressure.
Bond market uncertainty lingers for the dollar ahead of key data
The US dollar continues to take its cue from the bond market, where a firmer session yesterday eased some pressure on the greenback. Yields remain near multi-year highs, however, and any further signs of stress here could easily send the greenback lower once more.
Some attention will be on US data this week, ahead of Jackson Hole summit. Today, attention turns to housing figures and August consumer confidence, following softer readings in June and July.
The balance of risks for the dollar remains tilted to the downside, although the next decisive move is unlikely to happen until Kevin Warsh’s speech at Jackson Hole on Friday.
Technical EUR/USD forecast: Bear trap?
The EUR/USD chart may be looking a little more bearish again after two consecutive doji candles following the recent sharp advance. But is this simply another trap for the bears?
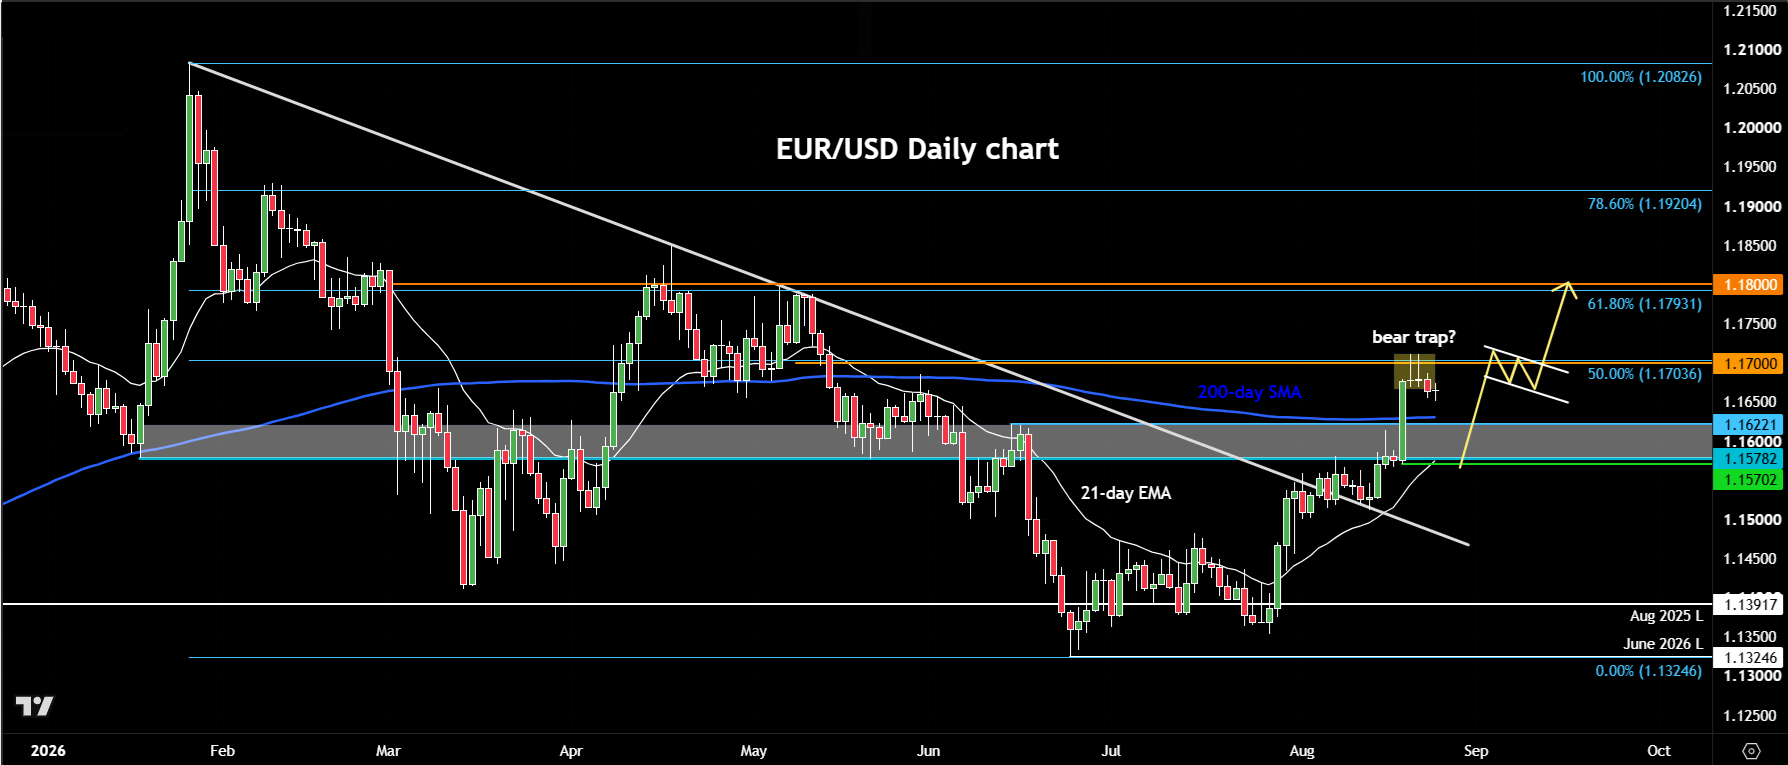
The technical EUR/USD forecast has turned decisively more constructive following the break above the previous bearish trend and the subsequent upside follow-through. The pair has already reached its first major target around 1.1700, where the 50% Fibonacci retracement of the January-to-June decline comes into play. It has since stalled at this level, forming two doji candles over the past two sessions.
In isolation, that would normally be interpreted as a warning sign for the bulls. But context matters. Given the scale of the preceding breakout, the current pause could instead prove to be a bear trap. A modest pullback would not necessarily change the broader picture and could even help clear out some of the recent long positions before another attempt higher.
On the downside, the 1.1575–1.1625 area is now the key support zone. The upper end of this range is roughly where the 200-day moving average comes into play, while the lower end marks the origin of the recent breakout.
As long as EUR/USD holds above 1.1575, the technical bias remains bullish. A sustained move back below this level, however, would weaken the current bullish structure and raise the prospect that the breakout was ultimately a false one.
Above 1.1700, attention would turn towards 1.1800, where the 61.8% Fibonacci retracement of the January-to-June decline sits. For now, the key question is whether this latest pause develops into a deeper correction – or simply sets the stage for another leg higher. For what it is worth, I think the latter.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.