




GBP/USD and EUR/USD in focus for UK and euro CPI reports
Inflation reports for the UK and eurozone put GBP/USD and EUR/USD firmly onto trader's radars, although options markets suggest the UK report is the more important of the two.
Share this:

Asian Indices:
- Australia's ASX 200 index rose by 33.6 points (0.46%) and currently trades at 7,317.40
- Japan's Nikkei 225 index has risen by 74.59 points (0.23%) and currently trades at 32,493.89
- Hong Kong's Hang Seng index has fallen by -242.34 points (-1.27%) and currently trades at 18,773.38
- China's A50 Index has fallen by -62.49 points (-0.5%) and currently trades at 12,520.94
UK and Europe:
- UK's FTSE 100 futures are currently down -4.5 points (-0.06%), the cash market is currently estimated to open at 7,449.19
- Euro STOXX 50 futures are currently up 1 points (0.02%), the cash market is currently estimated to open at 4,370.73
- Germany's DAX futures are currently down -20 points (-0.12%), the cash market is currently estimated to open at 16,105.49
US Futures:
- DJI futures are currently up 11 points (0.03%)
- S&P 500 futures are currently down -2 points (-0.04%)
- Nasdaq 100 futures are currently down -13.5 points (-0.08%)
UK inflation date is the main calendar event at 07:00 BST ahead of the UK open, where everyone including the BOE is likely crossing their fingers for a much softer print. UK data has continued to outperform expectations overall, and in particular we’ve seen employment remain firm and wages rise which feeds back into higher inflation and a more hawkish BOE. A soft report could reduce expectations of another 50bp hike and send GBP pairs lower from arguably overbought levels. Whilst another undesirably hot report could send GBP/USD to new cycle highs.
It is then on to European inflation data at 10:00 BST where hopes of lower CPI numbers feeds into some of the more dovish (or perhaps less hawkish) comments we’ve heard from ECB members this week. Whilst another hike on July 27th is practically a given, the September hike is far less certain than it previously was and hinges upon economic data leading into it. Therefore, a soft CPI print today could weigh on the euro as hawkish bets are scaled back.
- Goldman Sachs, Tesla, Netflix, IBM and United Airlines report earnings
- The FTSE 100 failed to break beneath 7400 to confirm our bearish bias, although prices remain beneath Friday’s bearish pinbar high which keeps a break beneath 7400 on the cards for a potential swing trade short if sentiment sours. A break above Friday’s high could suggest a run for trend resistance from the April high.
- Gold posted strong gains yesterday and stopped just shy of the lower 1985 target, but a move to $2000 remains a possibility and we suspect dips will be bought by gold bugs ($1970 and 1964 are potential support levels)
- WTI crude oil has pulled back from yesterday’s high overnight, which means the $76 handle and YTD open at 75.67 remains to be a key level of resistance and a likely pivotal level for traders
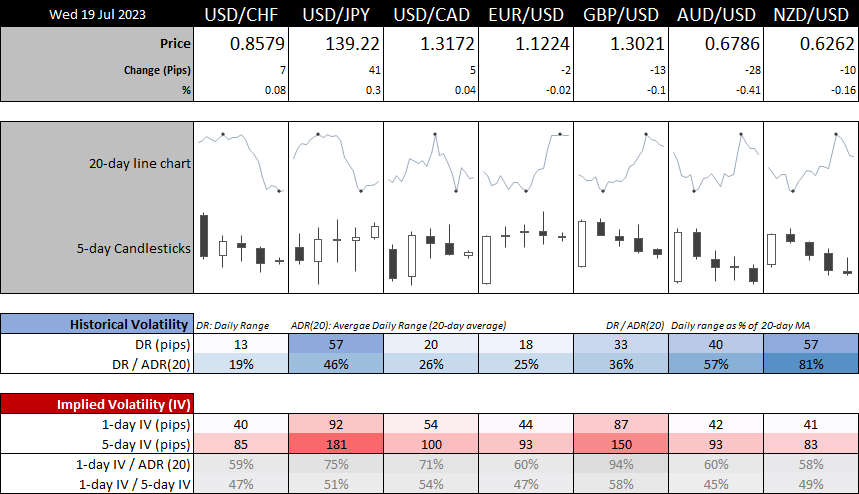
- Volatility for FX majors was contained overnight overall, although there was little economic data beyond New Zealand’s CPI report.
- AUD/USD and NZD/USD daily ranges were just 57% and 81% of their ADR(20) despite the NZ CPI report, whilst USD/JPY was less than half.
- GBP/USD, EUR/USD traded in tight ranges ahead of key inflation reports for the UK and eurozone
- 1-day implied volatility amongst FX majors is GBP/USD at 94% of its ADR(20), so volatility is expected but not at an extreme level relative to a typical daily range
- The same measure for EUR/USD is just 60%, meaning traders suspect the UK inflation report is the more important where monetary policy is concerned
GBP/USD daily chart:
GBP/USD has produced a very clean and strong bullish trend on the daily chart, thanks to outperforming economic data and renewed bets of a higher terminal BOE rate. However, GBP/USD has now retraced for three days (and currently lower for its fourth) ahead of today’s key inflation print. And with it holding above 1.30 / April 2022 low, it may prove to be a springboard for prices as bulls step in if inflation is hot today. The 1day upper implied volatility band is around yesterday’s high which makes a potential target for bulls. But if inflation is too far above expectations, a break to new highs seems probable. A break below 1.30 invalidates the near-term bullish bias.


EUR/USD daily chart:
EUR/USD has risen just over 4% in the past eight days thanks to softer US inflation data. Whilst it made minced meat of the 1.10 and 1.11 handles, it appears a little more cautious above 1.1200, with an open-close range of just 9 pips and a bearish pinbar candle forming yesterday. Whilst a single candle do not mean a reversal is imminent, it does shows a failed attempt to close higher from the bull camp. And if eurozone CPI is soft enough today I suspect it could trigger a decent pullback below 1.1200 as mean reversion finally kicks in and retrace closer towards 1.1100. However, a hot print could send it closer to 1.13, although bulls may need to question how much juice is left in its bullish tank after such a strong rally and remain nimble.


View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.
The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.


EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.