



European Open NZ Avoids Double Dip Recession EURNZD in Focus
New Zealand’s strong GDP beat the consensus and RBNZ’s gloomy expectations for a contraction in Q1. And that makes EUR/NZD of interest given it has struggled to hold above 1.7000.
Share this:
- Traders are downbeat heading into this week’s US-China trade talks in Washington DC after last night’s announcement that the Trump Administration would be blacklisting eight Chinese technology giants, today’s rumors that US government pensions would curtail investments in Chinese stocks, and the announcement of visa bans on Chinese officials from the Xinjiang province. At a minimum, traders will be looking for another delay to the next round of tariff escalation to declare the talks a success.
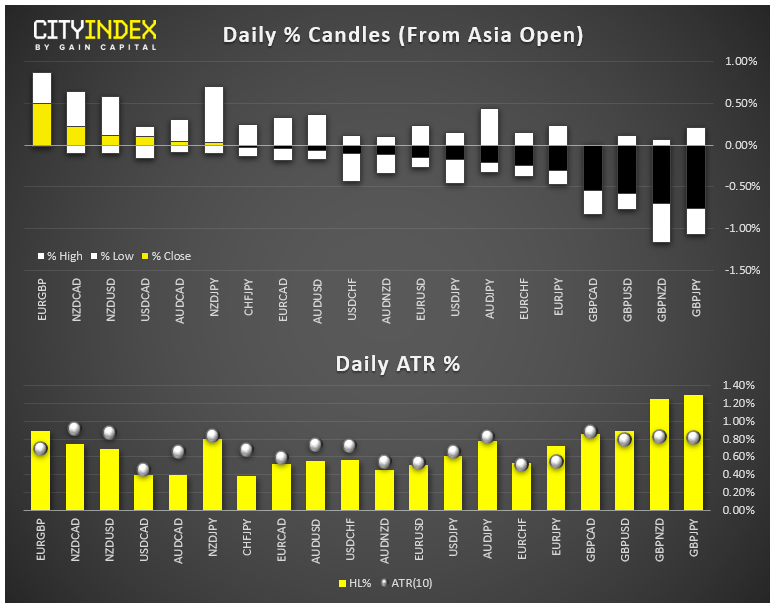
- FX: The British pound was the weakest major currency as Boris Johnson’s Brexit proposal looks increasingly unlikely to garner approval from the European Union. Speaking of Europe, the euro was the second-weakest major currency today, with a German official stating there is no need for a fiscal stimulus package. There was a three-way tie for the strongest major currency between the New Zealand dollar, Swiss franc, and Japanese yen.
- US data: PPI (Sept) printed at -0.3% m/m, well below the +0.1% reading expected. Core PPI also missed at -0.3% m/m vs. +0.2% eyed. A weak CPI report later this week could help cement the case for an interest rate cut from the Federal Reserve at the end of the month.
- Commodities: Gold edged higher on the day while oil ticked lower after the EIA cuts its forecast for 2020 world oil demand.

- US indices closed more than -1% lower across the board on US-China concerns. See what we'll be watching in the upcoming earnings season!
- All eleven sectors fell on the day, led lower by Financials (XLF). REITs (XLRE) fell the least on the day.
- Stocks on the move:
- Domino’s Pizza (DPZ) gained 5% after the company announced a $1B buyback program, despite cutting its outlook for the next three years.
- Chinese company stocks like Alibaba (BABA, -4%), JD.com (JD, -4%) and Baidu (BIDU, -2%) all slide on reports that the White House was considering limits on Chinese stock holdings in government pension funds.
- Big US banks like Bank of America (BAC, -2%) and JP Morgan Chase (JPM, -2%) slid amidst a drop in Treasury yields.


- Traders are downbeat heading into this week’s US-China trade talks in Washington DC after last night’s announcement that the Trump Administration would be blacklisting eight Chinese technology giants, today’s rumors that US government pensions would curtail investments in Chinese stocks, and the announcement of visa bans on Chinese officials from the Xinjiang province. At a minimum, traders will be looking for another delay to the next round of tariff escalation to declare the talks a success.
- FX: The British pound was the weakest major currency as Boris Johnson’s Brexit proposal looks increasingly unlikely to garner approval from the European Union. Speaking of Europe, the euro was the second-weakest major currency today, with a German official stating there is no need for a fiscal stimulus package. There was a three-way tie for the strongest major currency between the New Zealand dollar, Swiss franc, and Japanese yen.
- US data: PPI (Sept) printed at -0.3% m/m, well below the +0.1% reading expected. Core PPI also missed at -0.3% m/m vs. +0.2% eyed. A weak CPI report later this week could help cement the case for an interest rate cut from the Federal Reserve at the end of the month.
- Commodities: Gold edged higher on the day while oil ticked lower after the EIA cuts its forecast for 2020 world oil demand.
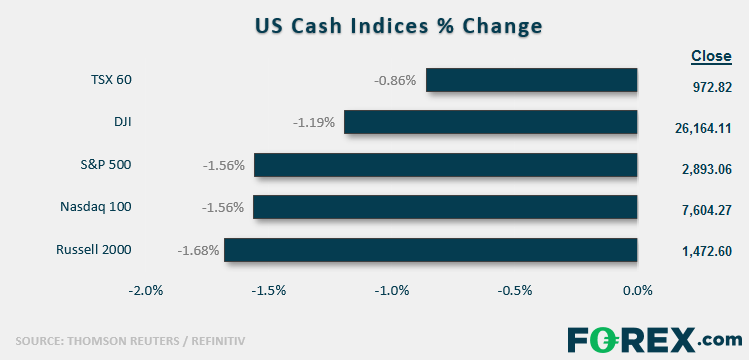
- US indices closed more than -1% lower across the board on US-China concerns.
- All eleven sectors fell on the day, led lower by Financials (XLF). REITs (XLRE) fell the least on the day.
- Stocks on the move:
- Domino’s Pizza (DPZ) gained 5% after the company announced a $1B buyback program, despite cutting its outlook for the next three years.
- Chinese company stocks like Alibaba (BABA, -4%), JD.com (JD, -4%) and Baidu (BIDU, -2%) all slide on reports that the White House was considering limits on Chinese stock holdings in government pension funds.
- Big US banks like Bank of America (BAC, -2%) and JP Morgan Chase (JPM, -2%) slid amidst a drop in Treasury yields.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.