




European Open: Silver’s rally has been strong, but a pullback could be due
Silver prices have rallied nearly 40% since the September low, yet key resistance looms around $25 and a multi-week bearish divergence is forming.
Share this:
Asian Indices:
- Australia's ASX 200 index rose by 113 points (1.63%) and currently trades at 7,059.20
- Japan's Nikkei 225 index has fallen by -373.51 points (-0.0143%) and currently trades at 25,720.99
- Hong Kong's Hang Seng index has risen by 400.63 points (1.99%) and currently trades at 20,545.92
- China's A50 Index has risen by 1.03 points (0.01%) and currently trades at 12,978.00
UK and Europe:
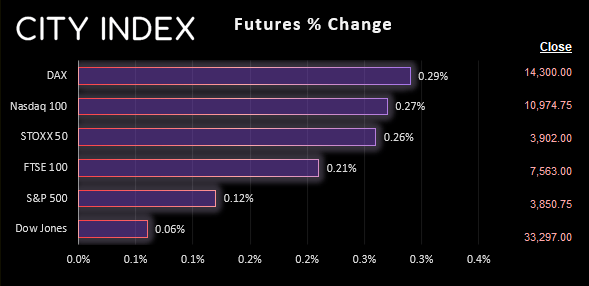
- UK's FTSE 100 futures are currently up 14 points (0.19%), the cash market is currently estimated to open at 7,568.09
- Euro STOXX 50 futures are currently up 11 points (0.28%), the cash market is currently estimated to open at 3,893.29
- Germany's DAX futures are currently up 44 points (0.31%), the cash market is currently estimated to open at 14,225.67
US Futures:
- DJI futures are currently up 13 points (0.04%)
- S&P 500 futures are currently up 25.25 points (0.23%)
- Nasdaq 100 futures are currently up 3.5 points (0.09%)

It was a mixed session for equity markets overnight with indices for China rising over 2% and the ASX erasing most of Tuesday’s losses and up around 1.5%. Investors remain upbeat on China’s reopening despite the rise in Covid cases. Yet shares across Japan had some catching up to do on their first trading day of the year and were down around -1.4%. The fact remains that volumes remains well below their usual levels and directional movements appear fickle.
German consumer prices fell to 8.6% y/y from 10%, which likely marks peak inflation at 10.4% two months prior. The -1.4% percentage point drop of the annual rate was its most aggressive since 1992, and the m/m rate contracted for the first time in a year at -0.5% (which was is fastest contraction in two years). With producer and wholesale prices also tumbling, it’s looking like the worst is behind Germany which is great news for the EU overall.
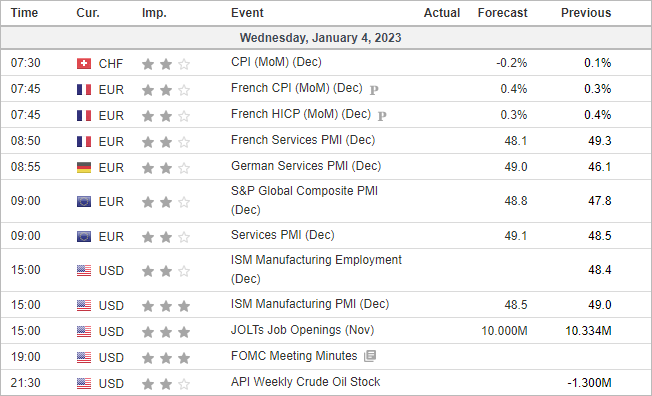
France release inflation data at 07:45 but it is expected to tick higher to 6.4% y/y (6.2% previously whilst core inflation is forecast to rise to 7.2% y/y (7.1% previously). PMI data is also scheduled today for Sweden, France, Spain, Italy and Germany.
The US session presents the ISM manufacturing report at 15:00 GMT, which is expected to contract for a second month and at its fastest pace since May 2020. With equity markets remaining sensitive to recession concerns that it has the potential to weigh further on Wall Street should it come in worse than already expected. The FOMC December minutes are released at 19:00 GMT where traders will look for further clues of a lower terminal rate, which could be further supportive of gold prices if traders like what they find.
The Australian dollar is the strongest major on China’s recovery hopes, although US indices are yet to show any interest of tracking China’s market’s higher.
EUR/GBP fell to a 7-day in line with yesterday’s bias, thanks to the soft inflation report from Germany. Prices are retracing higher on the intraday timeframes but we would consider fresh bearish setups below 0.8843 for an anticipated move down to the 0.8760 area.
Silver daily chart:
I do not expect this to be a popular view, given the excitement of the rally on metals in general in recent weeks. But no trend lasts for ever and we’ve not really seen much of a pullback on silver prices lately. Besides, silver has risen nearly 40% since the September low and fast approaching the upper trendline from a wide (slightly bearish) channel).


Prices are holding above trend support on the daily chart, but a bearish divergence has been forming with the RSI (14) as its rally has lost steam over the past couple of weeks. A bearish pinbar also suggests bulls are losing control, so we’re now waiting to either see momentum turn lower or provide a series of bearish reversal candles below $25.
The main issue with trying to pick turning points are it can leave one vulnerable to a series of false entries and/or giving up before the turn. Therefore, bears may want to use smaller positions with a wider stop, and fade into spikes below $25 before increasing exposure if momentum does finally turn lower. Alternatively, bears could wait for a break beneath the monthly pivot point to confirm a trend reversal on the daily chart.
Economic events up next (Times in GMT)
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.


AUD/USD forecast: Currency Pair of the Week | September 28, 2026
The week has started with stocks, gold, silver and bitcoin all falling, as crude oil rebounded and bond yields pushed further higher. Trump refusing to agree to Tehran’s proposal to re-open the Strait of Hormuz has left the markets disappointed. Still, reports that mediators are expected to hold talks with the two sides on an amended version of the 7-day proposal that Iran presented, keeps hopes alive that we may see some progress.

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.