







EM FX: Turmoil in emerging currencies pose big risk to markets
It is worth watching EM currencies closely here as there is a risk we could see further, sharp, selling, which, in turn, could provide a fresh source of threat to the global financial markets.
Share this:

While risk assets have been a tad more stable in the last couple of days ahead of US earnings season and CPI next week, we are not out of the woods just yet. So, don’t let the apparent calmness deceive you. Not much has changed fundamentally to suggest the worst is behind us just yet.
The global economy could weaken much more than it is priced in right now. A global recession is looming large, with Europe looking particularly weak. But the situation for some emerging markets is even bleaker. Just take a look at their inflation figures:
| Country | CPI annual inflation |
| SOUTH KOREA | 5.4% |
| SINGAPORE | 5.6% |
| SOUTH AFRICA | 6.5% |
| INDIA | 7.0% |
| THAILAND | 7.1% |
| MEXICO | 7.7% |
| BRAZIL | 11.7% |
| POLAND | 13.9% |
| RUSSIA | 17.1% |
| ARGENTINA | 60.7% |
| TURKEY | 73.5% |
Obviously, the official data might be understating inflation in some of these nations. The actual situation might be a lot worse.
More to the point, the US dollar’s ongoing strength is making the situation even worse in these nations. As EM currencies continue to weaken, costs of import only go up, further weighing on demand.
To prevent their currencies from weakening, central banks in these countries are forced to either introduce capital controls and/or hike interest rates more aggressively than would otherwise be the case. Obviously, I am not talking about the Erdogan-controlled CBRT here, given that it has been doing the opposite! Tighter monetary conditions make it more difficult to emerge from this vicious spiral.
When you consider the fact that the Fed is aggressively tightening, expect a summer of turmoil in EM space. There’s also the risk that inflation in developed economies might prove to be more persistent – something the Fed highlighted the risk of at their last monetary policy sitting, judging from the minutes of that meeting released on Wednesday.
More central banks will be tightening their belts further with the RBNZ and BOC both set for sharp hikes in the week ahead. This will further deliver unwelcome weakness for EM currencies.
So, while things are calm on the surface, it is worth watching EM currencies closely here as there is a risk we could see further, sharp, selling, which, in turn, could provide a fresh source of threat to the global financial markets.
Let’s take a look at some of the most eye-catching moves, featuring PLN, MXN, THB and TRY:
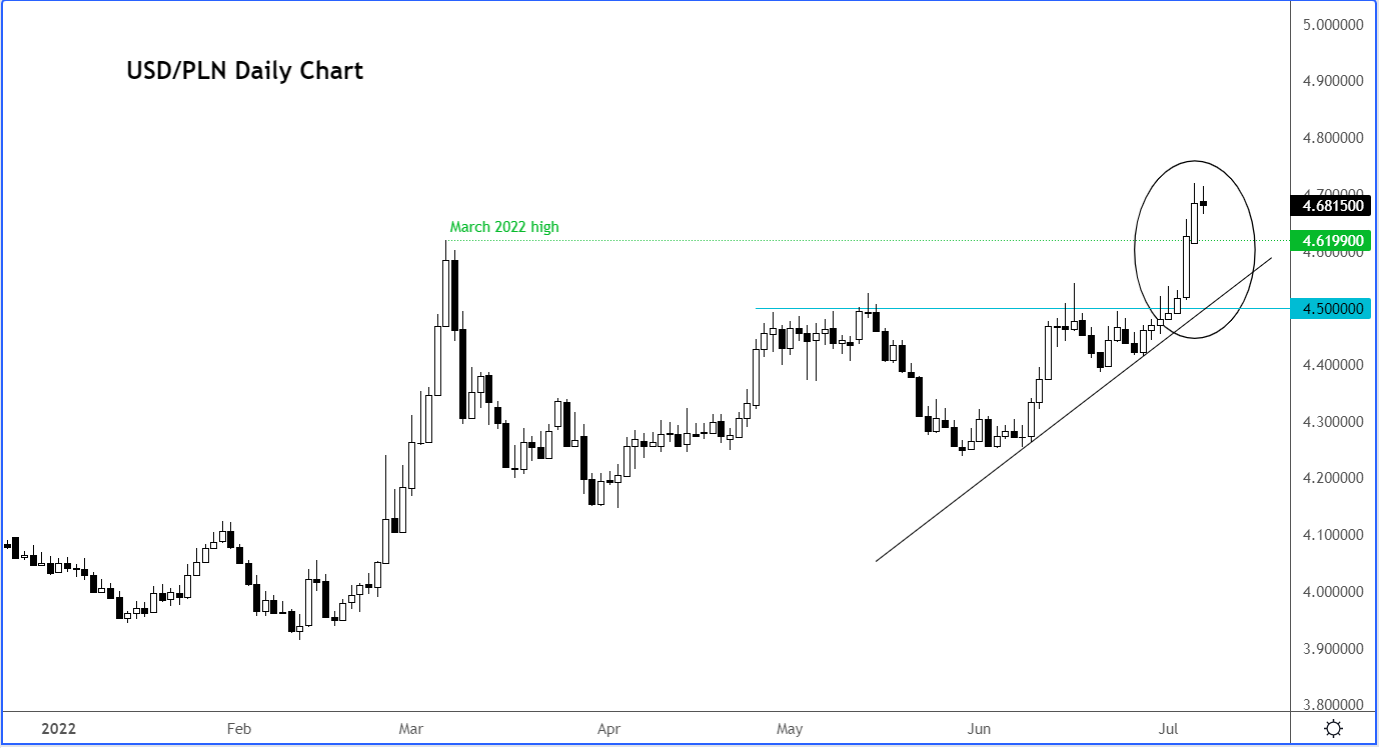
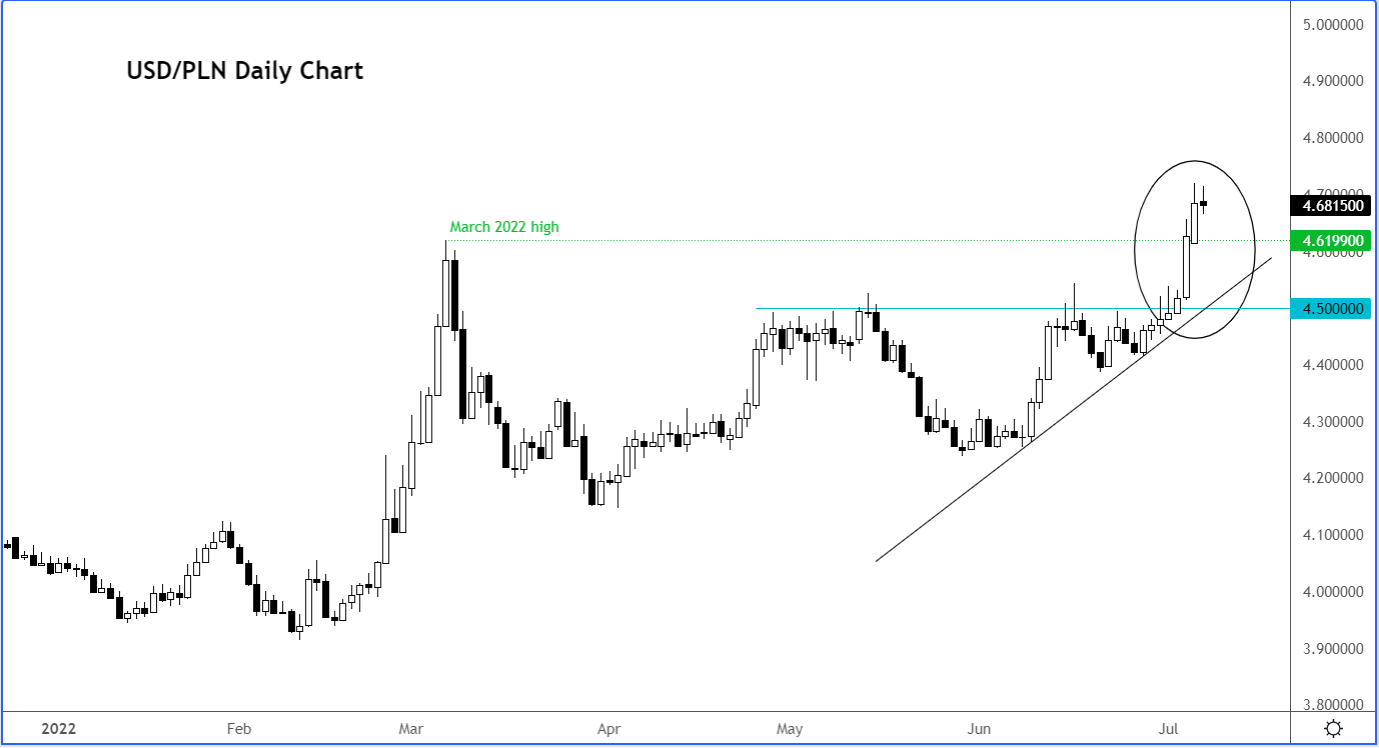
The USD/PLN has just broken to a new high for the year – there’s no stopping this pair now, by the looks of it:
The USD/MXN is attempting a breakout above 20.50, which will also see rates take out the bearish trend line that has been in place since last year.
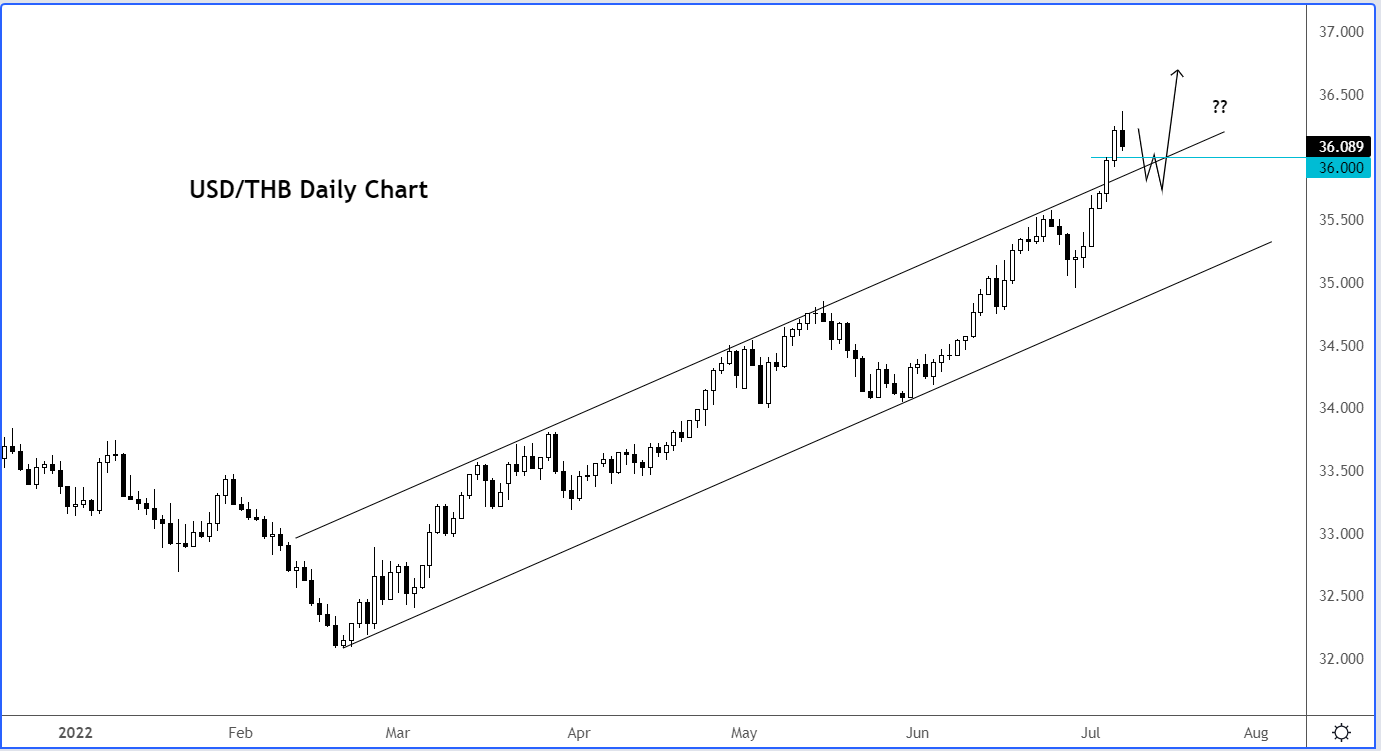
The USD/THB has risen so sharply that it has even broken out of its rising channel. Dip-buying is likely to continue after shallow pullbacks.
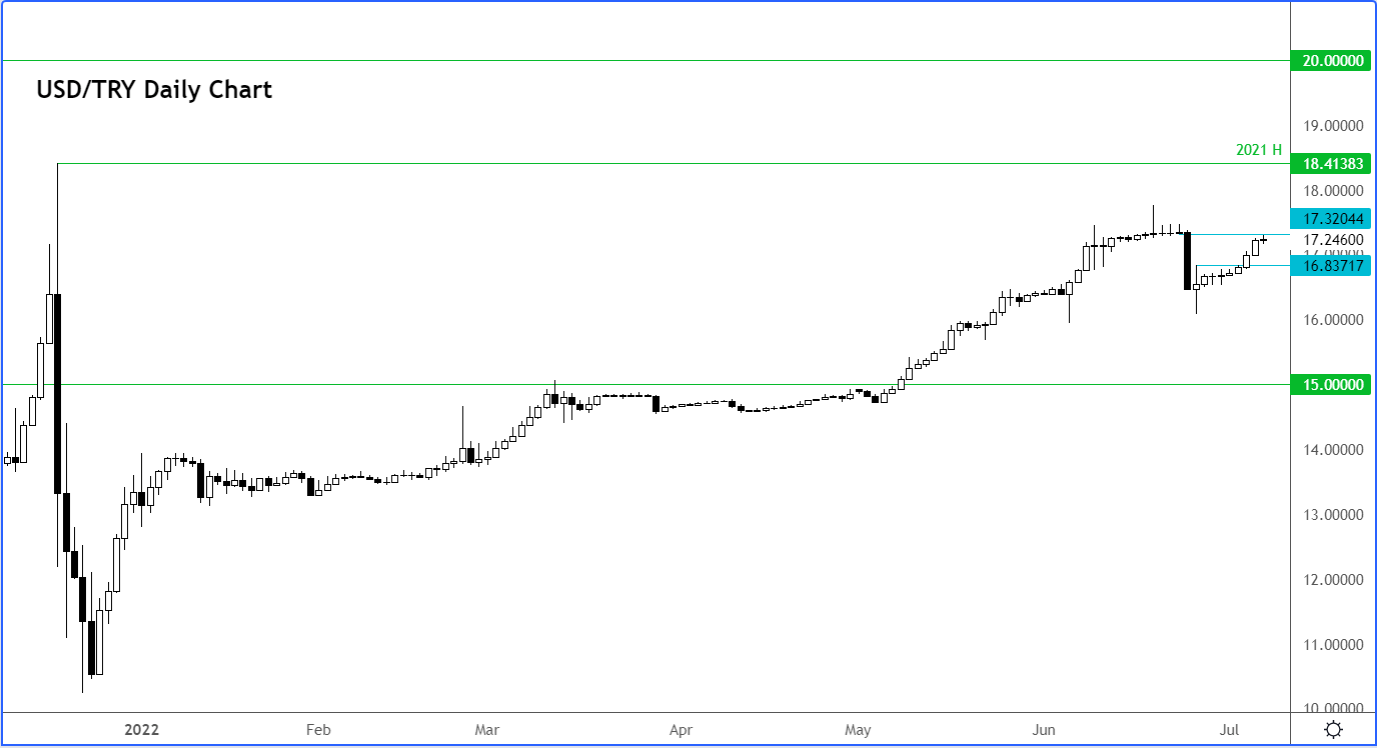
Finally, the USD/TRY looks like it will challenge last year’s high:
The USD/PLN has just broken to a new high for the year – there’s no stopping this pair now, by the looks of it:
The USD/MXN is attempting a breakout above 20.50, which will also see rates take out the bearish trend line that has been in place since last year.
The USD/THB has risen so sharply that it has even broken out of its rising channel. Dip-buying is likely to continue after shallow pullbacks.
Finally, the USD/TRY looks like it will challenge last year’s high:
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.