


Market Brief Boeing Takes Off in HalfHoliday Trade
See a summary of the top market themes and trends from today's US trading session!
Share this:

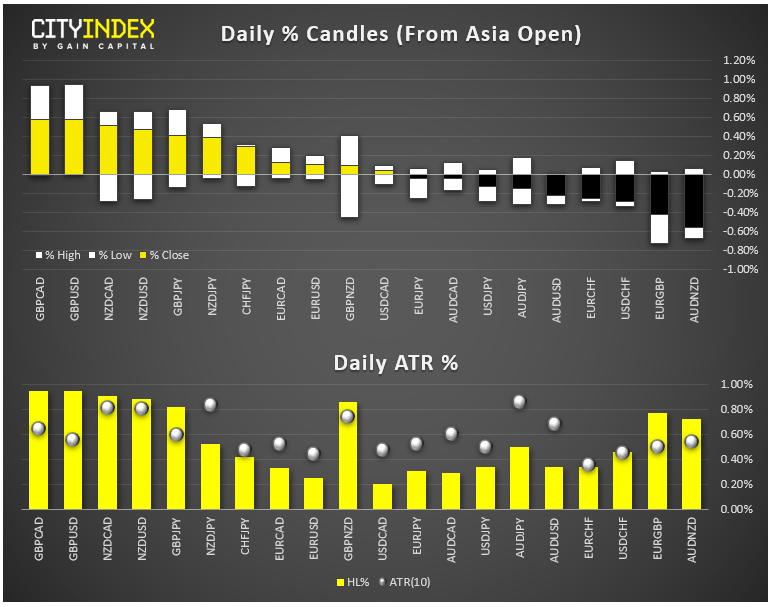
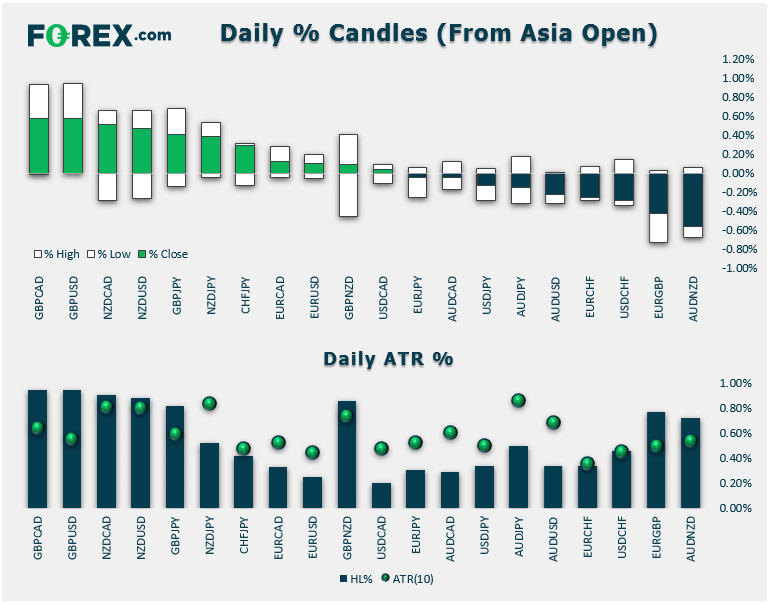
View our guide on how to interpret the FX Dashboard.
- US and Canadian bond markets were closed for Veteran’s Day, leading to lower volatility in other markets and a dearth of economic data releases
- In terms of major news, the headlines that Nigel Farage’s Brexit party would sit out the coming UK election reduced the risk of a hung Parliament and boosted the pound.
- FX: The New Zealand dollar and British pound were the strongest major currencies on the day, while the Australian, Canadian, and US dollar are all vying for the day’s worst performance as of writing.
- Commodities: Gold ticked lower to test a key support level and oil edged lower in a quiet day.

- US indices closed mixed in quiet holiday trade.
- REITs (XLRE) were the strongest major sector on the day; Energy (XLE) brought up the rear.
- Stocks on the move:
- Boeing (BA) rallied 5% after announcing its 737 Max fleet could return to service in January.
- Goldman Sachs (GS) dropped -2% after the NY Department of Financial Services announced a probe into the new Apple Card (AAPL, +1%).
- Alibaba (BABA, -0%) was essentially flat despite announcing its Single’s Day haul of CNY268B ($38B USD).
View our guide on how to interpret the FX Dashboard.
- US and Canadian bond markets were closed for Veteran’s Day, leading to lower volatility in other markets and a dearth of economic data releases
- In terms of major news, the headlines that Nigel Farage’s Brexit party would sit out the coming UK election reduced the risk of a hung Parliament and boosted the pound.
- FX: The New Zealand dollar and British pound were the strongest major currencies on the day, while the Australian, Canadian, and US dollar are all vying for the day’s worst performance as of writing.
- Commodities: Gold ticked lower to test a key support level and oil edged lower in a quiet day.

- US indices closed mixed in quiet holiday trade.
- REITs (XLRE) were the strongest major sector on the day; Energy (XLE) brought up the rear.
- Stocks on the move:
- Boeing (BA) rallied 5% after announcing its 737 Max fleet could return to service in January.
- Goldman Sachs (GS) dropped -2% after the NY Department of Financial Services announced a probe into the new Apple Card (AAPL, +1%).
- Alibaba (BABA, -0%) was essentially flat despite announcing its Single’s Day haul of CNY268B ($38B USD).
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Technical Outlook: AUD/USD Breakdown Threatens Deeper Correction 9 23 2026
AUD/USD remains under pressure after breaking key trend support, with the latest decline putting the focus on the next major downside pivot.

USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.