





Market Brief GBP hurt by poor services PMI
A summary of news and snapshot of moves ahead of the US session.
Share this:

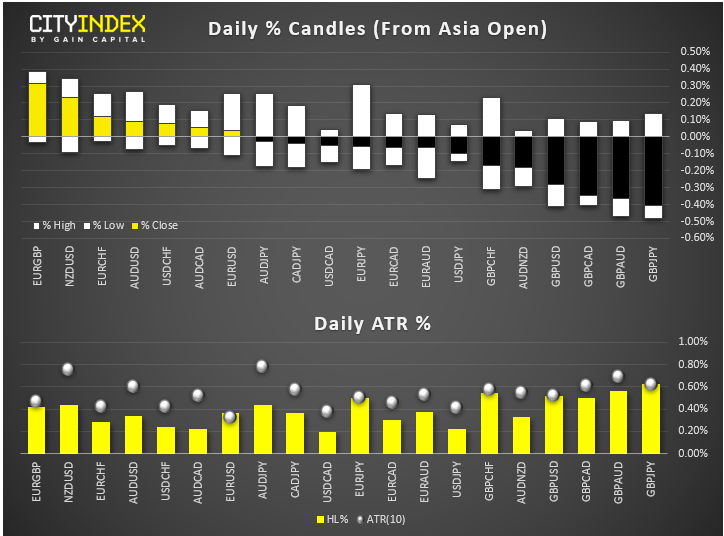
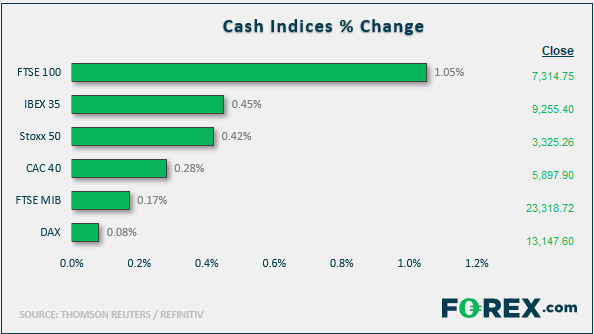
- Market update: In FX, GBP and to a lesser degree EUR sold off this morning although both were off their worst lows but still down on the day following the earlier release of poor services PMI data from the UK and Eurozone. Stocks were higher, although mainland European indices came off their best levels while FTSE was up 1% at the time of writing, supported by a weaker sterling. Gold was up as German, UK and US 10-year yields fell, and the yen strengthened. Crude oil was a touch higher after two days of sharp gains. The price of Bitcoin dropped to its lowest level since May, reaching a low so far of $6930.
View our guide on how to interpret the FX Dashboard
- Christine Lagarde gave her first proper speech as ECB’s president and although she shied away from providing any significant hints about changes in interest rates, she did call for a strategic review of monetary policy in the near future and greater fiscal spending. Read more HERE.
- Data recap: the latest services PMI data from the UK and Eurozone disappointed expectations, hurting both the pound and the euro:
- The Eurozone Composite PMI unexpectedly fell to 50.3 in November from 50.6 in October, worse than expected
- Eurozone Manufacturing PMI remained in the contraction for the 10th consecutive month, coming in at 46.6 vs. 46.4 expected and 45.9 last.
- Eurozone Services PMI fell to a 10-month low of 51.5 vs. 52.2 last and 52.4 expected
- On a country level, French manufacturing PMI rebounded to expansion territory at 51.6 vs. 50.7 last, while services PMI was unchanged at 52.9. German manufacturing PMI improved to 43.8 from 42.1, while services PMI slowed to 51.3 from 51.6.
- UK Flash Services PMI printed 48.6 for November, suggesting the sector contracted. It fell more than one whole point from 50.0 in October and was also worse than 50.1 expected.
- UK flash Manufacturing PMI eases to 48.3 compared with 48.8 expected and 49.6 last.
- Coming up:
- Canadian retail sales: headline expected to print -0.3% m/m vs. -0.1% last; Core expected to come in at -0.1% vs. -0.2% in the previous month
- US Markit Flash Manufacturing and Services PMIs, expected at 51.5 and 51.2 respectively
- Revised UoM Consumer Sentiment and Inflation Expectations
- Market update: In FX, GBP and to a lesser degree EUR sold off this morning although both were off their worst lows but still down on the day following the earlier release of poor services PMI data from the UK and Eurozone. Stocks were higher, although mainland European indices came off their best levels while FTSE was up 1% at the time of writing, supported by a weaker sterling. Gold was up as German, UK and US 10-year yields fell, and the yen strengthened. Crude oil was a touch higher after two days of sharp gains. The price of Bitcoin dropped to its lowest level since May, reaching a low so far of $6930.
View our guide on how to interpret the FX Dashboard
- Christine Lagarde gave her first proper speech as ECB’s president and although she shied away from providing any significant hints about changes in interest rates, she did call for a strategic review of monetary policy in the near future and greater fiscal spending. Read more HERE.
- Data recap: the latest services PMI data from the UK and Eurozone disappointed expectations, hurting both the pound and the euro:
- The Eurozone Composite PMI unexpectedly fell to 50.3 in November from 50.6 in October, worse than expected
- Eurozone Manufacturing PMI remained in the contraction for the 10th consecutive month, coming in at 46.6 vs. 46.4 expected and 45.9 last.
- Eurozone Services PMI fell to a 10-month low of 51.5 vs. 52.2 last and 52.4 expected
- On a country level, French manufacturing PMI rebounded to expansion territory at 51.6 vs. 50.7 last, while services PMI was unchanged at 52.9. German manufacturing PMI improved to 43.8 from 42.1, while services PMI slowed to 51.3 from 51.6.
- UK Flash Services PMI printed 48.6 for November, suggesting the sector contracted. It fell more than one whole point from 50.0 in October and was also worse than 50.1 expected.
- UK flash Manufacturing PMI eases to 48.3 compared with 48.8 expected and 49.6 last.
- Coming up:
- Canadian retail sales: headline expected to print -0.3% m/m vs. -0.1% last; Core expected to come in at -0.1% vs. -0.2% in the previous month
- US Markit Flash Manufacturing and Services PMIs, expected at 51.5 and 51.2 respectively
- Revised UoM Consumer Sentiment and Inflation Expectations
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.