




Market Brief Risk rebounds after restrained retaliation
The aftermath of fresh geopolitical drama is turning out to be muted for global markets
Share this:

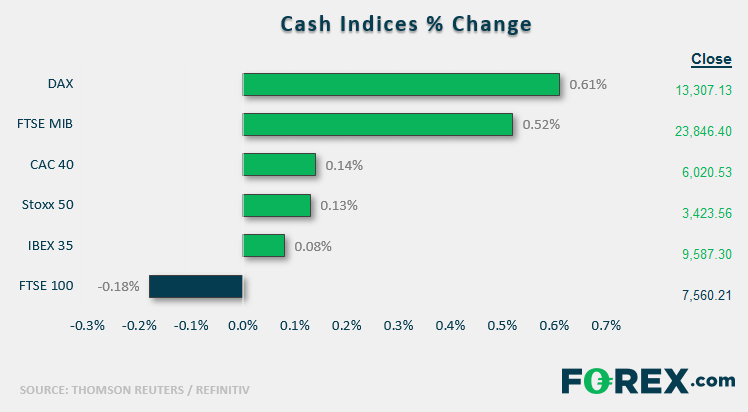
Stock market snapshot as of [8/1/2020 3:45 PM]
- The aftermath of fresh geopolitical drama is less thunderous for global markets than precipitating events
- EMEA indices have been slower to venture into the green than U.S. stocks, though all equity markets remain off lows
- Along the spectrum of ‘retaliation scenarios’ following the U.S. missile attack on one of Iran’s top generals last week, the one that Tehran instigated overnight should rank among the most restrained. Despite more than a dozen missiles reportedly fired on the Ayn al-Asad base in western Iraq and another in Erbil, there were no casualties. Tehran’s subsequent statement framed the move unequivocally, at least at the secular level: “proportionate measures” have been concluded, “we do not seek escalation or war”
- President Donald Trump’s tweeted conclusion that “All is well” was less convincing, but certainly flagged a reduced probability and imminence of escalation. The White House later signalled its interpretation of the attack as designed to satisfy retaliatory imperatives with the most minimal possible response, in order to avoid devastating U.S. counter assault
- Evidently, the view that recent Middle East events have fomented a tinder box, is still prevalent. Yet haven flows have abated considerably since news hit in early European hours. Tell-tale signs of ‘safety seeking’ remain in equity markets too. Select utility stocks see interest. Again though, caution hasn’t overshadowed interest in ‘riskier’ sectors like semiconductors in the wake of better-than forecast Samsung results
- For the near term, markets are likely to stage a second attempt at a gradual return to calm—albeit uneasy—as the one seen in the days following Qasem Soleimani’s death. The risk of continued escalation will continue to lurk in the background though investors are set to apply an increasing discount if Tehran and Washington signals that a line could soon be drawn under the specific matter of Soleimani’s assassination turn out to be correct. A press conference with Donald Trump has been scheduled for 16.00 GMT
Stocks/sectors on the move
- Another sign that European investors aren’t notching ongoing risk assessments at the most elevated levels: chip stocks are participating in sector cheer after Samsung’s better than expected earnings. Samsung’s biggest profit generator, enabled earnings to avoid the lowest forecasts
- Auto industry shares help Europe’s consumer sector into the green, led by Michelin, following a brokerage upgrade. The stock was up 2.2% into U.S. trading
- The weaker sectors were led by UK and French commercial property shares. This follows news that British Land’s proposal of a tower block in a central residential district was rejected. The stock fell 3%
- Boeing fell 1.7%. Grim exoneration is the most probable outcome after the latest tragedy involving a 737. The crash of a flight on its way to Ukraine from Iran involved a predecessor model of the 737 MAX. Boeing has accepted that flight control software known as MCAS played a key part in two fatal crashes between October 2018 and last March. MCAS was specifically developed for the 737 MAX
- Walgreens Boots Alliance tanks almost 7% as core drugstore profits slid in the first quarter, underscoring WBA’s reasons for looking into going private
- Lennar, the big homebuilder, rose 3.4% on better than forecast Q4 sales
- Costco will be the other large cap to help kick off earnings season when it reports after the U.S. close. Its stock traded 0.6% higher
- Macy’s holiday season trading report brought respite to turbulent retail shares after it noted a “strong trend improvement”. Kohl’s, Walmart, Target and Nordstrom were all higher. Macy’s rose 7%
- Beyond Meat and McDonald’s continue an uneasy association. The synthetic-food maker’s stock rose 4% on news that MCD will expand tests of BYND’s plant burger

FX snapshot as of [8/1/2020 3:45 PM]
View our guide on how to interpret the FX Dashboard
FX markets
- Currency trading also reflects the rapid swing from ‘risk-off’ to ‘risk-on’ albeit of the most cautious kind. The dollar index saw losses of around two tenths of a percentage point before rising 0.1% as U.S. stock trading began
- The yen has given up earlier gains of as much as 0.7%. Suspected algo-drive trading had a field day earlier after a deluge of “Iran” and “attack” keywords hit the Twittersphere and beyond. Importers reportedly bought the USD/JPY dip below 108, adding momentum to the bounce
- G10 FX has generally adopted a wait-and-see stance, as pairs drift within 0.3% higher or lower on the day
- EUR/USD sees a 0.3% loss after another slab of soft data, namely an Ifo business sentiment reading and unimpressive German factory orders
Stock market snapshot as of [8/1/2020 3:45 PM]
- The aftermath of fresh geopolitical drama is less thunderous for global markets than precipitating events
- EMEA indices have been slower to venture into the green than U.S. stocks, though all equity markets remain off lows
- Along the spectrum of ‘retaliation scenarios’ following the U.S. missile attack on one of Iran’s top generals last week, the one that Tehran instigated overnight should rank among the most restrained. Despite more than a dozen missiles reportedly fired on the Ayn al-Asad base in western Iraq and another in Erbil, there were no casualties. Tehran’s subsequent statement framed the move unequivocally, at least at the secular level: “proportionate measures” have been concluded, “we do not seek escalation or war”
- President Donald Trump’s tweeted conclusion that “All is well” was less convincing, but certainly flagged a reduced probability and imminence of escalation. The White House later signalled its interpretation of the attack as designed to satisfy retaliatory imperatives with the most minimal possible response, in order to avoid devastating U.S. counter assault
- Evidently, the view that recent Middle East events have fomented a tinder box, is still prevalent. Yet haven flows have abated considerably since news hit in early European hours. Tell-tale signs of ‘safety seeking’ remain in equity markets too. Select utility stocks see interest. Again though, caution hasn’t overshadowed interest in ‘riskier’ sectors like semiconductors in the wake of better-than forecast Samsung results
- For the near term, markets are likely to stage a second attempt at a gradual return to calm—albeit uneasy—as the one seen in the days following Qasem Soleimani’s death. The risk of continued escalation will continue to lurk in the background though investors are set to apply an increasing discount if Tehran and Washington signals that a line could soon be drawn under the specific matter of Soleimani’s assassination turn out to be correct. A press conference with Donald Trump has been scheduled for 16.00 GMT
Stocks/sectors on the move
- Another sign that European investors aren’t notching ongoing risk assessments at the most elevated levels: chip stocks are participating in sector cheer after Samsung’s better than expected earnings. Samsung’s biggest profit generator, enabled earnings to avoid the lowest forecasts
- Auto industry shares help Europe’s consumer sector into the green, led by Michelin, following a brokerage upgrade. The stock was up 2.2% into U.S. trading
- The weaker sectors were led by UK and French commercial property shares. This follows news that British Land’s proposal of a tower block in a central residential district was rejected. The stock fell 3%
- Boeing fell 1.7%. Grim exoneration is the most probable outcome after the latest tragedy involving a 737. The crash of a flight on its way to Ukraine from Iran involved a predecessor model of the 737 MAX. Boeing has accepted that flight control software known as MCAS played a key part in two fatal crashes between October 2018 and last March. MCAS was specifically developed for the 737 MAX
- Walgreens Boots Alliance tanks almost 7% as core drugstore profits slid in the first quarter, underscoring WBA’s reasons for looking into going private
- Lennar, the big homebuilder, rose 3.4% on better than forecast Q4 sales
- Costco will be the other large cap to help kick off earnings season when it reports after the U.S. close. Its stock traded 0.6% higher
- Macy’s holiday season trading report brought respite to turbulent retail shares after it noted a “strong trend improvement”. Kohl’s, Walmart, Target and Nordstrom were all higher. Macy’s rose 7%
- Beyond Meat and McDonald’s continue an uneasy association. The synthetic-food maker’s stock rose 4% on news that MCD will expand tests of BYND’s plant burger
FX snapshot as of [8/1/2020 3:45 PM]
View our guide on how to interpret the FX Dashboard
FX markets
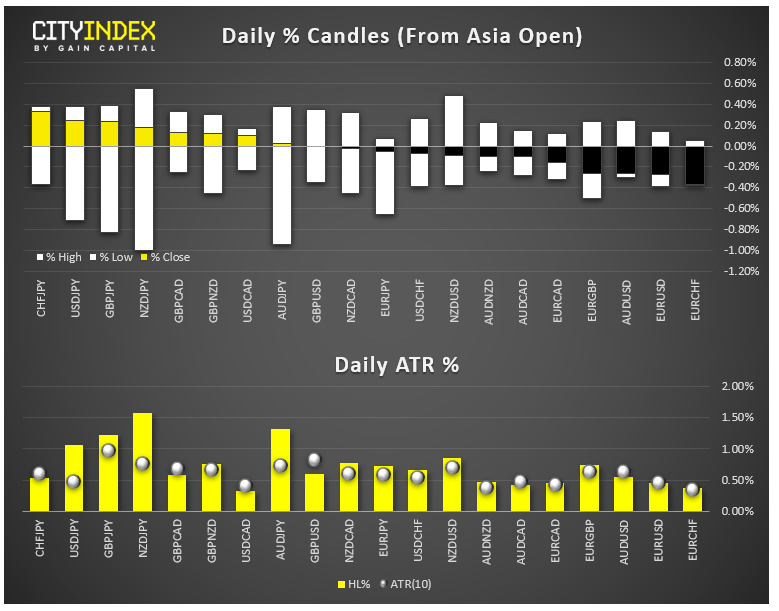
- Currency trading also reflects the rapid swing from ‘risk-off’ to ‘risk-on’ albeit of the most cautious kind. The dollar index saw losses of around two tenths of a percentage point before rising 0.1% as U.S. stock trading began
- The yen has given up earlier gains of as much as 0.7%. Suspected algo-drive trading had a field day earlier after a deluge of “Iran” and “attack” keywords hit the Twittersphere and beyond. Importers reportedly bought the USD/JPY dip below 108, adding momentum to the bounce
- G10 FX has generally adopted a wait-and-see stance, as pairs drift within 0.3% higher or lower on the day
- EUR/USD sees a 0.3% loss after another slab of soft data, namely an Ifo business sentiment reading and unimpressive German factory orders
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions

EUR/USD Forecast: Euro Extends Losses Ahead of Fed Rate Decision
The euro has started to face a more challenging period in the short term. The EUR/USD pair has already declined by nearly 0.81% over the last four trading sessions, a move that has begun to reinforce a meaningful bearish bias in favor of the U.S. dollar.
EUR/USD Analysis: Euro Attempts to Recover Following the ECB Decision
Today's session has been particularly relevant for the euro's performance in the short term. After the EUR/USD registered a decline of nearly 0.3% during the session, the European currency has managed to recover a large part of its losses.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.