





Market Brief Short Covering Rebound
A summary of news and snapshot of moves ahead of the US session.
Share this:

- The AUD is the strongest on RBA inaction and risk rebound, with safe-haven Japanese yen being the weakest after its sharp rally in recent days. EUR has not found much support from strong German data
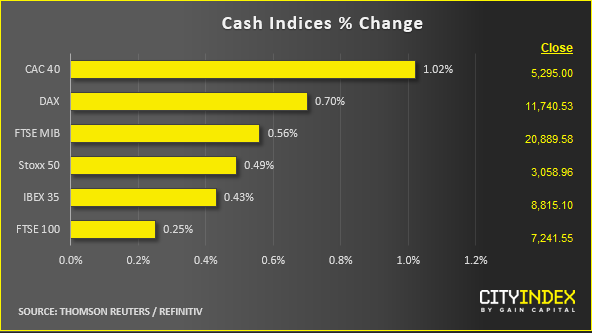
- The ongoing US-China trade dispute remains the main focal point after the US government formally named China a “currency manipulator” after the close of Wall Street on Monday. This came after Beijing allowed the renminbi to fall below 7 against the dollar for the first time in more than a decade, apparently in retaliation to the imposition of fresh tariffs on Chinese goods arriving in the US that were announced last week. However, after an initial dip on the news, stock index futures managed to rebound and were up noticeably at the time of writing. The People’s Bank of China set the daily currency fixing stronger than expected overnight, presumably to distance itself from the accusation it manipulates the yuan.
- Also supporting the markets is probably bargain hunting of companies with good fundamentals and short-covering elsewhere. BUT we think too much technical damage may have already incurred to suggest the bulls are still in control after a multi-month rally sent US indices to virgin territories and markets elsewhere to elevated levels, before the plunge that started last week.
- Meanwhile there was good news from Germany for a change following an onslaught of negative news. Here, factory orders unexpectedly jumped 2.5% in June. This was well above the 0.5% increase expected and more than made up May’s 2% decline. Still, given the sheer amount of data disappointment from Germany, a recession could be looming anyway for the Eurozone’s largest economy. More German data is on the way tomorrow, this time industrial production.
- Overnight, the Reserve Bank of Australia (RBA) decided to leave monetary policy unchanged, disappointing some expectations for a hat-trick of 25 basis-point rate cuts. However, the RBA left the door open for further rate cuts: “It is reasonable to expect that an extended period of low interest rates will be required in Australia to make progress in reducing unemployment and achieve more assured progress towards the inflation target. The Board will continue to monitor developments in the labour market closely and ease monetary policy further if needed to support sustainable growth in the economy and the achievement of the inflation target over time.”
- The AUD is the strongest on RBA inaction and risk rebound, with safe-haven Japanese yen being the weakest after its sharp rally in recent days. EUR has not found much support from strong German data
- The ongoing US-China trade dispute remains the main focal point after the US government formally named China a “currency manipulator” after the close of Wall Street on Monday. This came after Beijing allowed the renminbi to fall below 7 against the dollar for the first time in more than a decade, apparently in retaliation to the imposition of fresh tariffs on Chinese goods arriving in the US that were announced last week. However, after an initial dip on the news, stock index futures managed to rebound and were up noticeably at the time of writing. The People’s Bank of China set the daily currency fixing stronger than expected overnight, presumably to distance itself from the accusation it manipulates the yuan.
- Also supporting the markets is probably bargain hunting of companies with good fundamentals and short-covering elsewhere. BUT we think too much technical damage may have already incurred to suggest the bulls are still in control after a multi-month rally sent US indices to virgin territories and markets elsewhere to elevated levels, before the plunge that started last week.
- Meanwhile there was good news from Germany for a change following an onslaught of negative news. This was well above the 0.5% increase expected and more than made up May’s 2% decline. Still, given the sheer amount of data disappointment from Germany, a recession could be looming anyway for the Eurozone’s largest economy. More German data is on the way tomorrow, this time industrial production.
- Overnight, the Reserve Bank of Australia (RBA) decided to leave monetary policy unchanged, disappointing some expectations for a hat-trick of 25 basis-point rate cuts. However, the RBA left the door open for further rate cuts: “It is reasonable to expect that an extended period of low interest rates will be required in Australia to make progress in reducing unemployment and achieve more assured progress towards the inflation target. The Board will continue to monitor developments in the labour market closely and ease monetary policy further if needed to support sustainable growth in the economy and the achievement of the inflation target over time.”
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.


USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.