




Market Brief Solid NFP Erases Indices EarlyWeek Losses
See a summary of the top market themes and trends from today's US trading session!
Share this:

View our guide on how to interpret the FX Dashboard.
*Please note that the Pre-Asia Market Brief report will be on hiatus next week, returning Monday December, 16.*
- OPEC formalized a 500k bpd production cut, with additional voluntary cuts from Saudi Arabia.
- US data: Non-Farm Payrolls (Nov) printed at 266k, well above expectations of a 180k rise. Previous reports were also revised up by 41k. Average Hourly Earnings rose just 0.2% m/m (3.1% y/y), keeping a lid on the ensuing US dollar strength. Separately, the UofM Consumer Sentiment report improved to 99.2, above estimates of a 97.0 reading.
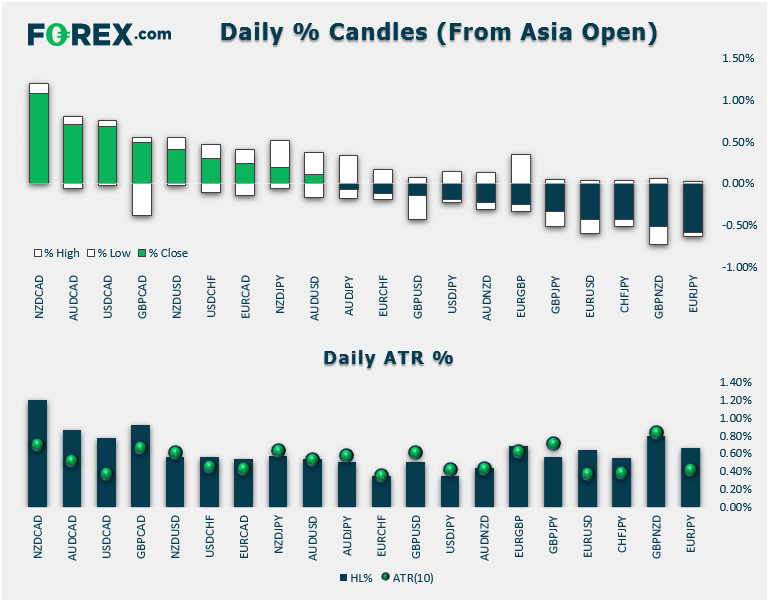
- FX: The New Zealand dollar was the strongest major currency on the day, while the Canadian dollar brought up the rear. An abysmal Canadian jobs report (-71.2k jobs, unemployment up 4 ticks to 5.9%) was the main culprit.
- Commodities: Oil gained over 1% on confirmation of the OPEC production cuts; gold slipped more than -1% on the back of the solid NFP report.

- US indices closed sharply higher to erase the losses from earlier in the week and close near record highs once again.
- Energy (XLE) and Financials (XLF) were the strongest sectors on the day. Utilities brought up the rear, closing lower on the day.
- Stocks on the move:
- Financial stocks, including Bank of America (BAC, +1%), Citigroup (C, +1%), and J.P. Morgan (JPM, +2%), rallied across the board on rising bond yields.
- Oil stocks also rose, helped along the OPEC production cut. Both Chevron (CVX) and Exxon Mobile (XOM) rose 1-2%.
- Manufacturing firm 3M (MMM) gained 4% after report that it was exploring selling off its drug delivery business.
- Uber Technologies (UBER) shed -3% on news that it received 16% more sexual assault reports this year than last. The company has long struggled with concerns about its culture.
View our guide on how to interpret the FX Dashboard.
*Please note that the Pre-Asia Market Brief report will be on hiatus next week, returning Monday December, 16.*
- OPEC formalized a 500k bpd production cut, with additional voluntary cuts from Saudi Arabia.
- US data: Non-Farm Payrolls (Nov) printed at 266k, well above expectations of a 180k rise. Previous reports were also revised up by 41k. Average Hourly Earnings rose just 0.2% m/m (3.1% y/y), keeping a lid on the ensuing US dollar strength. Separately, the UofM Consumer Sentiment report improved to 99.2, above estimates of a 97.0 reading.
- FX: The New Zealand dollar was the strongest major currency on the day, while the Canadian dollar brought up the rear. An abysmal Canadian jobs report (-71.2k jobs, unemployment up 4 ticks to 5.9%) was the main culprit.
- Commodities: Oil gained over 1% on confirmation of the OPEC production cuts; gold slipped more than -1% on the back of the solid NFP report.

- US indices closed sharply higher to erase the losses from earlier in the week and close near record highs once again.
- Energy (XLE) and Financials (XLF) were the strongest sectors on the day. Utilities brought up the rear, closing lower on the day.
- Stocks on the move:
- Financial stocks, including Bank of America (BAC, +1%), Citigroup (C, +1%), and J.P. Morgan (JPM, +2%), rallied across the board on rising bond yields.
- Oil stocks also rose, helped along the OPEC production cut. Both Chevron (CVX) and Exxon Mobile (XOM) rose 1-2%.
- Manufacturing firm 3M (MMM) gained 4% after report that it was exploring selling off its drug delivery business.
- Uber Technologies (UBER) shed -3% on news that it received 16% more sexual assault reports this year than last. The company has long struggled with concerns about its culture.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.