




NFP will not be a Game Changer for the Fed
The headline NFP Payroll number should not sway the Fed in their decision.
Share this:

The headline NFP number for September was marginally weaker at 136K vs the 145K expectation. However, with the revision to August’s number from 130K to 168K, the overall headline number will be looked at as slightly better than expected. The headline NFP Payroll number itself should not sway the Fed in their decision to cut rates on October 30th. The unemployment number dropped to 3.5% in September from 3.7% in August.
However, the Average Hourly Earnings (MoM) dropped from 0.4% in August 0.0% in September, vs an expectation on 0.3%. This is a huge miss and will heighten the Fed’s awareness to a slowdown in inflation over the month. The FOMC meets again on October 30th. In theory, lower inflation would lead to a lower US Dollar, which would lead to more rate cuts.
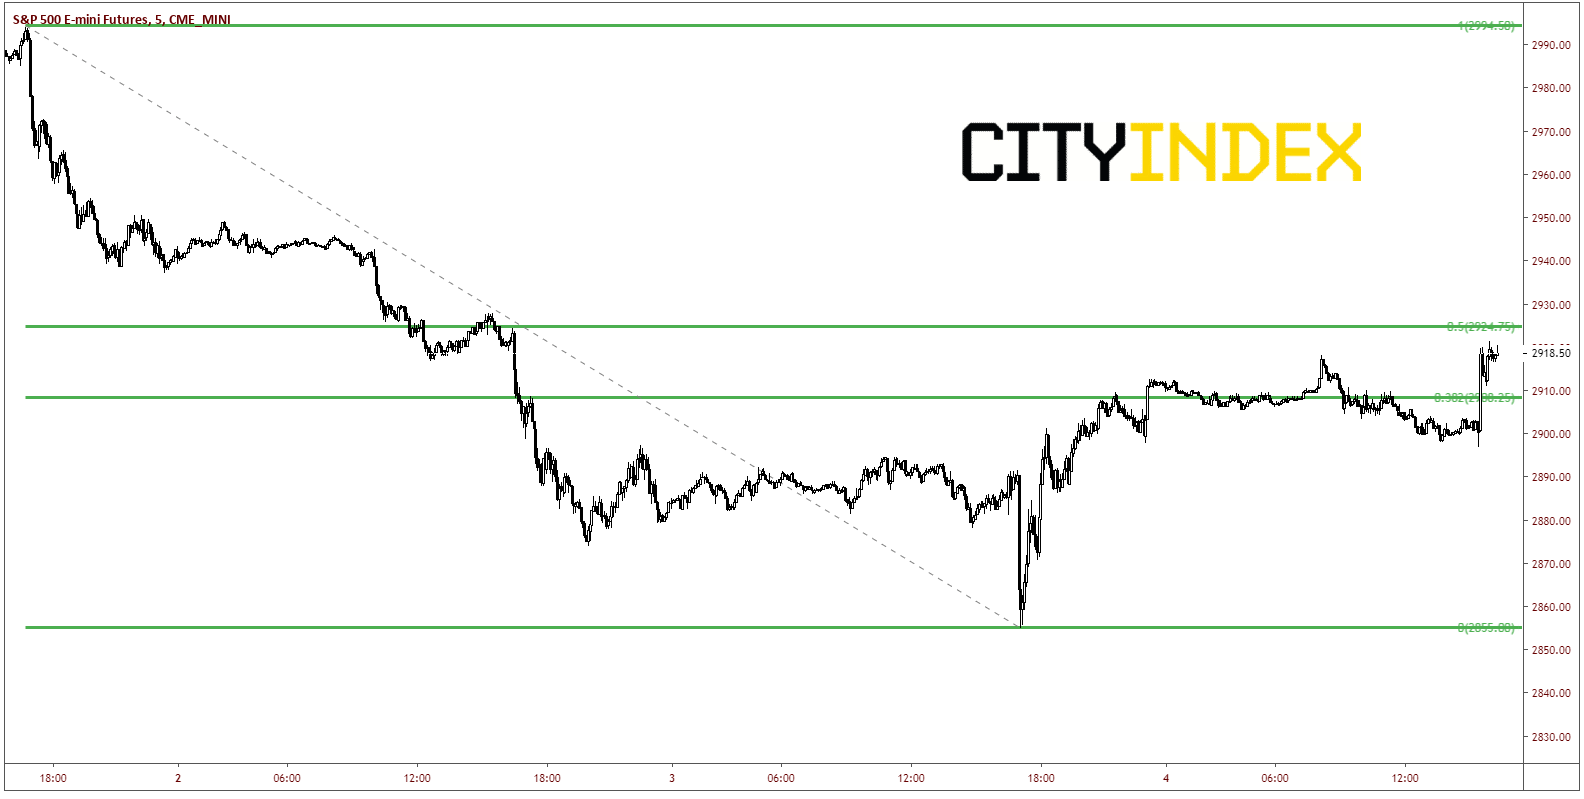
Immediately after the release of the data S&Ps spiked higher, mostly likely a “relief rally” from 2900 to near 2020. Given all the poor data released this week, the market is content to have a number that is inline/slightly better. S&PS are closing in on the 50% retracement at 2925 from the Oct 2nd high to yesterday’s lows. Support is at today’s lows of 2896.75. Next support is yesterday’s lows at 2855.
Source: Tradingview, City Index, CME
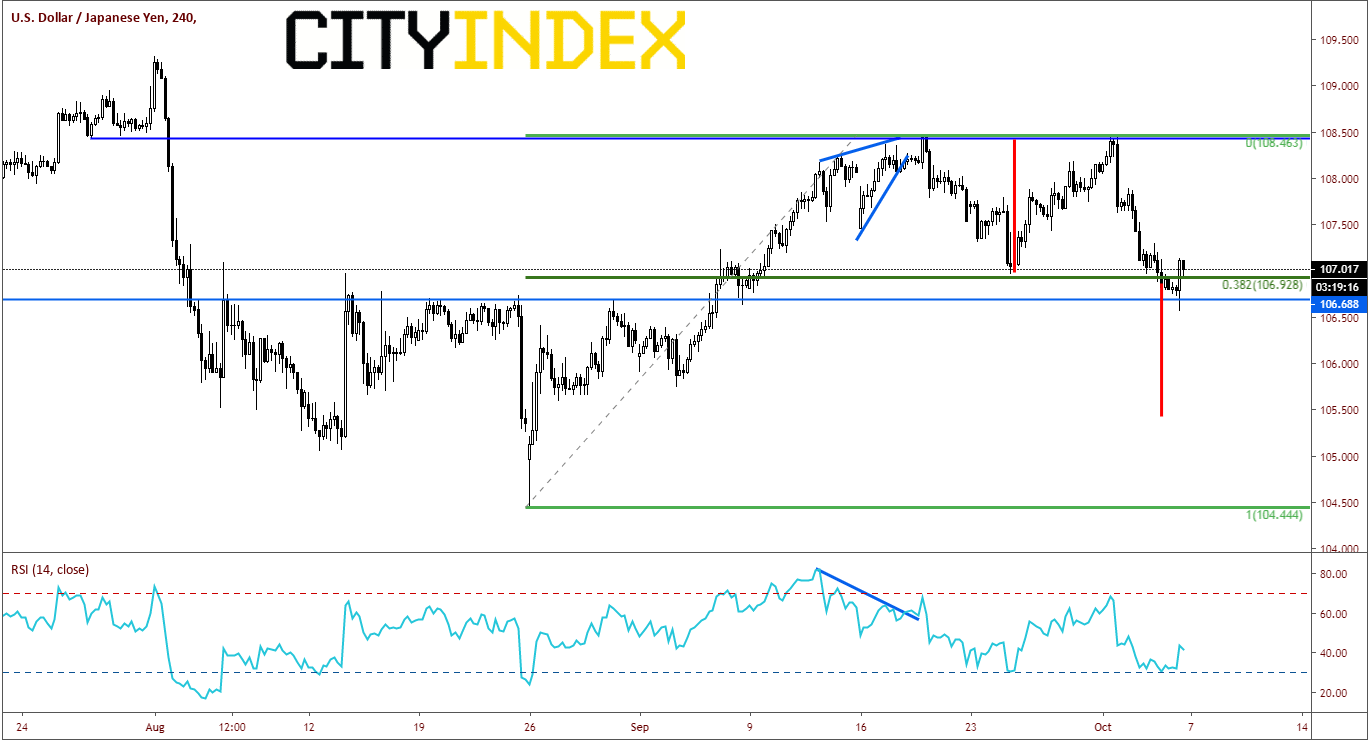
USD/JPY also spiked after the data release, possibly also on a relief rally. However, on a 240-minute chart, one can see that a double top has been formed, with the neckline broken near 107.05. This breakdown has failed for the moment, as horizontal support was held at 106.68. However, a break below this level may confirm the next move lower. To find the target for a double top, take the distance of the high to low between the 2 highs, and add it to the breakdown point. The target in this case is near 105.45
Source: Tradingview, City Index
The headline NFP number for September was marginally weaker at 136K vs the 145K expectation. However, with the revision to August’s number from 130K to 168K, the overall headline number will be looked at as slightly better than expected. The headline NFP Payroll number itself should not sway the Fed in their decision to cut rates on October 30th. The unemployment number dropped to 3.5% in September from 3.7% in August.
However, the Average Hourly Earnings (MoM) dropped from 0.4% in August 0.0% in September, vs an expectation on 0.3%. This is a huge miss and will heighten the Fed’s awareness to a slowdown in inflation over the month. The FOMC meets again on October 30th. In theory, lower inflation would lead to a lower US Dollar, which would lead to more rate cuts.
Immediately after the release of the data S&Ps spiked higher, mostly likely a “relief rally” from 2900 to near 2020. Given all the poor data released this week, the market is content to have a number that is inline/slightly better. S&PS are closing in on the 50% retracement at 2925 from the Oct 2nd high to yesterday’s lows. Support is at today’s lows of 2896.75. Next support is yesterday’s lows at 2855.
Source: Tradingview, FOREX.com, CME
USD/JPY also spiked after the data release, possibly also on a relief rally. However, on a 240-minute chart, one can see that a double top has been formed, with the neckline broken near 107.05. This breakdown has failed for the moment, as horizontal support was held at 106.68. However, a break below this level may confirm the next move lower. To find the target for a double top, take the distance of the high to low between the 2 highs, and add it to the breakdown point. The target in this case is near 105.45
Source: Tradingview, FOREX.com
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.


GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.