




Risk Rally Pauses For Breath ECB in Focus
Share this:
Wall Street ended in the green, with the Nasdaq briefly touching levels last seen pre-coronavirus, in February and just short of its all-time high. The optimism spilled into Asia overnight, where fresh two month highs were reached. However, risk tone is struggling for direction heading into the European open, as investors await the ECB monetary policy meeting.
Gradual easing of lockdown measures and optimism surrounding the reopening of economies, combined with government and central bank stimulus has seen risk appetite soar. Stocks continue to trade at levels which appear at odds with the data which is coming through.
The S&P is trading just 3% down this year and the Dax 5%. These figures seem almost unbelievable given the horrendous data which is revealing the extent of the damage that the coronavirus crisis has inflicted on economies across the globe. It almost seems absurd that US stock indices can be trading at these levels whilst the unemployment running close to levels last seen the great depression of the 1930’s
Worst behind us & low expectations beaten
However, a good portion of this data is beating forecasts. Just yesterday, service sector PMI data across Europe, UK and the US beat expectations, even though activity remains deep in contraction. US ADP data showed that only 2 million US private sector jobs were lost, well down from the 9 million forecast and 25 million from April. A classic example of if you set the bar low enough anything is a positive.
However, a good portion of this data is beating forecasts. Just yesterday, service sector PMI data across Europe, UK and the US beat expectations, even though activity remains deep in contraction. US ADP data showed that only 2 million US private sector jobs were lost, well down from the 9 million forecast and 25 million from April. A classic example of if you set the bar low enough anything is a positive.
There is a clear sense that the worst is in the rear-view mirror. Combine this optimism with government and central bank stimulus, and the expectation that more stimulus is coming the rally is more comprehensible.
German stimulus, Dax soars
Angela Merkel didn’t disappoint yesterday, announcing an additional €130 billion stimulus package to help Germany recover from the coronavirus crisis, adding to an initial shot of stimulus in March. The announcement came as the unemployment rate hit its highest level since late 2015.
Angela Merkel didn’t disappoint yesterday, announcing an additional €130 billion stimulus package to help Germany recover from the coronavirus crisis, adding to an initial shot of stimulus in March. The announcement came as the unemployment rate hit its highest level since late 2015.
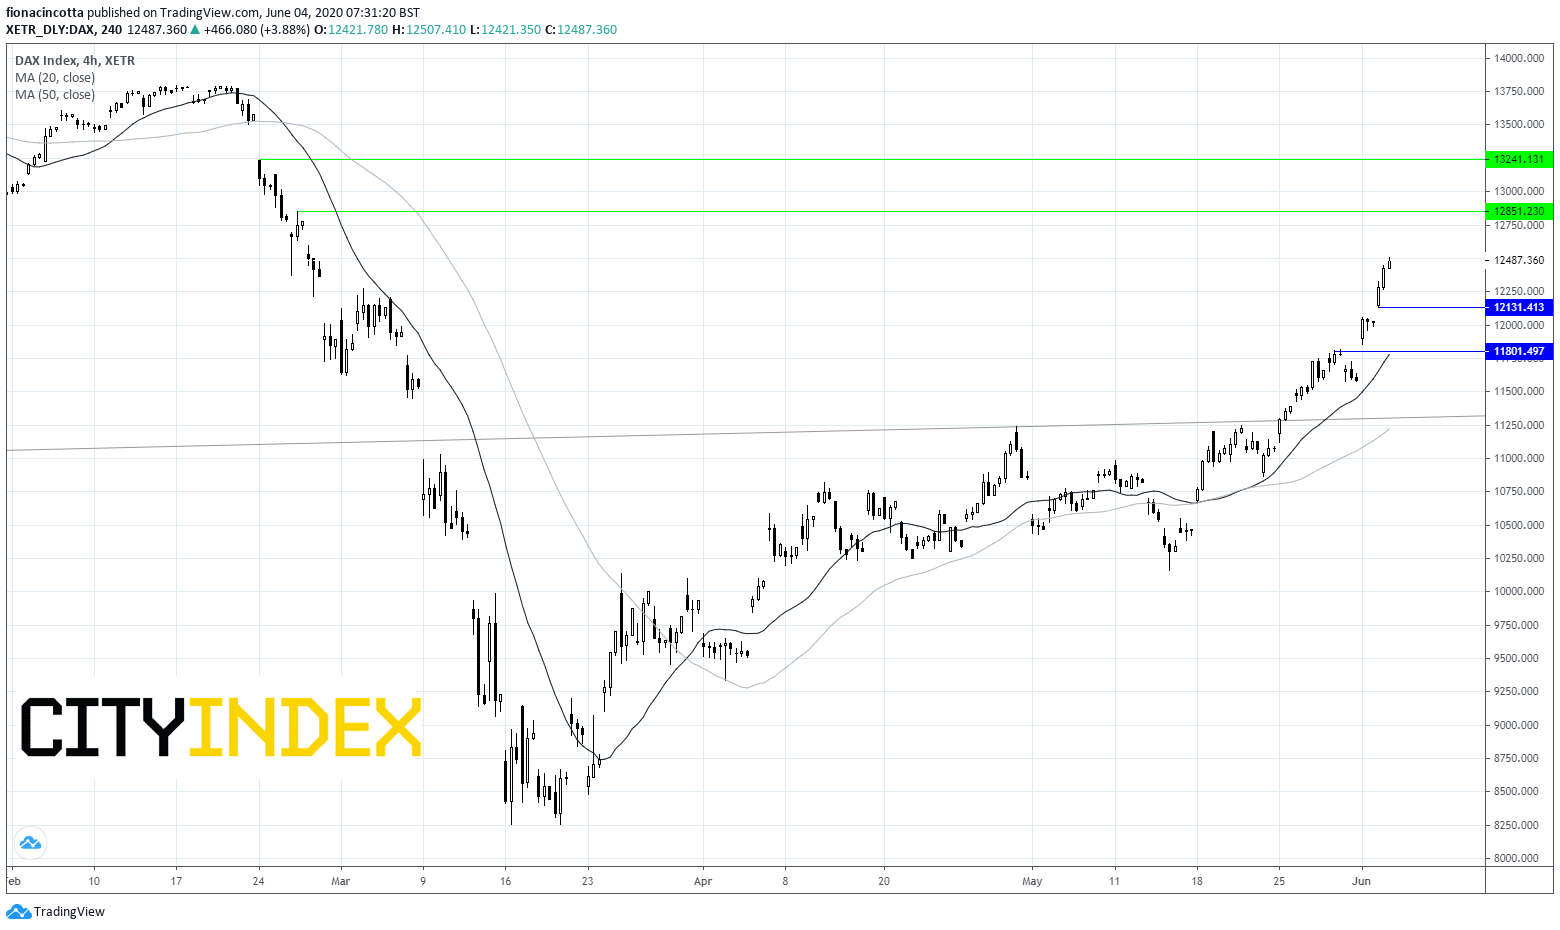
The Dax rallied 3.8% in the previous session, gaining just shy of 7% so far in June. The index is down just 5% so far this year, highlighting the under performance of the FTSE, which still trades some 15% off its levels at the start of the year.
ECB to expand PEPP
Attention will now turn to the ECB, which is expected to keep rates on hold. However, there is a growing expectation that the central bank will expand their bond purchasing programme, the Pandemic Emergency Purchase Programme.
The €750 billion programme, aimed to support those nations hardest hit by the coronavirus crisis, is set to run out in October. Expectations are for the programme to be expanded by €250 billion - €500 billion and the timeline pushed out beyond October. However, with expectations riding so high, the biggest risk here is that the ECB do nothing and wait further data.
ECB staff projections will also be closely watched and are expected to make for pretty grim reading. GDP contraction in the region of 8-12% is expected.
Dax levels to watch:
The Dax trades above its 100, 50 & 20 sma on 4 hour chart, a strongly bullish chart. The index also trades above its long term trend line dating back to October 2011.
Immediate resistance can be seen at 12850 (high 26th Feb) prior to 13240 (high 24th Feb).
Support can be seen at 12133 (low 2nd June) prior to 11810 (high 28th May).
Wall Street ended in the green, with the Nasdaq briefly touching levels last seen pre-coronavirus, in February and just short of its all-time high. The optimism spilled into Asia overnight, where fresh two month highs were reached. However, risk tone is struggling for direction heading into the European open, as investors await the ECB monetary policy meeting.
Gradual easing of lockdown measures and optimism surrounding the reopening of economies, combined with government and central bank stimulus has seen risk appetite soar. Stocks continue to trade at levels which appear at odds with the data which is coming through.
The S&P is trading just 3% down this year and the Dax 5%. These figures seem almost unbelievable given the horrendous data which is revealing the extent of the damage that the coronavirus crisis has inflicted on economies across the globe. It almost seems absurd that US stock indices can be trading at these levels whilst the unemployment running close to levels last seen the great depression of the 1930’s
Worst behind us & low expectations beaten
However, a good portion of this data is beating forecasts. Just yesterday, service sector PMI data across Europe, UK and the US beat expectations, even though activity remains deep in contraction. US ADP data showed that only 2 million US private sector jobs were lost, well down from the 9 million forecast and 25 million from April. A classic example of if you set the bar low enough anything is a positive.
However, a good portion of this data is beating forecasts. Just yesterday, service sector PMI data across Europe, UK and the US beat expectations, even though activity remains deep in contraction. US ADP data showed that only 2 million US private sector jobs were lost, well down from the 9 million forecast and 25 million from April. A classic example of if you set the bar low enough anything is a positive.
There is a clear sense that the worst is in the rear-view mirror. Combine this optimism with government and central bank stimulus, and the expectation that more stimulus is coming the rally is more comprehensible.
German stimulus, Dax soars
Angela Merkel didn’t disappoint yesterday, announcing an additional €130 billion stimulus package to help Germany recover from the coronavirus crisis, adding to an initial shot of stimulus in March. The announcement came as the unemployment rate hit its highest level since late 2015.
Angela Merkel didn’t disappoint yesterday, announcing an additional €130 billion stimulus package to help Germany recover from the coronavirus crisis, adding to an initial shot of stimulus in March. The announcement came as the unemployment rate hit its highest level since late 2015.
The Dax rallied 3.8% in the previous session, gaining just shy of 7% so far in June. The index is down just 5% so far this year, highlighting the under performance of the FTSE, which still trades some 15% off its levels at the start of the year.
ECB to expand PEPP
Attention will now turn to the ECB, which is expected to keep rates on hold. However, there is a growing expectation that the central bank will expand their bond purchasing programme, the Pandemic Emergency Purchase Programme.
The €750 billion programme, aimed to support those nations hardest hit by the coronavirus crisis, is set to run out in October. Expectations are for the programme to be expanded by €250 billion - €500 billion and the timeline pushed out beyond October. However, with expectations riding so high, the biggest risk here is that the ECB do nothing and wait further data.
ECB staff projections will also be closely watched and are expected to make for pretty grim reading. GDP contraction in the region of 8-12% is expected.
Dax levels to watch:
The Dax trades above its 100, 50 & 20 sma on 4 hour chart, a strongly bullish chart. The index also trades above its long term trend line dating back to October 2011.
Immediate resistance can be seen at 12850 (high 26th Feb) prior to 13240 (high 24th Feb).
Support can be seen at 12133 (low 2nd June) prior to 11810 (high 28th May).
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.