




Sell in May and come back on St Legers Day
The old adage “Sell in May and come back on St Leger Day” isn’t looking like such bad advice so far.
Share this:
The old adage “Sell in May and come back on St Leger Day” isn’t looking like such bad advice so far. After a steep sell off in stocks on Friday, renewed tensions between US and China is dragging on risk sentiment again at the start of the week, dragging on stocks and boosting safe haven flows. Oil prices are once again tumbling on trade war fears and rapidly filling storage. With a shortage of data releases risk sentiment will be a key driving factor across today’s session.
US – China trade wars fears resurface
Stock are pointing to a lower start amid fresh efforts from the Trump administration to pin blame for the coronavirus pandemic on China and linking the outbreak to a laboratory in Wuhan. Tariff threats continue to loom fueling fears over another chapter to the US – China trade war
Trump’s threats of a trade tariffs and his growing desire to pull supply chains from China is fueling fears that the trade deal, signed just that the beginning of this year could be under threat. Trump’s motivation has never been greater. The devastating impact of the virus on American lives and the economy could cost him the US election. Trump’s big chance at keeping election hopes alive is through uniting the American people against a common enemy, China.
Another round to the US China trade war is the last thing that global economies will be able to cope given their fragility as economies start to ease lock down measures and gradually restart and the markets are clear on that. Stock across Asia dropped lower overnight and European and US Futures are pointing to a negative start as trade war fears overshadow optimism surrounding the gradual reopening of economies and easing of lock down measures.
Oil Drops 7%
After a weekly gain of 16.7% last week, oil is once again under pressure. WTI is trading down over 7%, through $18.50 pb, hit by the prospect of a trade war strangling the global economy, supressing oil demand further, in addition to persistent concerns about over supply and inadequate storage. Economies are starting to reopen, however this is happening at a very gradual pace. Demand for oil is not expected to pick up sharply any time soon. In the meantime, with too much oil glugging round the system pressure will keep prices below $20 for the time being.
After a weekly gain of 16.7% last week, oil is once again under pressure. WTI is trading down over 7%, through $18.50 pb, hit by the prospect of a trade war strangling the global economy, supressing oil demand further, in addition to persistent concerns about over supply and inadequate storage. Economies are starting to reopen, however this is happening at a very gradual pace. Demand for oil is not expected to pick up sharply any time soon. In the meantime, with too much oil glugging round the system pressure will keep prices below $20 for the time being.
Eurozone PMI
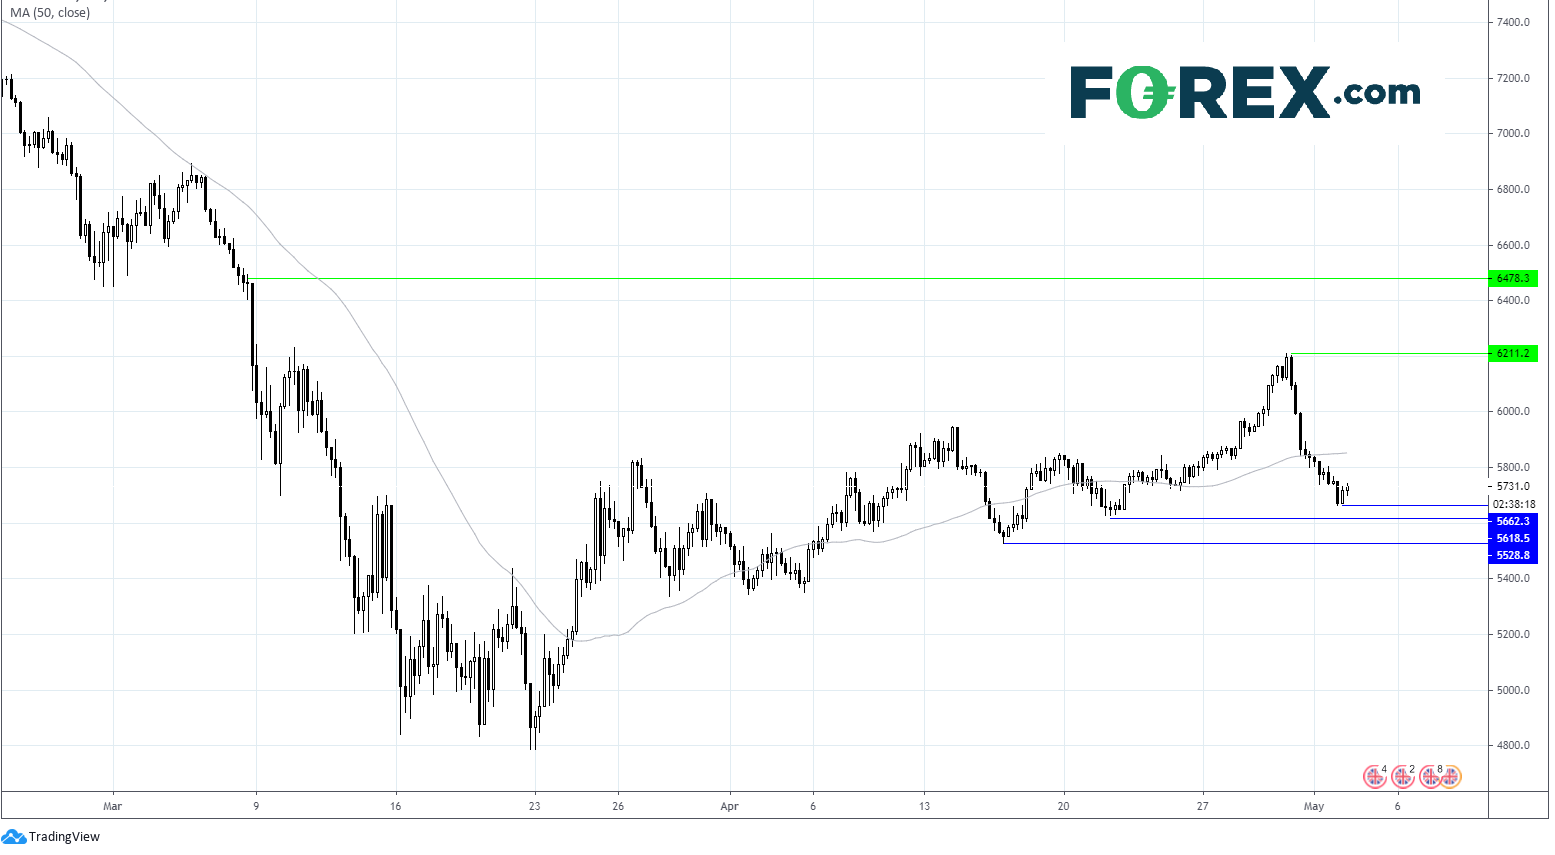
In Europe attention will shift towards manufacturing PMI readings. So far, the manufacturing sector has held up better that the service sector, experiencing less of a covid-19. However, expectations are still weak, particularly given that most countries were in lockdown for the full month of April. Eurozone manufacturing pmi is expected at 33.6 in April, down from 44.1 in March, whilst Germany at 34.4 down from 45.4 in April. EUR/USD is already moving lower in risk off trading, weak PMI readings could drag the common currency towards $1.09.
The old adage “Sell in May and come back on St Leger Day” isn’t looking like such bad advice so far. After a steep sell off in stocks on Friday, renewed tensions between US and China is dragging on risk sentiment again at the start of the week, dragging on stocks and boosting safe haven flows. Oil prices are once again tumbling on trade war fears and rapidly filling storage. With a shortage of data releases risk sentiment will be a key driving factor across today’s session.
US – China trade wars fears resurface
Stock are pointing to a lower start amid fresh efforts from the Trump administration to pin blame for the coronavirus pandemic on China and linking the outbreak to a laboratory in Wuhan. Tariff threats continue to loom fueling fears over another chapter to the US – China trade war
Trump’s threats of a trade tariffs and his growing desire to pull supply chains from China is fueling fears that the trade deal, signed just that the beginning of this year could be under threat. Trump’s motivation has never been greater. The devastating impact of the virus on American lives and the economy could cost him the US election. Trump’s big chance at keeping election hopes alive is through uniting the American people against a common enemy, China.
Another round to the US China trade war is the last thing that global economies will be able to cope given their fragility as economies start to ease lock down measures and gradually restart and the markets are clear on that. Stock across Asia dropped lower overnight and European and US Futures are pointing to a negative start as trade war fears overshadow optimism surrounding the gradual reopening of economies and easing of lock down measures.
Oil Drops 7%
After a weekly gain of 16.7% last week, oil is once again under pressure. WTI is trading down over 7%, through $18.50 pb, hit by the prospect of a trade war strangling the global economy, supressing oil demand further, in addition to persistent concerns about over supply and inadequate storage. Economies are starting to reopen, however this is happening at a very gradual pace. Demand for oil is not expected to pick up sharply any time soon. In the meantime, with too much oil glugging round the system pressure will keep prices below $20 for the time being.
After a weekly gain of 16.7% last week, oil is once again under pressure. WTI is trading down over 7%, through $18.50 pb, hit by the prospect of a trade war strangling the global economy, supressing oil demand further, in addition to persistent concerns about over supply and inadequate storage. Economies are starting to reopen, however this is happening at a very gradual pace. Demand for oil is not expected to pick up sharply any time soon. In the meantime, with too much oil glugging round the system pressure will keep prices below $20 for the time being.
Eurozone PMI
In Europe attention will shift towards manufacturing PMI readings. So far, the manufacturing sector has held up better that the service sector, experiencing less of a covid-19. However, expectations are still weak, particularly given that most countries were in lockdown for the full month of April. Eurozone manufacturing pmi is expected at 33.6 in April, down from 44.1 in March, whilst Germany at 34.4 down from 45.4 in April. EUR/USD is already moving lower in risk off trading, weak PMI readings could drag the common currency towards $1.09.
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.