




S&P 500 analysis: Risk off remains dominant theme
It was “risk off” again first thing this morning as Europe’s leading indices fell along with US index futures following Wednesday’s selling. Though the indices bounced off their lows by mid-day London, it remained to be seen whether the markets will be able to regain their poise meaningfully. Recent recovery attempts have all been futile. This could be another one.
Share this:
- S&P 500 analysis: Stocks could drop further as US 10y bond yields close in on 5%
- Sentiment remains bearish as geopolitical unrest amplifies market uncertainty
- Lighter economic calendar but plenty of FedSpeak today
It was “risk off” again first thing this morning as Europe’s leading indices fell along with US index futures following Wednesday’s selling. Though the indices bounced off their lows by mid-day London, it remained to be seen whether the markets will be able to regain their poise meaningfully. Recent recovery attempts have all been futile. This could be another one.
Sentiment remains downbeat
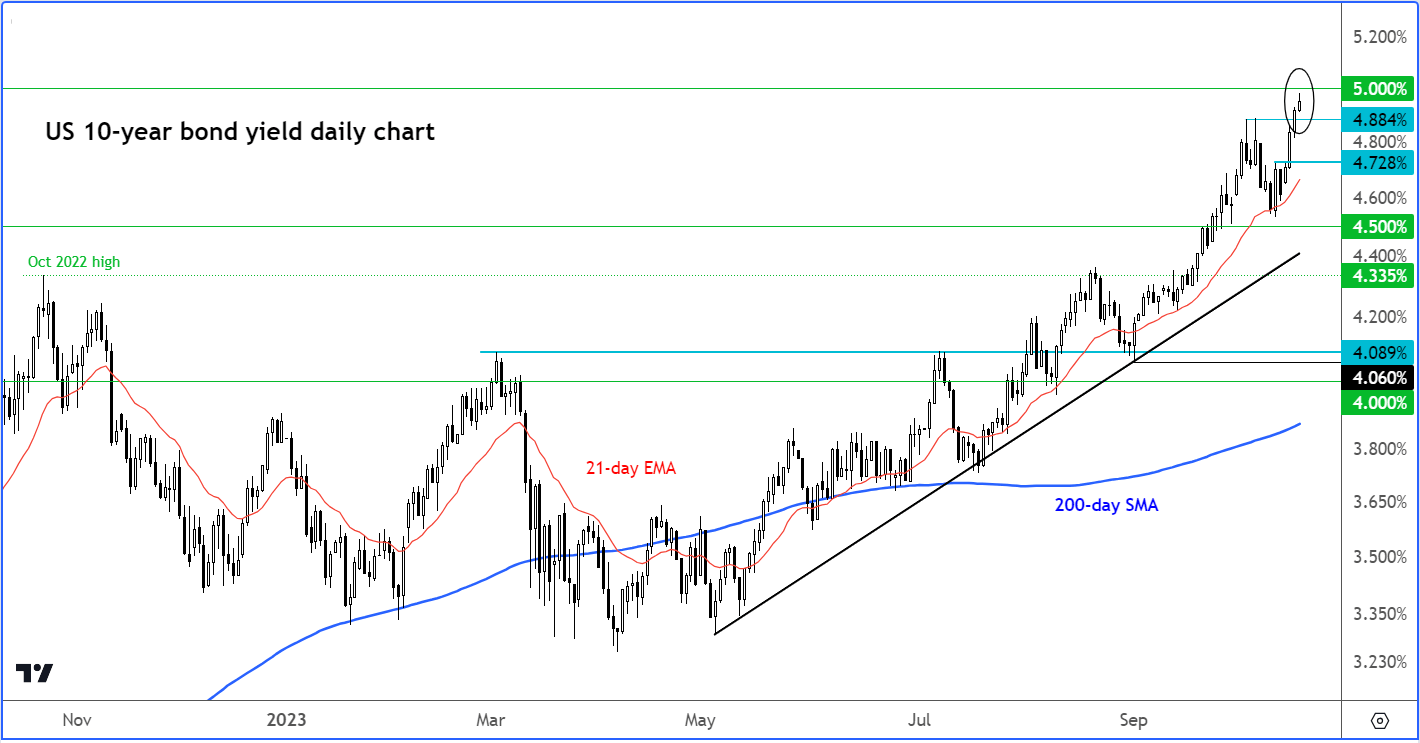
The current risk appetite remains conservative at best, due to the prevailing economic uncertainties and heightened geopolitical risks emitting from the Middle East. With interest rates at their highest levels since the financial crisis and the lingering uncertainty regarding inflation, investors are pondering the future economic landscape. While signs indicate a peak in inflation and the likelihood of looser monetary policies in 2024, the duration of elevated inflation remains uncertain, casting doubt on the longevity of high interest rates. Consequently, investors appear happy to keep selling government bonds, driving their yields higher. Additionally, the recent Middle East crisis has further fuelled concerns, pressurizing risk assets.
S&P 500 analysis: Stocks could drop further as US 10y bond yields close in on 5 pc
Today we saw a fresh peak in US 10-year yields for 2023, edging ever closer to that critical 5.00% mark that everyone is watching. The renewed rise in yields was responsible for the drop in Wall Street shares on Wednesday. The surge in US 10-year Treasury yields, perhaps a delayed reaction from robust US retail sales data earlier, has taken the forefront in global financial markets. For as long as yields remain elevated, this should keep risk appetite low.
Lighter economic calendar but plenty of FedSpeak
Today’s notable events on the economic calendar include several Federal Reserve speakers, particularly Fed Chair Jay Powell at 17:00 BST. The Fed has kept the door for a final rate hike open, but in light of the recent upsurge in bond yields, Powell may try and ease market concerns by indicating that rates are already at a peak.
We will also have some second-tier data to look forward to, including the release of the weekly jobless claims and Philly Fed manufacturing index, both at 13:30 BST, and existing home sales and CB leading index at 15:00 BST. Recent economic pointers from the US have been decent, and the ongoing absence of lay-offs in the jobless claims data continues to be a surprise element in the US data performance. Let’s see if jobless claims will start to rise as the economy slows down.
Geopolitical unrest amplifies market uncertainty
Although the stock market attempted a recovery this morning, the absence of positive fundamental factors to significantly alter investors' risk appetite suggests the possibility of sustained market pressure. In Europe, the DAX and FTSE look quite vulnerable and recent price action point to further potential losses.
It is also worth watching the currency markets for further volatility, especially risk-sensitive commodity dollars, like the NZD. Recent FX correlations with the stock markets suggest that a sell-off could lead to the dollar maintaining gains at the expense of commodity currencies. Despite the Australian dollar being undervalued from a macro perspective, it might face substantial impact as a high-beta victim during an equity sell-off, possibly dragging down cross rates like AUD/JPY. It is also worth pointing out that GBP/USD has shown a notably strong positive correlation with the S&P 500, compared to the EUR/USD.
Focus Turns to US Tech Earnings
The US earnings calendar is getting busier. With banks now out of the way, the focus is slowly going to turn to technology stocks. We have already heard from Tesla and Netflix. Next week, we have the following companies reporting their results:
- Microsoft, Tuesday October 24
- Alphabet, Tuesday October 24
- Meta, Wednesday October 25
- Amazon, Thursday October 26
- Apple, Thursday November 2
Earnings from these big tech giants are expected to grow which explains why the Nasdaq has outperformed some of the other major indices. Tech giants are expected to deliver better profits thanks to cost-cutting, resilient growth and AI prospects. However, the bar is set high, and it wouldn’t take much to disappoint expectations. Equally important will be what these companies will say about future growth. The market is always forward-looking. If they forecast a slowdown in earnings for future quarters, then this could see tech shares struggle to stay afloat.
HERE is our full tech earnings preview by my colleague Joshua Warner.
HERE is our full tech earnings preview by my colleague Joshua Warner.
S&P 500 technical analysis
The S&P 500 closed back below the August low of 4335, thereby invalidating the recent bullish structure that had been created above this level and around the 21-day exponential moving average. With the index now back below the 21-day, we could see an accelerated sell-off, especially if accompanied by bond yields breaking the 5.0% level. The next downside target is the 200-day average at around 4245. Below this, we have the recent support area around 4200 to keep an eye on. On the upside, that 4335 remains the most important short-term resistance to watch. But even if we go back above that level, this won’t necessarily be the end of the bearish trend. At some stage, the S&P will need to form a higher high to suggest the bearish trend that started in July, is over. Until we see such a signal, the bulls should proceed with extra care, as the selling could easily gather momentum.
Source for all charts used in this article: TradingView.com
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.