




Tech Warnings and Trump Threats Hit Sentiment
Sobering comments from tech giants Apple and Amazon in addition to fears of a new chapter to the US China trade war are weighing on sentiment
Share this:

European stocks are taking the lead from Wall Street and Asia, pointing to a sharply lower start on the open. Sobering comments from tech giants Apple and Amazon in addition to fears of a new chapter to the US China trade war are weighing on sentiment at the end of the trading week and the start of the new month, pulling equities lower and boosting the safe haven dollar.
Despite the sell off yesterday, global stocks posted their best month since 2011 in April thanks to a slowdown in coronavirus infections, optimism surrounding the gradual reopening of economies and massive stimulus initiatives. However, data and earnings are serving as a reminder that the economic pain is really only just beginning.
Sobering comments
Apple refrained from issuing guidance for the first time in more than a decade amid growing uncertainty and poor visibility. Meanwhile Amazon reported revenue growth but also higher expenses protecting its workers and customers. Amazon warned of losses in the coming quarter. Strong results for Microsoft, Facebook and Tesla limited losses of the tech heavy Nasdaq.
Apple refrained from issuing guidance for the first time in more than a decade amid growing uncertainty and poor visibility. Meanwhile Amazon reported revenue growth but also higher expenses protecting its workers and customers. Amazon warned of losses in the coming quarter. Strong results for Microsoft, Facebook and Tesla limited losses of the tech heavy Nasdaq.
Trade war chapter 2
Trump sharpening his rhetoric against China is unnerving investors, as his team look into retaliatory measures over the coronavirus outbreak. The China trade war seems like an eternity ago after coronavirus has dominated market movements with such intensity over recent weeks. However, threats of more tariffs from Trump have hit a nerve with the markets and is adding to the downbeat sentiment heading into the weekend.
Trump sharpening his rhetoric against China is unnerving investors, as his team look into retaliatory measures over the coronavirus outbreak. The China trade war seems like an eternity ago after coronavirus has dominated market movements with such intensity over recent weeks. However, threats of more tariffs from Trump have hit a nerve with the markets and is adding to the downbeat sentiment heading into the weekend.
UK manufacturing PMI
Following yesterday’s slew of disappointing figures from Europe today’s attention will turn to the UK economy with the final release of manufacturing PMI data, which is expected to come in at 32.8 in April. Whilst the manufacturing sector is holding up better than the service sector, it is still in a plain awful position. And things could get significantly worse with an industry body warning that British factory output was at risk of halving in the second quarter, as 80% of manufacturers reported a collapse in orders owing to the coronavirus outbreak.
Following yesterday’s slew of disappointing figures from Europe today’s attention will turn to the UK economy with the final release of manufacturing PMI data, which is expected to come in at 32.8 in April. Whilst the manufacturing sector is holding up better than the service sector, it is still in a plain awful position. And things could get significantly worse with an industry body warning that British factory output was at risk of halving in the second quarter, as 80% of manufacturers reported a collapse in orders owing to the coronavirus outbreak.
GBP is already trending lower in anticipation of dire data, despite Boris Johnson promising to announce the UK’s exit strategy from lock down next week.
US manufacturing
US ISM manufacturing PMI is expected to drop sharply in April after holding up near the 50 threshold in March. This forward looing survey will provide the first hint of what’s to come in next week’s non-farm payroll report.
US ISM manufacturing PMI is expected to drop sharply in April after holding up near the 50 threshold in March. This forward looing survey will provide the first hint of what’s to come in next week’s non-farm payroll report.
Quick word on oil
WTI is pushing higher for a third straight session, although the rally is running out of steam. After jumping 47% across the previous 2 sessions, WTI is trading just 1.8% higher on Friday, struggling to push through $20. Whilst economies across Europe and US states are gradually reopening and as the production cuts kick in today, the high levels of uncertainty are limiting gains.
FTSE chart
European stocks are taking the lead from Wall Street and Asia, pointing to a sharply lower start on the open. Sobering comments from tech giants Apple and Amazon in addition to fears of a new chapter to the US China trade war are weighing on sentiment at the end of the trading week and the start of the new month, pulling equities lower and boosting the safe haven dollar.
Despite the sell off yesterday, global stocks posted their best month since 2011 in April thanks to a slowdown in coronavirus infections, optimism surrounding the gradual reopening of economies and massive stimulus initiatives. However, data and earnings are serving as a reminder that the economic pain is really only just beginning.
Sobering comments
Apple refrained from issuing guidance for the first time in more than a decade amid growing uncertainty and poor visibility. Meanwhile Amazon reported revenue growth but also higher expenses protecting its workers and customers. Amazon warned of losses in the coming quarter. Strong results for Microsoft, Facebook and Tesla limited losses of the tech heavy Nasdaq.
Apple refrained from issuing guidance for the first time in more than a decade amid growing uncertainty and poor visibility. Meanwhile Amazon reported revenue growth but also higher expenses protecting its workers and customers. Amazon warned of losses in the coming quarter. Strong results for Microsoft, Facebook and Tesla limited losses of the tech heavy Nasdaq.
Trade war chapter 2
Trump sharpening his rhetoric against China is unnerving investors, as his team look into retaliatory measures over the coronavirus outbreak. The China trade war seems like an eternity ago after coronavirus has dominated market movements with such intensity over recent weeks. However, threats of more tariffs from Trump have hit a nerve with the markets and is adding to the downbeat sentiment heading into the weekend.
Trump sharpening his rhetoric against China is unnerving investors, as his team look into retaliatory measures over the coronavirus outbreak. The China trade war seems like an eternity ago after coronavirus has dominated market movements with such intensity over recent weeks. However, threats of more tariffs from Trump have hit a nerve with the markets and is adding to the downbeat sentiment heading into the weekend.
UK manufacturing PMI
Following yesterday’s slew of disappointing figures from Europe today’s attention will turn to the UK economy with the final release of manufacturing PMI data, which is expected to come in at 32.8 in April. Whilst the manufacturing sector is holding up better than the service sector, it is still in a plain awful position. And things could get significantly worse with an industry body warning that British factory output was at risk of halving in the second quarter, as 80% of manufacturers reported a collapse in orders owing to the coronavirus outbreak.
Following yesterday’s slew of disappointing figures from Europe today’s attention will turn to the UK economy with the final release of manufacturing PMI data, which is expected to come in at 32.8 in April. Whilst the manufacturing sector is holding up better than the service sector, it is still in a plain awful position. And things could get significantly worse with an industry body warning that British factory output was at risk of halving in the second quarter, as 80% of manufacturers reported a collapse in orders owing to the coronavirus outbreak.
GBP is already trending lower in anticipation of dire data, despite Boris Johnson promising to announce the UK’s exit strategy from lock down next week.
US manufacturing
US ISM manufacturing PMI is expected to drop sharply in April after holding up near the 50 threshold in March. This forward looing survey will provide the first hint of what’s to come in next week’s non-farm payroll report.
US ISM manufacturing PMI is expected to drop sharply in April after holding up near the 50 threshold in March. This forward looing survey will provide the first hint of what’s to come in next week’s non-farm payroll report.
Quick word on oil
WTI is pushing higher for a third straight session, although the rally is running out of steam. After jumping 47% across the previous 2 sessions, WTI is trading just 1.8% higher on Friday, struggling to push through $20. Whilst economies across Europe and US states are gradually reopening and as the production cuts kick in today, the high levels of uncertainty are limiting gains.
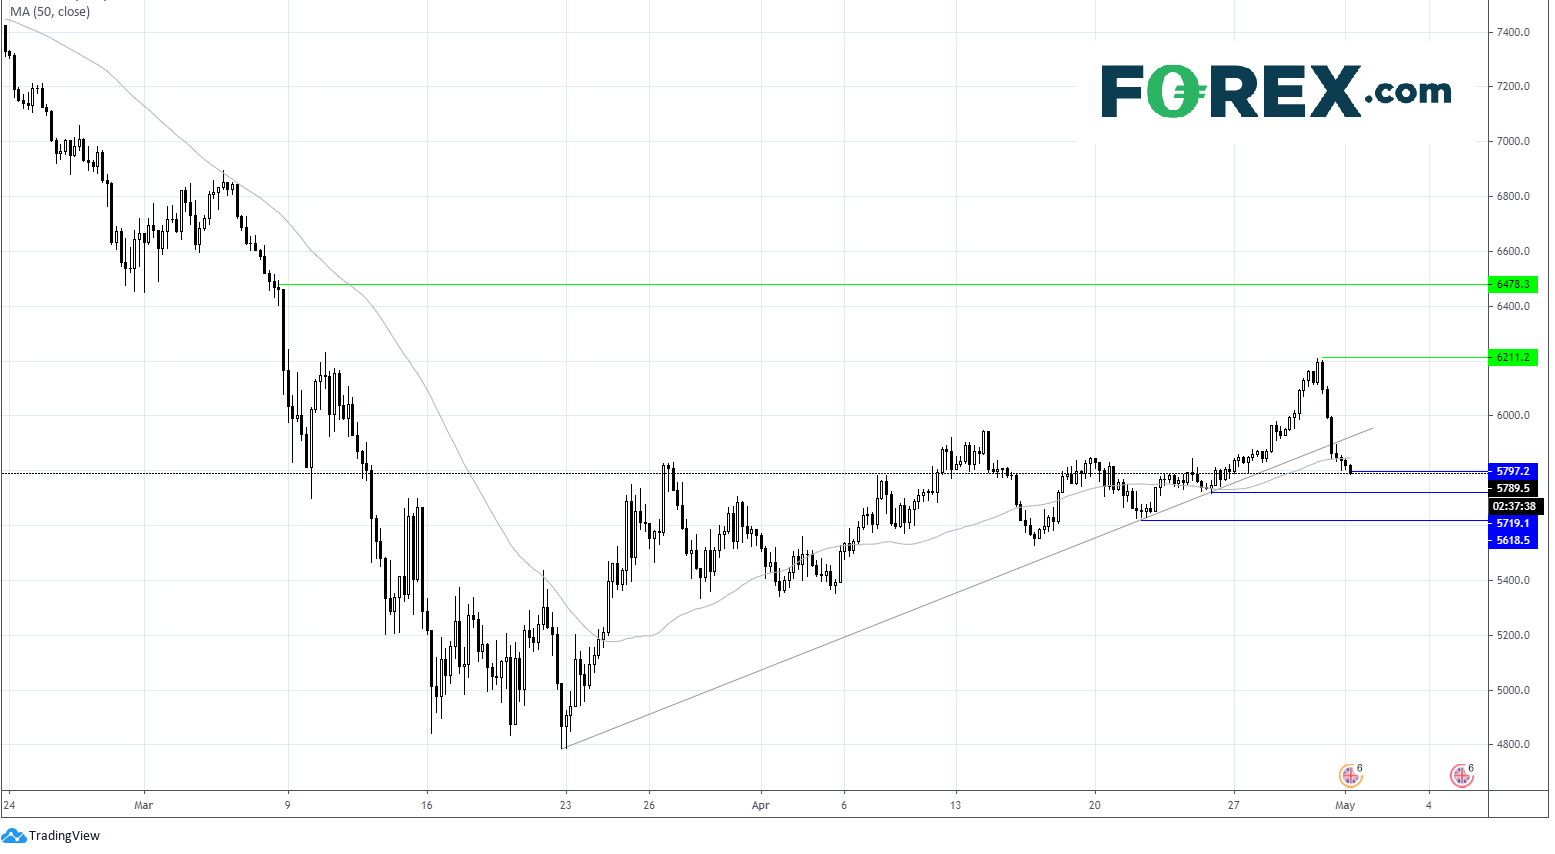
FTSE chart
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.