




US open Dow rebounds Nasdaq lags on net neutrality revival
US stocks set to broadly rebound although big tech will be in focus with Biden looking to revive net-neutrality rules.
Share this:

US futures
Dow futures +0.7% at 34667
S&P futures +0.4% at 4340
Nasdaq futures 0.01% at 14725
In Europe
FTSE +0.7% at 7081
Dax 1.% at 15566
Euro Stoxx +1.3% at 4045
Dow leads recovery, Nasdaq lags
US stocks are set to rebound on the open after steep losses in the previous session. The overall outlook remains upbeat, particularly with regards to corporate earnings which are drawing into focus as the US banks kick off earnings season next week.
Covid cases are on the rise, particularly in Asia, but for now that is not going to derail the rally. Yesterday’s selloff looks to be more of a technical pullback rather than owing to serious fundamental changes to the outlook.
On the virus front, Pfizer plans to request emergency authorization for a third booster dose of its covid vaccine, which is believes will be more effective against the Delta strain.
The Nasdaq set to lag behind its peers, with futures just breaking even. Big tech are coming under pressure after reports emerged that President Biden is encouraging regulators to re-instate Obama era rules on net-neutrality. This would encourage competition within certain sectors of the US -economy.
There is little in the way of data for investors to sink their teeth into. The Fed’s monetary policy report could attract some attention.
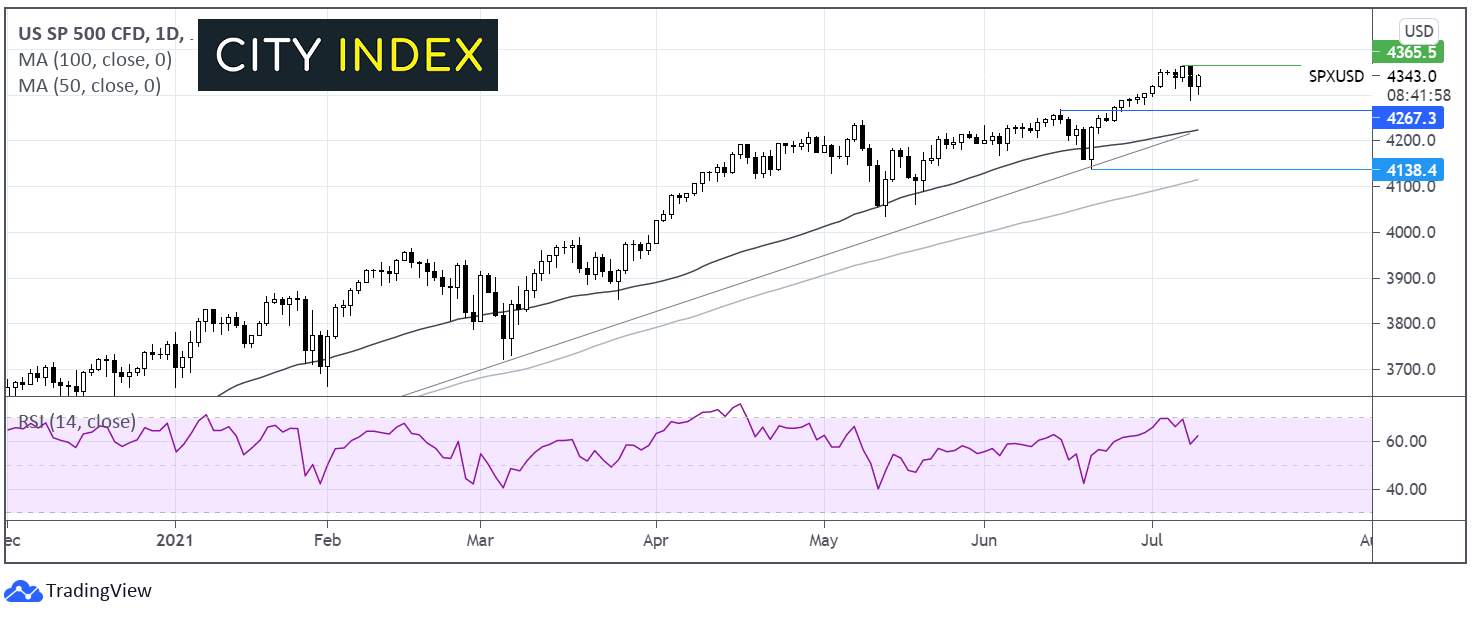
Where next for the S&P500?
The S&P500 is once again on the rise, yesterday’s selloff hasn’t even hit the sides of the rally. The pullback to a low of 4288 didn’t even bring the 50 sma into play. The RSI is in positive territory and pointing higher, suggesting that there could be more upside to come. Buyers need to break above 4360 to reach fresh all time highs. Sellers need a move below 4270 to negate the near term up trend. A fall below 4210 could see the sellers gai traction.
FX – GBP shrugs off weak GDP data
The US Dollar is edging lower despite both treasury yields and stocks rising.
EUR/USD -The pair is capitalizing on the weaker US Dollar. ECB president Christine Lagarde didn’t rock the boat in a speech today and there were no surprises in the minutes from the ECB meeting.
GBP/USD is rebounding from a deep selloff in the previous session shrugging off weak GDP data. UK GDP MoM in May rose 0.8% short of the 1.5% forecast. This was also down from April’s 2% GDP growth suggesting that growth was starting to slow even as the reopening was in full swing.
GBP/USD +0.24% at 1.3820
GBP/USD +0.24% at 1.3820
EUR/USD +0.1% at 1.1856
Oil extends rebound
Oil prices are rebounding for a second straight session following crude stockpile data. The data revealed that stock piles declined by 6.69 million barrels in the week ending 2 July, taking inventories to the lowest level since February last year, before the pandemic.
This is the seventh straight week of declining inventories and adds to evidence that demand is rising economies and the US driving season ramps up.
That said oil prices could struggle to retake recent multi year highs whilst the OPEC+ disagreement persists. With Saudi Arabia and UAE failing to see eye to eye over output increases the prospect of a price war for market share still exists.
Oil is set to decline 2.5% across the week
US crude trades +0.1% at $73.26
Brent trades +0.8% at $74.51
Looking ahead
15:00 US Whole sales inventories
17:00 Fed Monetary Policy Report
18:00 Baker Hughes Rig Count
GBP/USD +0.24% at 1.3820
EUR/USD +0.1% at 1.1856
Oil extends rebound
Oil prices are rebounding for a second straight session following crude stockpile data. The data revealed that stock piles declined by 6.69 million barrels in the week ending 2 July, taking inventories to the lowest level since February last year, before the pandemic.
This is the seventh straight week of declining inventories and adds to evidence that demand is rising economies and the US driving season ramps up.
That said oil prices could struggle to retake recent multi year highs whilst the OPEC+ disagreement persists. With Saudi Arabia and UAE failing to see eye to eye over output increases the prospect of a price war for market share still exists.
Oil is set to decline 2.5% across the week
US crude trades +0.1% at $73.26
Brent trades +0.8% at $74.51
Looking ahead
15:00 US Whole sales inventories
17:00 Fed Monetary Policy Report
18:00 Baker Hughes Rig Count
GBP/USD +0.24% at 1.3820
EUR/USD +0.1% at 1.1856
Oil extends rebound
Oil prices are rebounding for a second straight session following crude stockpile data. The data revealed that stock piles declined by 6.69 million barrels in the week ending 2 July, taking inventories to the lowest level since February last year, before the pandemic.
This is the seventh straight week of declining inventories and adds to evidence that demand is rising economies and the US driving season ramps up.
That said oil prices could struggle to retake recent multi year highs whilst the OPEC+ disagreement persists. With Saudi Arabia and UAE failing to see eye to eye over output increases the prospect of a price war for market share still exists.
Oil is set to decline 2.5% across the week
US crude trades +0.1% at $73.26
Brent trades +0.8% at $74.51
Looking ahead
15:00 US Whole sales inventories
17:00 Fed Monetary Policy Report
18:00 Baker Hughes Rig Count
Open a Forex.com account, or log-in if you’re already a customer.
US futures
Dow futures +0.7% at 34667
S&P futures +0.4% at 4340
Nasdaq futures 0.01% at 14725
In Europe
FTSE +0.7% at 7081
Dax 1.% at 15566
Euro Stoxx +1.3% at 4045
Learn more about trading indices
Dow leads recovery, Nasdaq lags
US stocks are set to rebound on the open after steep losses in the previous session. The overall outlook remains upbeat, particularly with regards to corporate earnings which are drawing into focus as the US banks kick off earnings season next week.
Covid cases are on the rise, particularly in Asia, but for now that is not going to derail the rally. Yesterday’s selloff looks to be more of a technical pullback rather than owing to serious fundamental changes to the outlook.
On the virus front, Pfizer plans to request emergency authorization for a third booster dose of its covid vaccine, which is believes will be more effective against the Delta strain.
The Nasdaq set to lag behind its peers, with futures just breaking even. Big tech are coming under pressure after reports emerged that President Biden is encouraging regulators to re-instate Obama era rules on net-neutrality. This would encourage competition within certain sectors of the US -economy.
There is little in the way of data for investors to sink their teeth into. The Fed’s monetary policy report could attract some attention.
Where next for the S&P500?
The S&P500 is once again on the rise, yesterday’s selloff hasn’t even hit the sides of the rally. The pullback to a low of 4288 didn’t even bring the 50 sma into play. The RSI is in positive territory and pointing higher, suggesting that there could be more upside to come. Buyers need to break above 4360 to reach fresh all time highs. Sellers need a move below 4270 to negate the near term up trend. A fall below 4210 could see the sellers gai traction.
FX – GBP shrugs off weak GDP data
The US Dollar is edging lower despite both treasury yields and stocks rising.
EUR/USD -The pair is capitalizing on the weaker US Dollar. ECB president Christine Lagarde didn’t rock the boat in a speech today and there were no surprises in the minutes from the ECB meeting.
GBP/USD is rebounding from a deep selloff in the previous session shrugging off weak GDP data. UK GDP MoM in May rose 0.8% short of the 1.5% forecast. This was also down from April’s 2% GDP growth suggesting that growth was starting to slow even as the reopening was in full swing.
GBP/USD +0.24% at 1.3820
EUR/USD +0.1% at 1.1856
Oil extends rebound
Oil prices are rebounding for a second straight session following crude stockpile data. The data revealed that stock piles declined by 6.69 million barrels in the week ending 2 July, taking inventories to the lowest level since February last year, before the pandemic.
This is the seventh straight week of declining inventories and adds to evidence that demand is rising economies and the US driving season ramps up.
That said oil prices could struggle to retake recent multi year highs whilst the OPEC+ disagreement persists. With Saudi Arabia and UAE failing to see eye to eye over output increases the prospect of a price war for market share still exists.
Oil is set to decline 2.5% across the week
US crude trades +0.1% at $73.26
Brent trades +0.8% at $74.51
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
15:00 US Whole sales inventories
17:00 Fed Monetary Policy Report
18:00 Baker Hughes Rig Count
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.
Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.