




US open Futures decline as ADP payrolls beat
US futures ease back from record highs. ADP beats forecasts at 692k, but investors wary ahead of Friday's NFP.
Share this:

US futures
Dow futures -0.17% at 34237
S&P futures -0.13% at 4286
Nasdaq futures -0.09% at 14562
In Europe
FTSE -0.5% at 7050
Dax -1.25% at 15531
Euro Stoxx -0.9% at 4071
Stocks ease back from record highs
US futures trade mildly lower, consolidating at record levels in the wake of stronger than expected ADP payroll data.
The private payroll report revealed that 692k new jobs were created in June, ahead of the 600k forecast. This was down from the almost 1 million private sector jobs created in May but is still a very solid print. Businesses are still scrambling to find workers as the economy continues to re-open.
Whilst inflation remains elevated, the Fed is looking for more progress in the US labour market recovery before tightening monetary policy. So far strong ADP data hasn’t been translating into strong US non-farm payroll numbers. Usually, the two reports are positively correlated. However, that hasn’t been the case recently.
Yesterday Moderna announced that its covid vaccine was effective against the highly infectious delta variant.
Despite the good news, the market is struggling to move higher ahead of Friday’s non farm payroll report. Few are prepared to take on large bullish bets when the market hovers at all time highs ahead of Friday’s jobs report.
Where next for the S&P 500?
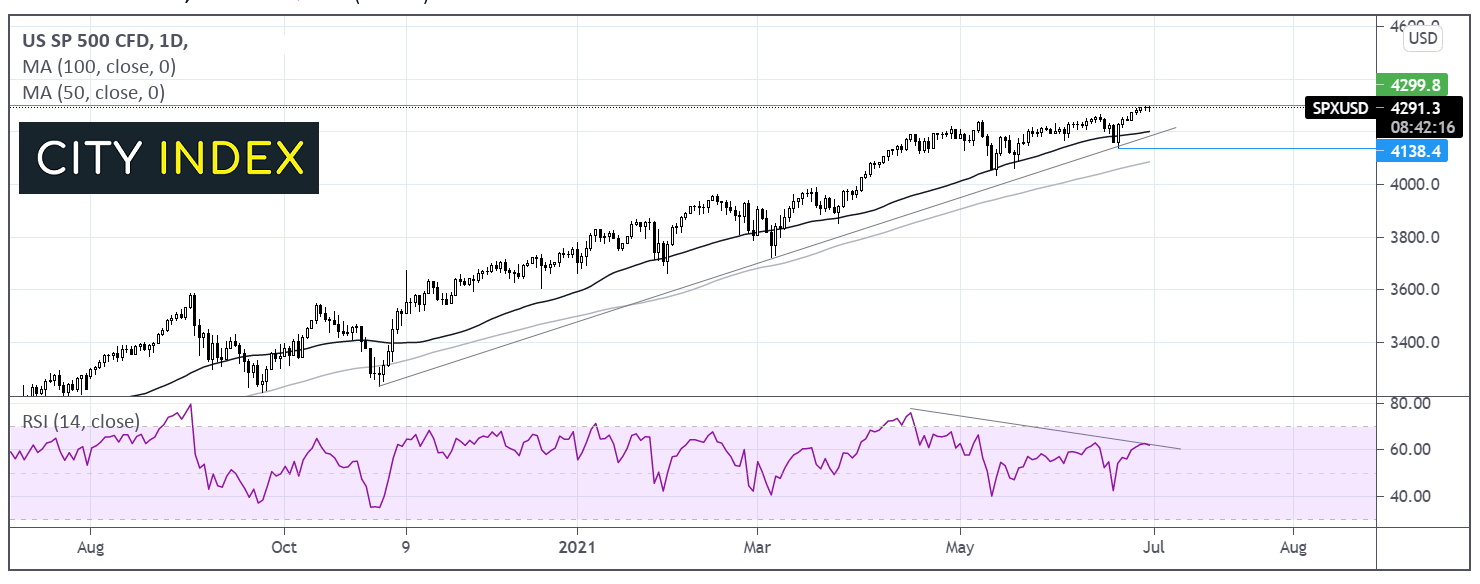
The S&P keeps grinding higher, hitting a fresh all time high of 4300 in the previous session. The index is ticking lower heading towards the open and the bearish divergence in the RSI suggests that momentum is slowing. It would take a move below 4200 the confluence of the multi-month ascending trendline, the 50 dma and horizontal support to negate the near term uptrend. Sellers could gain traction below 4138 the June 21 low. For the buyers 4300 is the target before looking for fresh all-time highs.
FX – USD rallies,
The US Dollar is edging higher for a sixth straight session and holding onto strong gains from the previous session. Strong US consumer sentiment numbers sent the US Dollar sharply higher.
GBP/USD has rebounded after hawkish comments from BoE’s Andy Haldane. The departing policymaker called for the unwinding of QE amid risks of surging inflation. Haldane sees inflation to be closer to 4% than 3% by the end of the year. His comments lifted the Pound, which had struggled for traction earlier in the session after the UK Q1 GDP final reading was downwardly revised to -1.6% quarter on quarter, from -1.5%.
GBP/USD +0.23% at 1.3868
EUR/USD -0.07% at 1.1888
Oil hits $75 after large inventory draw
Oil prices are bounding higher on Wednesday, extending gains for a second straight session. Both benchmarks continue to hover around two and a half year highs with Brent over $75 and WTI crude over $74.
The highly contagious Delta variant is spreading rapidly in some countries, promoting new lockdown restrictions. However, optimism surrounding a broader recovery in demand is keeping the bulls in control.
API reported a larger than expected draw on crude oil crude oil inventories of 8.2 million barrels. Attention will now turn to EIA data which is expected to show a -4.4-million-barrel draw.
Tomorrow the OPEC+ meeting begins. Expectations are growing that the group will raise production by 500,000 barrels per day, which could be comfortably absorbed into the market given the demand outlook. The OPEC sees demand rising by 6 million barrels per day in 2021, with 5 million of that coming in H2.
US crude trades +1.1% at $73.63
Brent trades +0.94% at $75.04
Looking ahead
15:00 Pending Home Sales
15:30 EIA Crude Oil Stocks
US futures
Dow futures -0.17% at 34237
S&P futures -0.13% at 4286
Nasdaq futures -0.09% at 14562
In Europe
FTSE -0.5% at 7050
Dax -1.25% at 15531
Euro Stoxx -0.9% at 4071
Stocks ease back from record highs
US futures trade mildly lower, consolidating at record levels in the wake of stronger than expected ADP payroll data.
The private payroll report revealed that 692k new jobs were created in June, ahead of the 600k forecast. This was down from the almost 1 million private sector jobs created in May but is still a very solid print. Businesses are still scrambling to find workers as the economy continues to re-open.
Whilst inflation remains elevated, the Fed is looking for more progress in the US labour market recovery before tightening monetary policy. So far strong ADP data hasn’t been translating into strong US non-farm payroll numbers. Usually, the two reports are positively correlated. However, that hasn’t been the case recently.
Yesterday Moderna announced that its covid vaccine was effective against the highly infectious delta variant.
Despite the good news, the market is struggling to move higher ahead of Friday’s non farm payroll report. Few are prepared to take on large bullish bets when the market hovers at all time highs ahead of Friday’s jobs report.
Where next for the S&P 500?
The S&P keeps grinding higher, hitting a fresh all time high of 4300 in the previous session. The index is ticking lower heading towards the open and the bearish divergence in the RSI suggests that momentum is slowing. It would take a move below 4200 the confluence of the multi-month ascending trendline, the 50 dma and horizontal support to negate the near term uptrend. Sellers could gain traction below 4138 the June 21 low. For the buyers 4300 is the target before looking for fresh all-time highs.
FX – USD holds gains, GBP rises
The US Dollar is edging higher for a sixth straight session and holding onto strong gains from the previous session. Strong US consumer sentiment numbers sent the US Dollar sharply higher.
GBP/USD has rebounded after hawkish comments from BoE’s Andy Haldane. The departing policymaker called for the unwinding of QE amid risks of surging inflation. Haldane sees inflation to be closer to 4% than 3% by the end of the year. His comments lifted the Pound, which had struggled for traction earlier in the session after the UK Q1 GDP final reading was downwardly revised to -1.6% quarter on quarter, from -1.5%.
GBP/USD +0.23% at 1.3868
EUR/USD -0.07% at 1.1888
Oil hits $75 after large inventory draw
Oil prices are bounding higher on Wednesday, extending gains for a second straight session. Both benchmarks continue to hover around two and a half year highs with Brent over $75 and WTI crude over $74.
The highly contagious Delta variant is spreading rapidly in some countries, promoting new lockdown restrictions. However, optimism surrounding a broader recovery in demand is keeping the bulls in control.
API reported a larger than expected draw on crude oil crude oil inventories of 8.2 million barrels. Attention will now turm to EIA data which is expected to show a -4.4-million-barrel draw.
Tomorrow the OPEC+ meeting begins. Expectations are growing that the group will raise production by 500,000 barrels per day, which could be comfortably absorbed into the market given the demand outlook. The OPEC sees demand rising by 6 million barrels per day in 2021, with 5 million of that coming in H2.
US crude trades +1.1% at $73.63
Brent trades +0.94% at $75.04
Looking ahead
15:00 Pending Home Sales
15:30 EIA Crude Oil Stocks
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.