



US open: Stocks drop on Fed jitters
Stocks head lower as nerves set in ahead of the Fed's rate decision tomorrow and after the Swedish central bank hiked rates by 1%, ahead of forecasts.
Share this:

US futures
Dow futures -0.6% at 30879
S&P futures -0.67% at 3873
Nasdaq futures -0.7% at 11868
In Europe
FTSE -0.35% at 7211
Dax -1% at 12695
Euro Stoxx -0.8% at 3422
Central banks are the only game in town
US stocks are pointing southwards as investors position themselves for the Federal Reserve’s interest rate decision tomorrow, after a larger-than-expected rate hike in Sweden.
The Swedish central bank hiked rates by a full 1%, its largest hike in 3 decades and above the 75 basis points forecast. Could this be a sign of things to come from the Fed?
The Fed is widely expected to hike rates by 75 basis points, the third straight 75 bps hike, as they look to rein in inflation and will also provide new economic projections. Volumes remain light and the mood cautious, with few looking to take on large positions before hearing what the Fed says and where policymakers see rates going by the end of the hiking cycle. This is what will drive the markets, not the rate hike tomorrow, but what the Fed plan to do next.
Today there are some mid-tier data points due, housing permits, and housing starts. These come as data surrounding the housing market has broadly shown a cooling in the sector as interest rates rise.
Corporate news:
Ford is falling some 5% lower pre-market after warning that supplier’s costs were expected to be around $1 billion higher due to inflation and supply chain issues. The automaker reaffirmed full-year guidance, but that hasn’t stemmed the selloff.
Where next for the Nasdaq?
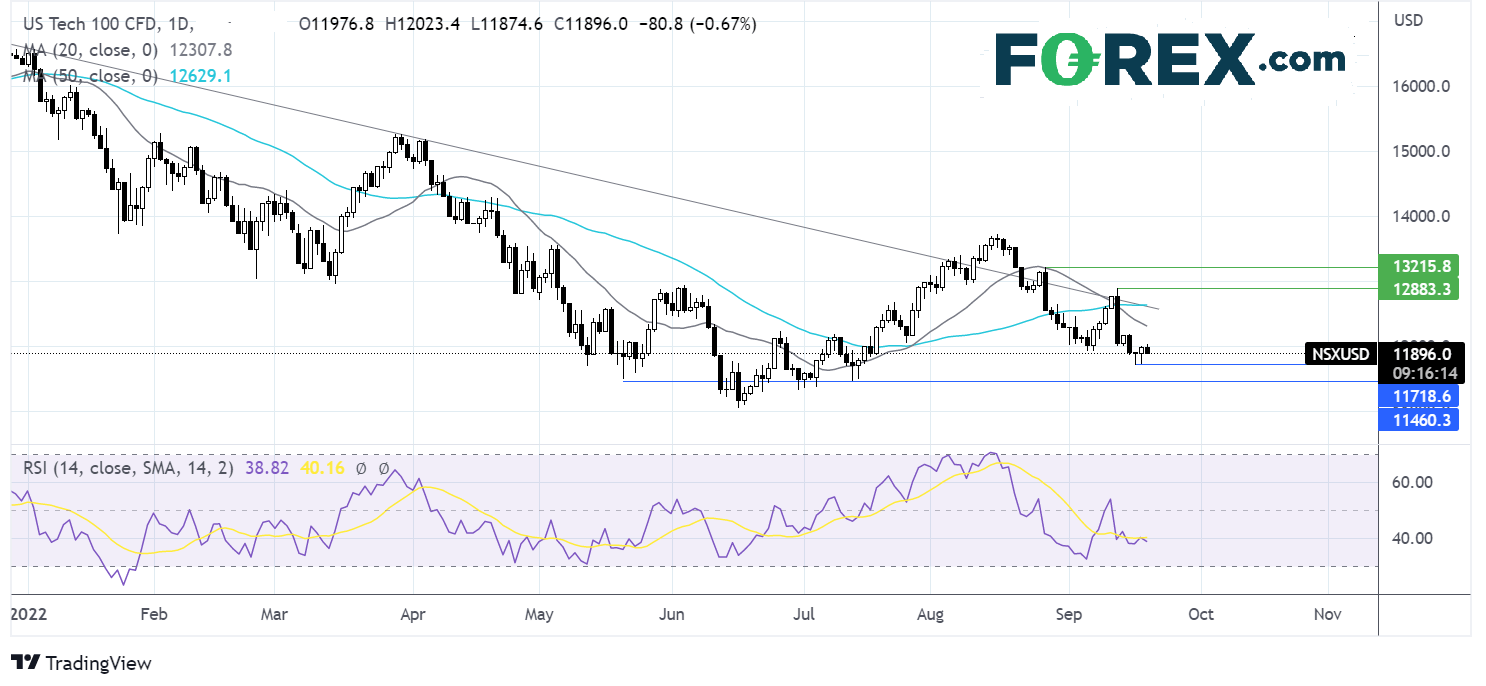
The Nasdaq failed to close over the falling trendline resistance, falling below the 20&50 sma, and took out last week’s low of 11900. This, combined with the 20 sma crossing below the 50 sma and the bearish RSI, suggests that there is more downside to come. Should buyers fail to defend 11700, last week’s low, sellers will look towards support around 11430 ahead of 11036, the 2022 low. On the flip side, a rise above 12300, the 20 sma, and 12620, the falling trendline resistance, would open the door to 12900, the weekly high.
FX markets – USD rises, GBP edges higher.
The USD is rising as attention is focused on the FOMC meeting, which kicks off today. Hawkish Fed bets and safe haven flows to keep the greenback supported.
EUR/USD is falling despite German PPI unexpectedly rising to a record level of 45.3% YoY, up from 37.2%, owing to surging energy costs. ECB Lagarde is due to speak later today. Recent ECB speakers have been in favour of smaller rate hikes after the latest jumbo-sized hike. Will Lagarde follow suit?
GBP/USD is edging higher above 1.14 but looks vulnerable as investors focus on the Fed and BoE monetary policy meetings this week and potential divergence. While the Fed is looking at a 75 basis point or 100 basis point hike, the BoE is looking at a 50 or 75 basis point hike.
GBP/USD +0.12% at 1.1446
EUR/USD -0.13% at 1.00
Oil hovers around 85.00
Oil is edging lower, slipping below 85.00 per barrel and paring modest gains from yesterday. While OPEC+ producing less than the quota is keeping supply challenges under the spotlight, all eyes are on the Fed’s rate decision for the next catalyst.
Even as output by OPEC+ missed the quota by 3.583 million barrels in August, the fact that prices fell anyway says a lot about the demand side of the equation.
The price has fallen 30% from June highs and are on track for the fourth straight month of declines as investors fret over the stronger USD and slowing growth hitting the demand outlook. Both Brent and WTI crude is set for the worst quarterly decline in percentage terms since the start of the pandemic.
WTI crude trades -0.6% at $84.33
Brent trades -0.5% at $91.00
Looking ahead
21:30 API crude oil stockpiles
US futures
Dow futures -0.6% at 30879
S&P futures -0.67% at 3873
Nasdaq futures -0.7% at 11868
In Europe
FTSE -0.35% at 7211
Dax -1% at 12695
Euro Stoxx -0.8% at 3422
Learn more about trading indices
Central banks are the only game in town
US stocks are pointing southwards as investors position themselves for the Federal Reserve’s interest rate decision tomorrow, after a larger-than-expected rate hike in Sweden.
The Swedish central bank hiked rates by a full 1%, its largest hike in 3 decades and above the 75 basis points forecast. Could this be a sign of things to come from the Fed?
The Fed is widely expected to hike rates by 75 basis points, the third straight 75 bps hike, as they look to rein in inflation and will also provide new economic projections. Volumes remain light and the mood cautious, with few looking to take on large positions before hearing what the Fed says and where policymakers see rates going by the end of the hiking cycle. This is what will drive the markets, not the rate hike tomorrow, but what the Fed plan to do next.
Today there are some mid-tier data points due, housing permits, and housing starts. These come as data surrounding the housing market has broadly shown a cooling in the sector as interest rates rise.
Corporate news:
Ford is falling some 5% lower pre-market after warning that supplier’s costs were expected to be around $1 billion higher due to inflation and supply chain issues. The automaker reaffirmed full-year guidance, but that hasn’t stemmed the selloff.
Where next for the Nasdaq?
The Nasdaq failed to close over the falling trendline resistance, falling below the 20&50 sma, and took out last week’s low of 11900. This, combined with the 20 sma crossing below the 50 sma and the bearish RSI, suggests that there is more downside to come. Should buyers fail to defend 11700, last week’s low, sellers will look towards support around 11430 ahead of 11036, the 2022 low. On the flip side, a rise above 12300, the 20 sma, and 12620, the falling trendline resistance, would open the door to 12900, the weekly high.

FX markets – USD rises, GBP edges higher.
The USD is rising as attention is focused on the FOMC meeting, which kicks off today. Hawkish Fed bets and safe haven flows to keep the greenback supported.
EUR/USD is falling despite German PPI unexpectedly rising to a record level of 45.3% YoY, up from 37.2%, owing to surging energy costs. ECB Lagarde is due to speak later today. Recent ECB speakers have been in favour of smaller rate hikes after the latest jumbo-sized hike. Will Lagarde follow suit?
GBP/USD is edging higher above 1.14 but looks vulnerable as investors focus on the Fed and BoE monetary policy meetings this week and potential divergence. While the Fed is looking at a 75 basis point or 100 basis point hike, the BoE is looking at a 50 or 75 basis point hike.
GBP/USD +0.12% at 1.1446
EUR/USD -0.13% at 1.00
Oil hovers around 85.00
Oil is edging lower, slipping below 85.00 per barrel and paring modest gains from yesterday. While OPEC+ producing less than the quota is keeping supply challenges under the spotlight, all eyes are on the Fed’s rate decision for the next catalyst.
Even as output by OPEC+ missed the quota by 3.583 million barrels in August, the fact that prices fell anyway says a lot about the demand side of the equation.
The price has fallen 30% from June highs and are on track for the fourth straight month of declines as investors fret over the stronger USD and slowing growth hitting the demand outlook. Both Brent and WTI crude is set for the worst quarterly decline in percentage terms since the start of the pandemic.
WTI crude trades -0.6% at $85.33
Brent trades -0.8% at $91.00
Learn more about trading oil here.
Looking ahead
21:30 API crude oil stockpiles
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.