



US open: Stocks edge lower with earnings, PMI data in focus
US stocks are set to open lower as earnings ramp up and ahead of US PPI data, which is expected to fall further.
Share this:

US futures
Dow futures -0.32% at 33513
S&P futures -0.36% at 4004
Nasdaq futures -0.57% at 11807
In Europe
FTSE -0.47% at 7757
Dax -0.32% at 15047
Microsoft reports after the close
US stocks are set to open mildly lower after gains in the previous session as investors digest the latest corporate earnings and look ahead to PMI data.
Whilst stocks gained yesterday on optimism that the Fed will slow its pace of interest rate hikes. The Federal Reserve will meet next week and are expected to slow the pace of rate hikes to 25 basis points. The market is also optimistic of 2 25 basis points rate cuts before the end of the year.
Today, however, the mood is more cautious, with concerns over a recession weighing on sentiment as PMI data comes into view.
The monthly PMI release is expected to show that business activity contracted at a faster pace in January, dropping to 44.7, down from 45. Weak PMI data could fuel recession bets further.
Earnings are very much in focus as earnings season steps up a gear with a raft of earnings due from several key firms, including General Electric, Verizon, and Johnson & Johnson, before the opening bell and tech giant Microsoft is expected to update the market after the closing bell.
Corporate news
GE rises after posting stronger than expected EOS of $1.24 ahead of the $1.27 forecast. The aerospace business. However, the renewables business is expected to be weaker than expected in 2023.
Microsoft is due to report later today and is expected to reveal a modest drop in profit despite a rise in revenue of around 8%. The Firm has also announced job cuts ahead of earnings and is hoping that an investment in Open AI will sustain future growth amid signs that its cloud business is slowing.
Where next for the Nasdaq?
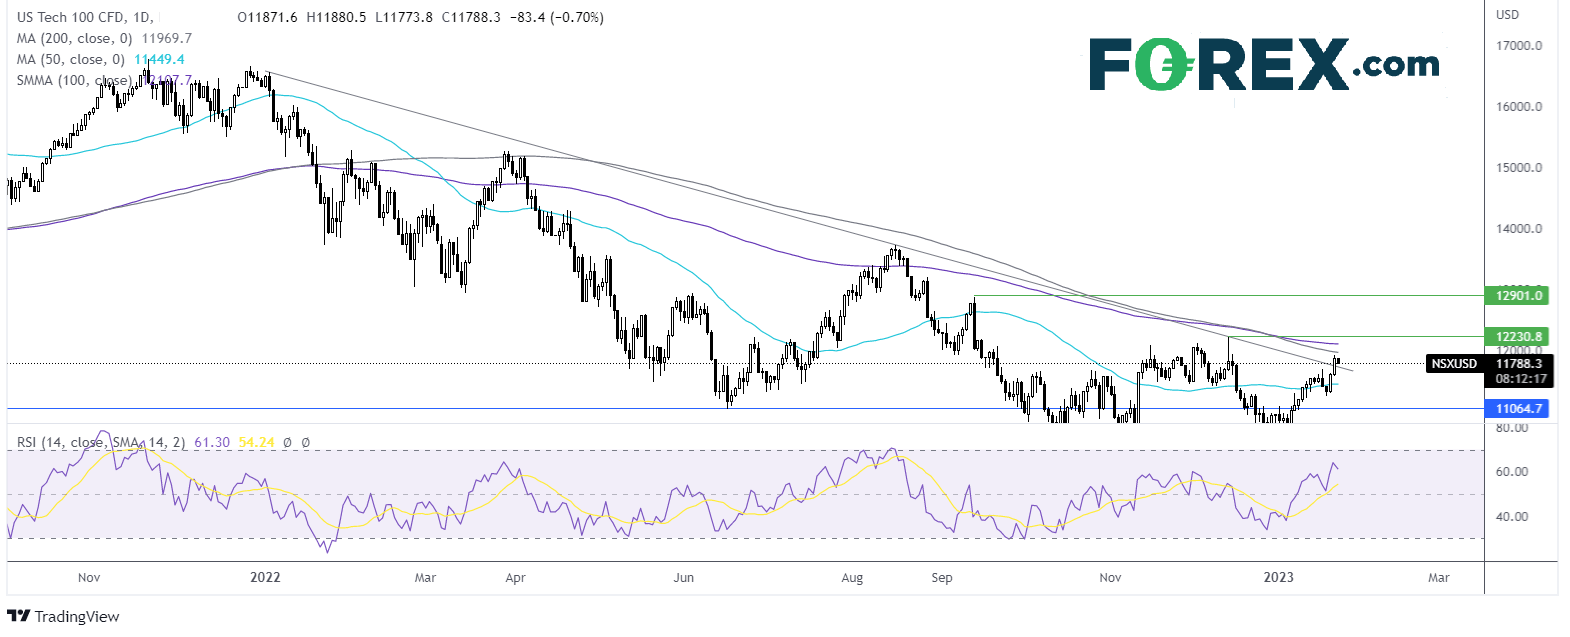
Nasdaq has extended it’s run up from 10665, rising above its 50 sma, which along with the RSI above 50 are, keeping buyers hopeful of further upside. Buyers have risen above the multi-month rising trendline but need a push over the 200 sma at 11980 and 12000 psychological level to bring 12230, the December high, into play. Above here a rose towards 12900, the September high could be on the cards. Meanwhile, immediate resistance is at 11700, the falling trendline, and 11400, the 50 sma. A break below here could open the door to 11000, round number.
FX markets – USD rises, GBP falls
The USD is rising cautiously but continues to hover around 9-month lows as the market weighs up an expected slowdown in the pace of Fed rate hikes, in addition to worries of a recession in the US.
GBP/USD is falling after weaker-than-expected flash PMI composite data. The PMI unexpectedly fell to 47.8, down from 49 and defying expectations of a rise to 49.1. UK government borrowing more than doubled in December, showing the highest level since records began in 1993.
EUR/USD is holding steady against the stronger U.S. dollar after business activity expanded in January. The composite PMI rose above 50 the level for separating expansion and contraction to 50.2, thanks to a recovering service sector. The data suggests that a eurozone recession could be milder than initially feared.
GBP/USD -0.43% at 1.2310
EUR/USD -0.02% at 1.0868
Oil holds steady ahead of API data
Oil prices are holding broadly steady as investors continue weighing up the Chinese economic reopening against concerns of a US recession.
PMI data due later today could suggest that the US economy is contracting, which would be bad news for the oil demand outlook.
Investors will also be looking toward the release of API inventory data which is expected to show that U.S. stocks of crude oil and gasoline rose last week while distillate stocks fell.
Meanwhile, the dollar hovering around a 9-month low has also helped to support the price of oil and other dollar-denominated commodities.
WTI crude trades +0.3% at $81.34
Brent trades at +0.25% at $88.35
Looking ahead
14:45 US PMI data
US futures
Dow futures -0.32% at 33513
S&P futures -0.36% at 4004
Nasdaq futures -0.57% at 11807
In Europe
FTSE -0.47% at 7757
Dax -0.32% at 15047
Learn more about trading indices
Microsoft reports after the close
US stocks are set to open mildly lower after gains in the previous session as investors digest the latest corporate earnings and look ahead to PMI data.
Whilst stocks gained yesterday on optimism that the Fed will slow its pace of interest rate hikes. The Federal Reserve will meet next week and are expected to slow the pace of rate hikes to 25 basis points. The market is also optimistic of 2 25 basis points rate cuts before the end of the year.
Today, however, the mood is more cautious, with concerns over a recession weighing on sentiment as PMI data comes into view.
The monthly PMI release is expected to show that business activity contracted at a faster pace in January, dropping to 44.7, down from 45. Weak PMI data could fuel recession bets further.
Earnings are very much in focus as earnings season steps up a gear with a raft of earnings due from several key firms, including General Electric, Verizon, and Johnson & Johnson, before the opening bell and tech giant Microsoft is expected to update the market after the closing bell.
Corporate news
GE rises after posting stronger than expected EOS of $1.24 ahead of the $1.27 forecast. The aerospace business. However, the renewables business is expected to be weaker than expected in 2023.
Microsoft is due to report later today and is expected to reveal a modest drop in profit despite a rise in revenue of around 8%. The Firm has also announced job cuts ahead of earnings and is hoping that an investment in Open AI will sustain future growth amid signs that its cloud business is slowing.
Where next for the Nasdaq?
Nasdaq has extended it’s run up from 10665, rising above its 50 sma, which along with the RSI above 50 are, keeping buyers hopeful of further upside. Buyers have risen above the multi-month rising trendline but need a push over the 200 sma at 11980 and 12000 psychological level to bring 12230, the December high, into play. Above here a rose towards 12900, the September high could be on the cards. Meanwhile, immediate resistance is at 11700, the falling trendline, and 11400, the 50 sma. A break below here could open the door to 11000, round number.

FX markets – USD rises, GBP falls
The USD is rising cautiously but continues to hover around 9-month lows as the market weighs up an expected slowdown in the pace of Fed rate hikes, in addition to worries of a recession in the US.
GBP/USD is falling after weaker-than-expected flash PMI composite data. The PMI unexpectedly fell to 47.8, down from 49 and defying expectations of a rise to 49.1. UK government borrowing more than doubled in December, showing the highest level since records began in 1993.
EUR/USD is holding steady against the stronger U.S. dollar after business activity expanded in January. The composite PMI rose above 50 the level for separating expansion and contraction to 50.2, thanks to a recovering service sector. The data suggests that a eurozone recession could be milder than initially feared.
GBP/USD -0.43% at 1.2310
EUR/USD -0.02% at 1.0868
Oil rises as China’s holiday begins
Oil prices are holding broadly steady as investors continue weighing up the Chinese economic reopening against concerns of a US recession.
PMI data due later today could suggest that the US economy is contracting, which would be bad news for the oil demand outlook.
Investors will also be looking toward the release of API inventory data which is expected to show that U.S. stocks of crude oil and gasoline rose last week while distillate stocks fell.
Meanwhile, the dollar hovering around a 9-month low has also helped to support the price of oil and other dollar-denominated commodities.
WTI crude trades +0.3% at $81.34
Brent trades at +0.25% at $88.35
Learn more about trading oil here.
Looking ahead
14:45 US PMI data
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.