



US open: Stocks jump after inflation cools by more than forecast
US stocks surge as CPI and core CPI cool paving the way for a less hawkish Federal Reserve.
Share this:

US futures
Dow futures +2% at 34704
S&P futures +2.7% at 4100
Nasdaq futures +3.75% at 12160
In Europe
FTSE +0.7% at 7503
Dax +1.8% at 14516
Inflation & core CPI fall raising dovish Fed hopes
US stocks have shot higher following the release of cooler-than-expected US inflation data which is prompting bets of a less hawkish Federal Reserve.
US CPI fell to 7.1% YoY in November, down from 7.7% YoY in October and below the 7.3% forecast. Core inflation also fell, dropping to 6%, down from 6.3%. On a monthly basis core CPI posted the smallest monthly increase in over a year, rising 0.2%. The data supports expectations that the Federal Reserve will slow the pace of interest rate hikes from the December meeting.
The data comes ahead of tomorrow's Federal Reserve interest rate decision, and the market is now pricing in an 80% probability of 50 basis point rate hike and a 20% probability of a 75-basis point rate hike.
Inflation has now fallen over the past few months from a peak of 9.1%. With several months of falling inflation, it is safe to say a trend is forming. The Fed is expected to continue hiking interest rates in Q1, which, combined with the US economy falling into an expected recession, will help to tame inflation further. The market even sees the Fed cutting interest rates before the end of next year.
The USD has fallen sharply following the release, while Gold and stocks, particularly the Nasdaq, has jumped higher.
Where next for the S&P500?
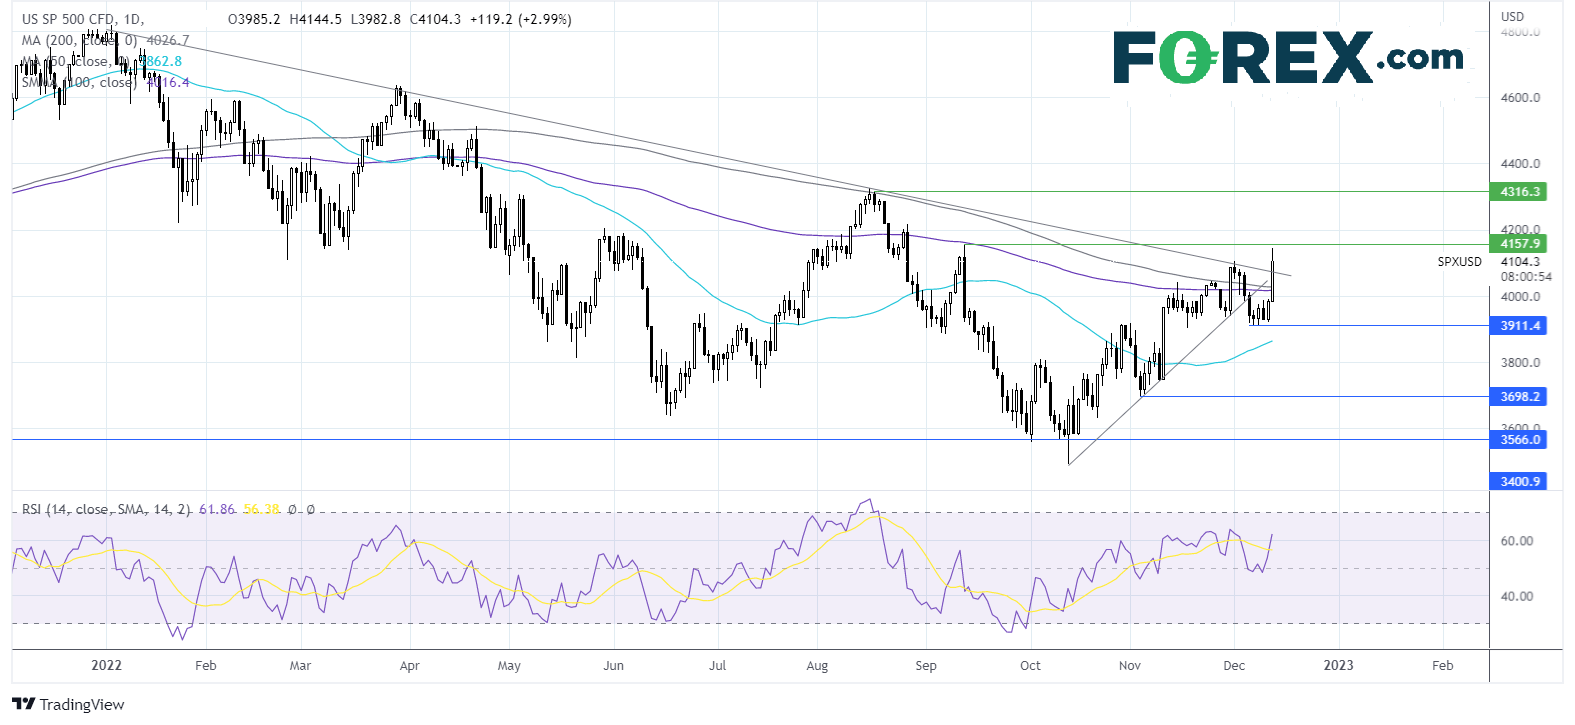
The S&P500 Found the port last week at 3910 and is rebounding higher. The RSI is about 15 and supports further upside. Buyers have risen over 4015/25 the 100 & 200 smas and is testing the falling trendline support. A rise above here opens the door to 4100 the December high, and 4160 the September high. On the downside, support can be seen at the 100 & 200 smas ahead of 3910, the December low.
FX markets – USD drops, GBP jumps.
The USD is falling sharply after US inflation data cooled by more than expected, raising the chances of a more dovish Federal Reserve going forwards.
EURUSD is rising owing to a weaker USD after German inflation data confirmed the initial reading of 10.3% and after German ZEW economic sentiment improved by more than expected economic sentiment was -23.3, up from -36.7 and ahead of forecasts of -26.4. German investor morale has proved for the third straight month and is now at the highest level the start of the Ukraine war.
GBP/USD rose to 1.23 in early trade after UK jobs data showed that unemployment ticked higher to 3.7% and wage growth also accelerated. Wages grew at 6.1% up from 5.8% and ahead of forecasts. data piles pressure on the Bank of England to continue hiking interest rates aggressively
GBP/USD +1.20% at 1.2391
EUR/USD +1.3% at 1.0650
Oil rises
Oil prices are rising for a third straight day recovering from declines of over $1 earlier in the session.
Oil fell in early trade after China’s leaders delayed a policy meeting amid surging COVID cases which raised concerns of a potential policy U-turn regarding the move away from zero COVID.
The successful reopening of China would be key to boosting oil prices, and according to Bank of America and Goldman Sachs, oil could rise to $90 per barrel should China manage to end its zero-Covid stance.
The price is also finding support from potential lower supply from Russia as a response to the G7 oil and price cap. Expectations are for export volume for Russia's Baltic and Black Sea ports to fall this month.
Attention will now turn 2 the OPEC monthly report and US inflation data as well as the API inventory figures due later today.
WTI crude trades +0.8% at $73.70
Brent trades at +1% at $78.8
US futures
Dow futures +2% at 34704
S&P futures +2.7% at 4100
Nasdaq futures +3.75% at 12160
In Europe
FTSE +0.7% at 7503
Dax +1.8% at 14516
Learn more about trading indices
Inflation & core CPI fall raising dovish Fed hopes
US stocks have shot higher following the release of cooler-than-expected US inflation data which is prompting bets of a less hawkish Federal Reserve.
US CPI fell to 7.1% YoY in November, down from 7.7% YoY in October and below the 7.3% forecast. Core inflation also fell, dropping to 6%, down from 6.3%. On a monthly basis core CPI posted the smallest monthly increase in over a year, rising 0.2%. The data supports expectations that the Federal Reserve will slow the pace of interest rate hikes from the December meeting.
The data comes ahead of tomorrow's Federal Reserve interest rate decision, and the market is now pricing in an 80% probability of 50 basis point rate hike and a 20% probability of a 75-basis point rate hike.
Inflation has now fallen over the past few months from a peak of 9.1%. With several months of falling inflation, it is safe to say a trend is forming. The Fed is expected to continue hiking interest rates in Q1, which, combined with the US economy falling into an expected recession, will help to tame inflation further. The market even sees the Fed cutting interest rates before the end of next year.
The USD has fallen sharply following the release, while Gold and stocks, particularly the Nasdaq, has jumped higher.
Where next for the S&P500?
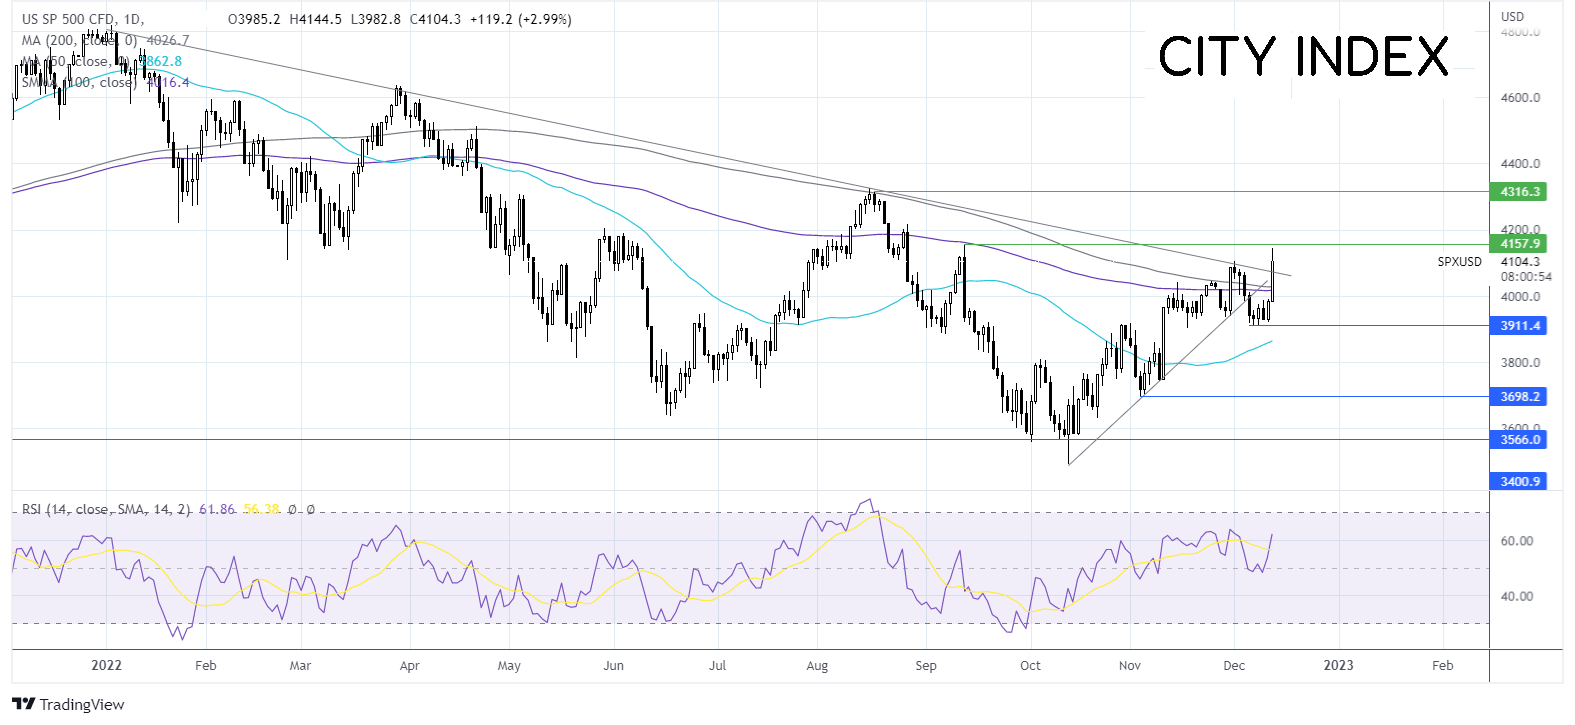
The S&P500 Found the port last week at 3910 and is rebounding higher. The RSI is about 15 and supports further upside. Buyers have risen over 4015/25 the 100 & 200 smas and is testing the falling trendline support. A rise above here opens the door to 4100 the December high, and 4160 the September high. On the downside, support can be seen at the 100 & 200 smas ahead of 3910, the December low.
FX markets – USD drops, GBP jumps.
The USD is falling sharply after US inflation data cooled by more than expected, raising the chances of a more dovish Federal Reserve going forwards.
EURUSD is rising owing to a weaker USD after German inflation data confirmed the initial reading of 10.3% and after German ZEW economic sentiment improved by more than expected economic sentiment was -23.3, up from -36.7 and ahead of forecasts of -26.4. German investor morale has proved for the third straight month and is now at the highest level the start of the Ukraine war.
GBP/USD rose to 1.23 in early trade after UK jobs data showed that unemployment ticked higher to 3.7% and wage growth also accelerated. Wages grew at 6.1% up from 5.8% and ahead of forecasts. data piles pressure on the Bank of England to continue hiking interest rates aggressively
GBP/USD +1.20% at 1.2391
EUR/USD +1.3% at 1.0650
Oil rises
Oil prices are rising for a third straight day recovering from declines of over $1 earlier in the session.
Oil fell in early trade after China’s leaders delayed a policy meeting amid surging COVID cases which raised concerns of a potential policy U-turn regarding the move away from zero COVID.
The successful reopening of China would be key to boosting oil prices, and according to Bank of America and Goldman Sachs, oil could rise to $90 per barrel should China manage to end its zero-Covid stance.
The price is also finding support from potential lower supply from Russia as a response to the G7 oil and price cap. Expectations are for export volume for Russia's Baltic and Black Sea ports to fall this month.
Attention will now turn 2 the OPEC monthly report and US inflation data as well as the API inventory figures due later today.
WTI crude trades +0.8% at $73.70
Brent trades at +1% at $78.80
Learn more about trading oil here.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
Gold forecast: Rising yields become too hot for gold, but the outlook is far from bearish
Gold and silver prices took a plunge today, with the former down 3% and the latter falling some 5% by mid European session, before bouncing off their lows. The losses come after the metals remained largely supported until last week, despite the big dollar rally and surging bond yields as we have seen in recent weeks. But it simply got too much, and the metals succumbed to pressure today.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.