


US open: Stocks mixed Snap, Twitter disappoint
US stocks are mixed but are set for a weekly gain after broadly upbeat earnings in tech. However, Snap & Twitter disappointed.
Share this:

US futures
Dow futures +0.18% at 32100
S&P futures +0.1% at 3960
Nasdaq futures -0.35% at 12570
In Europe
FTSE +0.37% at 7250
Dax +0.8% at 13320
Euro Stoxx +0.4% at 3616
Stocks mixed but set for weekly gains
US stocks are pointing to a mixed start to trading on Friday, with the Nasdaq lower after Snap and Twitter earnings disappoint.
Earnings season is in full swing and so far have been broadly ahead of expectations. Rising costs, the stronger USD and slowing growth are areas that remain in focus.
Whilst Netflix and Tesla beat forecasts this week, boosting optimism, Snap is hurting the mood today after weaker earnings.
The markets have risen higher across the week, boosted by upbeat earnings and tempered expectations of aggressive Fed rate hikes.
The big test for the rally will be next week when faced with the Fed interest rates decision and more earnings from big tech, which have already indicated slower hiring and therefore slower spending.
Looking ahead US PMI data is expected to show that business activity growth slowed,. With the composite PMI is expected to slip to 51.7 in July from 52.3 in June.
In corporate news:
Snap was the first major tech firm to report Q2 earnings, and the picture was pretty grim, with the company falling 25% pre-market. The stock missed the top and bottom line and said that it plans to slow hiring substantially as it battles slowing revenue.
Twitter also disappointed on top and bottom lines citing weaker advertising revenue and uncertainty surrounding the Musk takeover.
Where next for the Nasdaq?
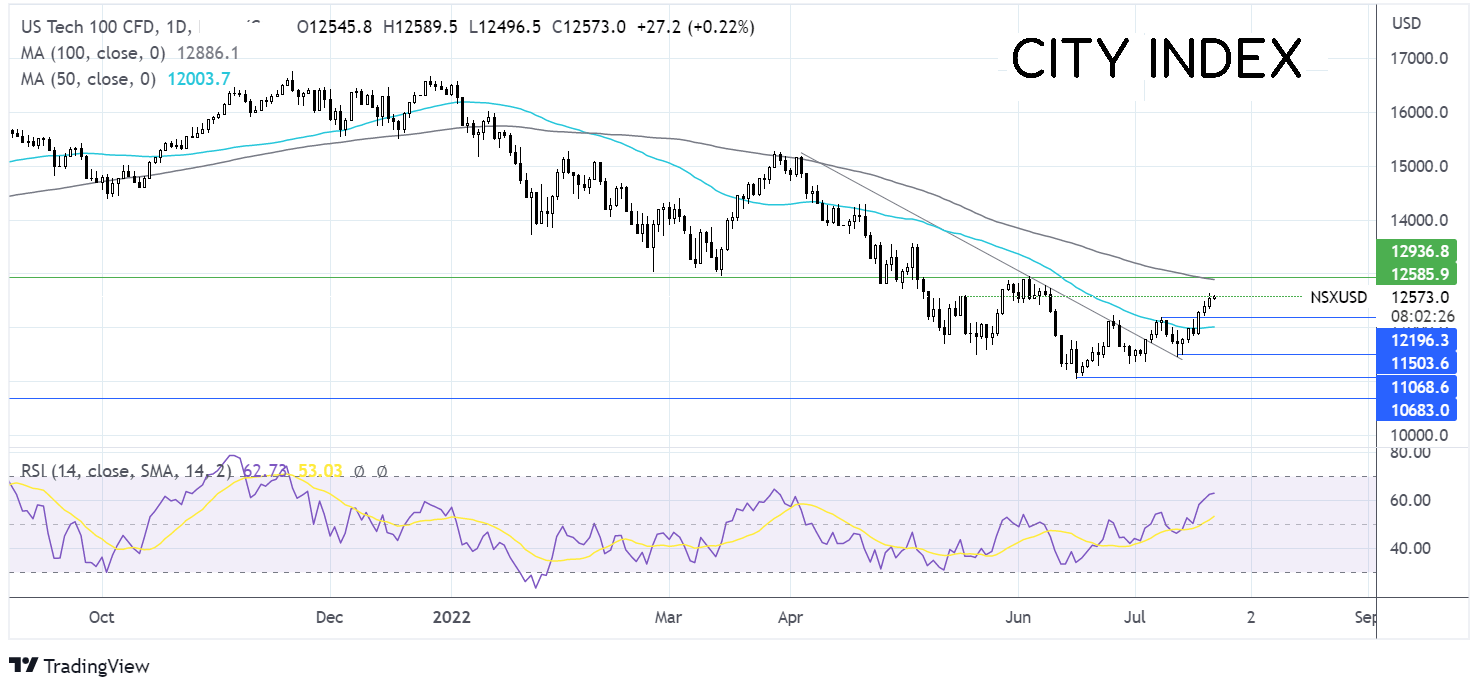
The Nasdaq is extending its rally from 2022 lows, retaking the 50 sna, which, combined with the bullish RSI, is keeping buyers optimistic about further gains. Buyers need to break above 12585, the 100 sma, and the June high. On the flip side, it would take a move below the 50 sma at 12040 to negate the near-term downtrend.

FX markets – USD rises, EUR falls.
USD is rising but is set for losses across the week as investors pare back expectations of a more aggressive rate hike. Higher than expected jobless claims yesterday raised recession concerns.
EURUSD is falling after PMI data showed that business activity slipped into contraction. The composite PMI fell to 49.4 in July, worse than the 51 forecasts and down from 52 in June. The data doesn’t bode well for GDP growth in the quarter.
GBP/USD is falling against a stronger USD and despite retail sales and business activity falling less than feared. Retail sales slipped -0.1% YoY, better than the -0.3% feared and up from -0.5%. The composite PMI data fell to 52.8, down from 53.7.
GBP/USD -0.06% at 1.1950
EUR/USD -0.5% at 1.0180
Oil falls by $5
Oil prices are falling, extending losses from the previous session and puts oil on track for losses of around 2.5% across the week, the third straight week of declines.
The weakening global demand outlook combined with the resumption of Libyan crude oil output is dragging on oil prices.
Macro data points to a global economic slowdown just as central banks are aggressively hiking rates. Slower growth hurts the demand outlook.
WTI crude trades -4.5% at $95.20
Brent trades -4% at $99.00
Looking ahead
N/A
US futures
Dow futures +0.18% at 32100
S&P futures +0.1% at 3960
Nasdaq futures -0.35% at 12570
In Europe
FTSE +0.37% at 7250
Dax +0.8% at 13320
Euro Stoxx +0.4% at 3616
Learn more about trading indices
Stocks mixed but set for weekly gains
US stocks are pointing to a mixed start to trading on Friday, with the Nasdaq lower after Snap and Twitter earnings disappoint.
Earnings season is in full swing and so far have been broadly ahead of expectations. Rising costs, the stronger USD and slowing growth are areas that remain in focus.
Whilst Netflix and Tesla beat forecasts this week, boosting optimism, Snap is hurting the mood today after weaker earnings.
The markets have risen higher across the week, boosted by upbeat earnings and tempered expectations of aggressive Fed rate hikes.
The big test for the rally will be next week when faced with the Fed interest rates decision and more earnings from big tech, which have already indicated slower hiring and therefore slower spending.
Looking ahead US PMI data is expected to show that business activity growth slowed,. With the composite PMI is expected to slip to 51.7 in July from 52.3 in June.
In corporate news:
Snap was the first major tech firm to report Q2 earnings, and the picture was pretty grim, with the company falling 25% pre-market. The stock missed the top and bottom line and said that it plans to slow hiring substantially as it battles slowing revenue.
Twitter also disappointed on top and bottom lines citing weaker advertising revenue and uncertainty surrounding the Musk takeover.
Where next for the Nasdaq?
The Nasdaq is extending its rally from 2022 lows, retaking the 50 sna, which, combined with the bullish RSI, is keeping buyers optimistic about further gains. Buyers need to break above 12585, the 100 sma, and the June high. On the flip side, it would take a move below the 50 sma at 12040 to negate the near-term downtrend.
FX markets – USD rises, EUR falls.
USD is rising but is set for losses across the week as investors pare back expectations of a more aggressive rate hike. Higher than expected jobless claims yesterday raised recession concerns.
EURUSD is falling after PMI data showed that business activity slipped into contraction. The composite PMI fell to 49.4 in July, worse than the 51 forecasts and down from 52 in June. The data doesn’t bode well for GDP growth in the quarter.
GBP/USD is falling against a stronger USD and despite retail sales and business activity falling less than feared. Retail sales slipped -0.1% YoY, better than the -0.3% feared and up from -0.5%. The composite PMI data fell to 52.8, down from 53.7.
GBP/USD -0.06% at 1.1950
EUR/USD -0.5% at 1.0180
Oil falls by $5
Oil prices are falling, extending losses from the previous session and puts oil on track for losses of around 2.5% across the week, the third straight week of declines.
The weakening global demand outlook combined with the resumption of Libyan crude oil output is dragging on oil prices.
Macro data points to a global economic slowdown just as central banks are aggressively hiking rates. Slower growth hurts the demand outlook.
WTI crude trades -4.5% at $95.20
Brent trades -4% at $99.00
Learn more about trading oil here.
Looking ahead
N/A
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Blue wave adds to Nikkei’s AI troubles
The Nikkei 225 has taken another beating as a Democratic sweep adds to concerns about AI investment returns. But after the scale of the earlier declines, how much bad news is already priced in?
US dollar outlook: Nasdaq breakdown raises stakes for EUR/USD, USD/JPY
A potential Democratic sweep of Congress is adding to the AI trade's headaches, with Nasdaq 100 futures breaking below a major technical level. The implications for the dollar could be significant.
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.