







Who Said the Yield Curve is Inverted
Could the current yield curve follow the same pattern as crude did?
Share this:

An inverted yield curve is said to be indicative of a recession. Why? Because the last 7 recessions were all preceded by an inverted yield curve. The yield curve we are referencing is the difference between the 10-year yield and the 2-year yield. Indeed, toward the end of August this yield curve did go briefly into negative territory for a few days. Does that mean a recession is ahead? Only time will tell. However, looking at today, we put in a bullish engulfing candle on a daily timeframe (in positive territory).
Source: Tradingview, City Index
The main reason for the bid was that the back end (longer term) bonds sold off at a faster rate than the front end (shorter term) bonds.
Source: Tradingview, City Index
Bonds and yields are inversely related. Therefore, yields rose faster in the back end than in the front end causing the yield curve to rise.
Will the yield curve turn negative again soon? Obviously, there is no way to tell, but let’s look at another instrument with a similar pattern and see what happened:
Source: Tradingview, City Index
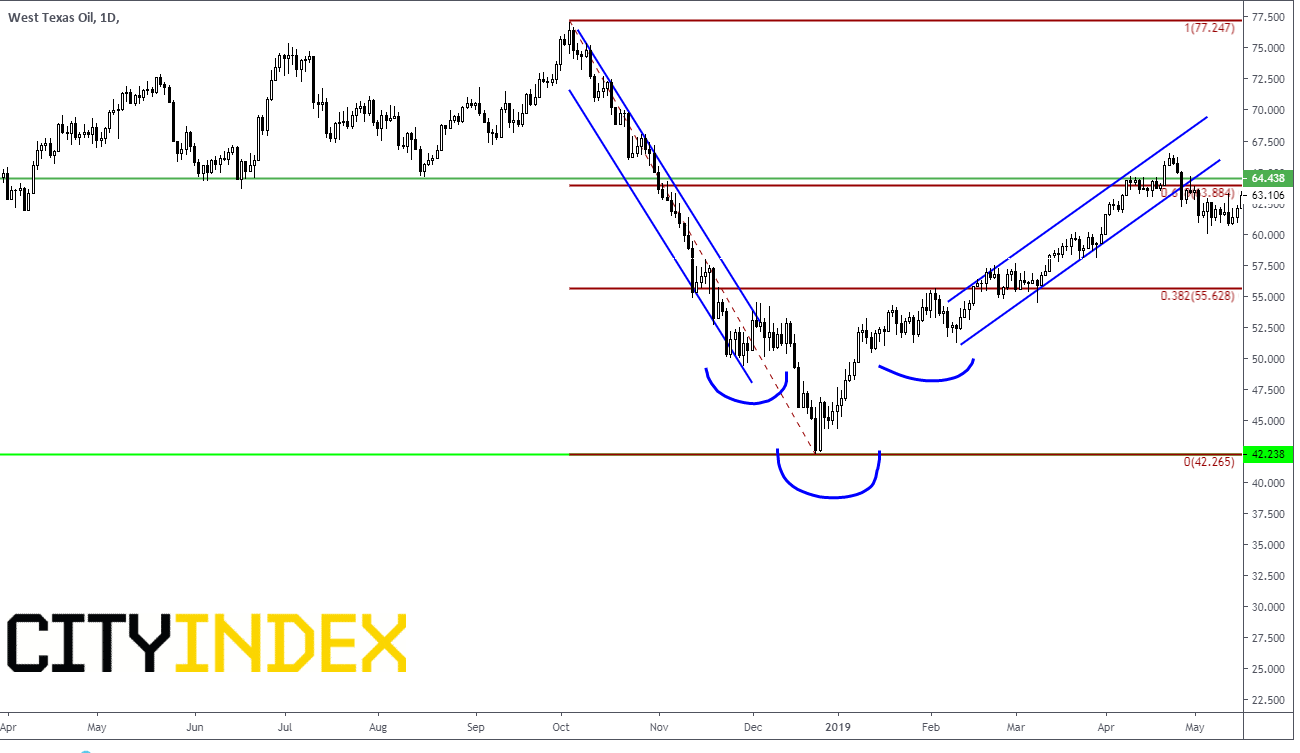
Fall of 2018, WTI Crude Oil
- Traded lower in a channel from near $77.50 to near $55.00
- Put in a head and shoulders REVERSAL bottom down to $42.23
- Stalled at the neckline of the 32.8% retracement of the entire move lower, near $55.00
- Broke the neckline at roughly $55.00.
- Traded higher within a channel to the 61.8% retracement of the previous move, and horizontal resistance, near $64.00.
Source: Tradingview, City Index
Summer of 2019, Yield Curve
- Traded lower in a channel from near 0.25 down to 0.00
- Currently putting in the right shoulder of a possible head and shoulders REVERSAL bottom down near -0.05.
- Stalling at neckline at 0.041%
- Bidding up towards the 38.2% retracement level of the entire move lower, near 0.086.
- If the 38.2% retracement level gets taken out, the yield curve could bid up to the 61.8% retracement of the previous move, and horizontal resistance, near 0.15/0.17
Could the current yield curve follow the same pattern as crude did in the fall of 2018? Maybe. But planning a trade and being ready for the possible outcomes are just as important as executing the trade!
An inverted yield curve is said to be indicative of a recession. Why? Because the last 7 recessions were all preceded by an inverted yield curve. The yield curve we are referencing is the difference between the 10-year yield and the 2-year yield. Indeed, toward the end of August this yield curve did go briefly into negative territory for a few days. Does that mean a recession is ahead? Only time will tell. However, looking at today, we put in a bullish engulfing candle on a daily timeframe (in positive territory).
Source: Tradingview, FOREX.com
The main reason for the bid was that the back end (longer term) bonds sold off at a faster rate than the front end (shorter term) bonds.
Source: Tradingview, FOREX.com
Bonds and yields are inversely related. Therefore, yields rose faster in the back end than in the front end causing the yield curve to rise.
Will the yield curve turn negative again soon? Obviously, there is no way to tell, but let’s look at another instrument with a similar pattern and see what happened:
Source: Tradingview, FOREX.com
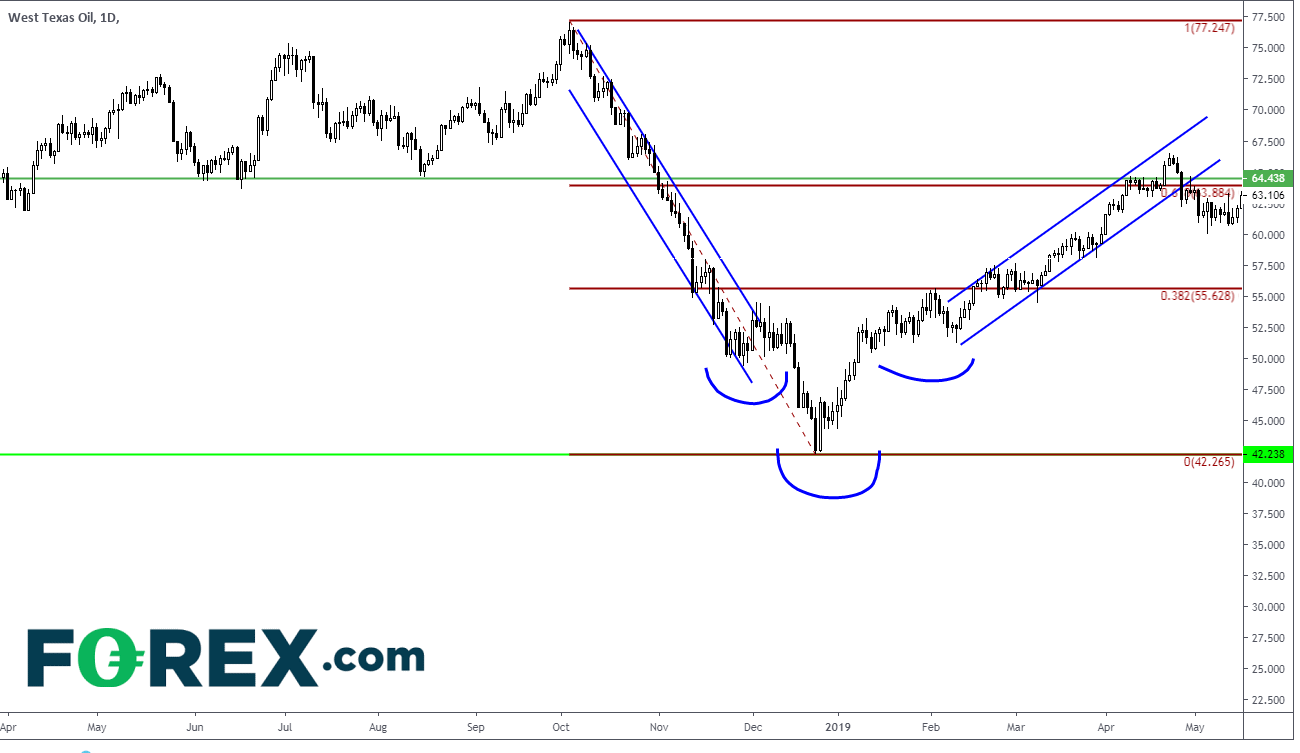
Fall of 2018, WTI Crude Oil
- Traded lower in a channel from near $77.50 to near $55.00
- Put in a head and shoulders REVERSAL bottom down to $42.23
- Stalled at the neckline of the 32.8% retracement of the entire move lower, near $55.00
- Broke the neckline at roughly $55.00.
- Traded higher within a channel to the 61.8% retracement of the previous move, and horizontal resistance, near $64.00.
Source: Tradingview, FOREX.com
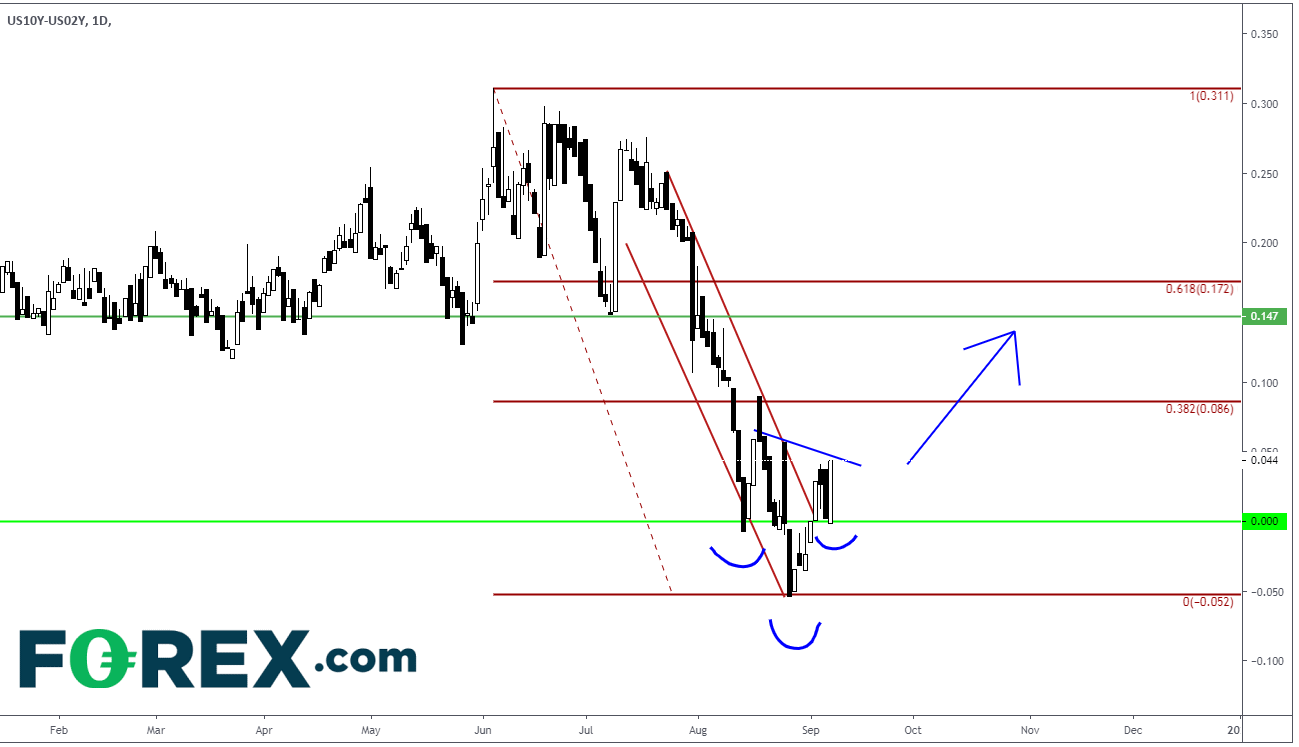
Summer of 2019, Yield Curve
- Traded lower in a channel from near 0.25 down to 0.00
- Currently putting in the right shoulder of a possible head and shoulders REVERSAL bottom down near -0.05.
- Stalling at neckline at 0.041%
- Bidding up towards the 38.2% retracement level of the entire move lower, near 0.086.
- If the 38.2% retracement level gets taken out, the yield curve could bid up to the 61.8% retracement of the previous move, and horizontal resistance, near 0.15/0.17
Could the current yield curve follow the same pattern as crude did in the fall of 2018? Maybe. But planning a trade and being ready for the possible outcomes are just as important as executing the trade!
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

GBP/USD forecast: US dollar surges as bonds implode
The US dollar continued to press higher deep into the European session, supported by the slump in the bond markets as yields broke out across the curve. Following the recent hawkish Fed rate hike, yield spreads between the US and the rest of the world has continually increased, and that motion continued today, helped in part by some forecast-beating US macro data and hawkish Fed commentary.


Gold Analysis: Rising Yields and Dollar Strength Weigh on XAU/USD
The trading week continues, and for now gold remains under notable pressure in the short term. This can be seen in the performance of XAU/USD over the last three trading sessions, where the metal has declined by more than 2.00%, bringing a bearish bias back into focus after it had lost momentum in recent weeks.

Wall Street Forecast: DJIA rises on hawkish Fed expectations & rising yields
U.S. stocks are opening lower on Wednesday, pressured by higher crude oil prices and rising government bond yields, as investors await further developments from negotiations in the Middle East and ahead of a key U.S.-China summit.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.