

DAX at Key Level; Alibaba Surges, Japan Tech Slumps
Markets opened September mixed. US inflation risks remain sticky, while weak consumer sentiment and PMI data weigh on the Fed outlook. Japan’s tech-heavy Nikkei dropped sharply on chip sector losses, while Alibaba surged in Hong Kong on new AI chip development. In Europe, inflation was mixed, with Germany seeing a slight rise. The DAX remains stuck below resistance, signaling fading bullish momentum unless bulls reclaim 24,300.
Share this:
1. Market Holidays
- USA: Markets closed for Labor Day.
- Canada: Markets also closed for Labor Day.
2. US Market Recap (Friday)
- Equities:
- US stocks closed lower.
- Nasdaq underperformed due to tech weakness.
- Sectors:
- Losses: Tech, Consumer Discretionary.
- Gains: Consumer Staples, Health Care.
- Data Highlights:
- PCE inflation came in line with expectations, but “supercore” measure rose for a third consecutive month → concerns about sticky inflation amid tariffs.
- Chicago PMI: Fell to 41.5 (vs. 47.1 prior), well below forecasts, signaling contraction.
- Trade deficit: Widened due to higher imports.
- University of Michigan Sentiment (final, Aug): Revised down to 58.2 (from 61.7), expectations component weakened.
- Inflation expectations: Revised lower.
- Market Impact:
- Fed expectations unchanged—focus remains on August jobs report (due Friday).
- Short-term Treasury yields and the US dollar eased after weak data.
3. Japan: Market & Economy
- Nikkei 225:
- Dropped 2%+ to a 3-week low, driven by heavy selling in chip-related stocks.
- Major contributors:
- Advantest (chip-testing/Nvidia supplier) plunged 9%, dragging 280 points off the Nikkei.
- SoftBank Group fell 6%, alongside losses in Disco, Socionext, Furukawa Electric.
- Topix Index: Fell only 0.8%, showing the sell-off was concentrated in tech.
- Economic Data:
- Industrial production (July): -1.6% MoM (worse than expected).
- Auto sector: -6.7%, hurt by new US tariffs.
- Retail sales: -1.6%, missing forecasts.
- Inflation (Tokyo, Aug): Slowed to 2.6%, largely due to energy subsidies. Core inflation (ex-food & energy) held at 3.0%.
- BoJ Outlook: Governor Ueda sees scope for further rate hikes as wages rise and labor market stays tight.
- Sectoral Trends:
- Export industries pressured by tariffs.
- Domestic demand: Supported by higher wages, benefiting services and banks.
4. China & Alibaba
- Alibaba Stock Surge:
- Shares jumped ~19% in Hong Kong on cloud and semiconductor optimism.
- New Chip Development:
- Alibaba unveiled a new AI chip, more advanced than prior models, aiming to reduce reliance on US semiconductors restricted by export bans.
- Limitations: Designed for running AI applications, not training large AI models (where Nvidia remains dominant).
- Competitive Context: Raises competitive concerns for Nvidia, while highlighting China’s drive for AI self-sufficiency.
5. Europe & Inflation
- Germany (Aug CPI):
- Rose to 2.2% YoY (vs. 2.0% prior months).
- Food prices: +2.5%.
- Energy prices: -2.7%.
- Core inflation: Steady at 2.7% for the third month.
- Services: +3.1%.
- Other Countries:
- France: Inflation eased slightly.
- Italy & Spain: Unchanged from prior month.
- Eurozone Outlook:
- Analysts expect August inflation to rise modestly to 2.1%.
- ECB likely to remain cautious; markets price only ~35% chance of another cut by year-end.
6. DAX Technical Analysis 4 hours
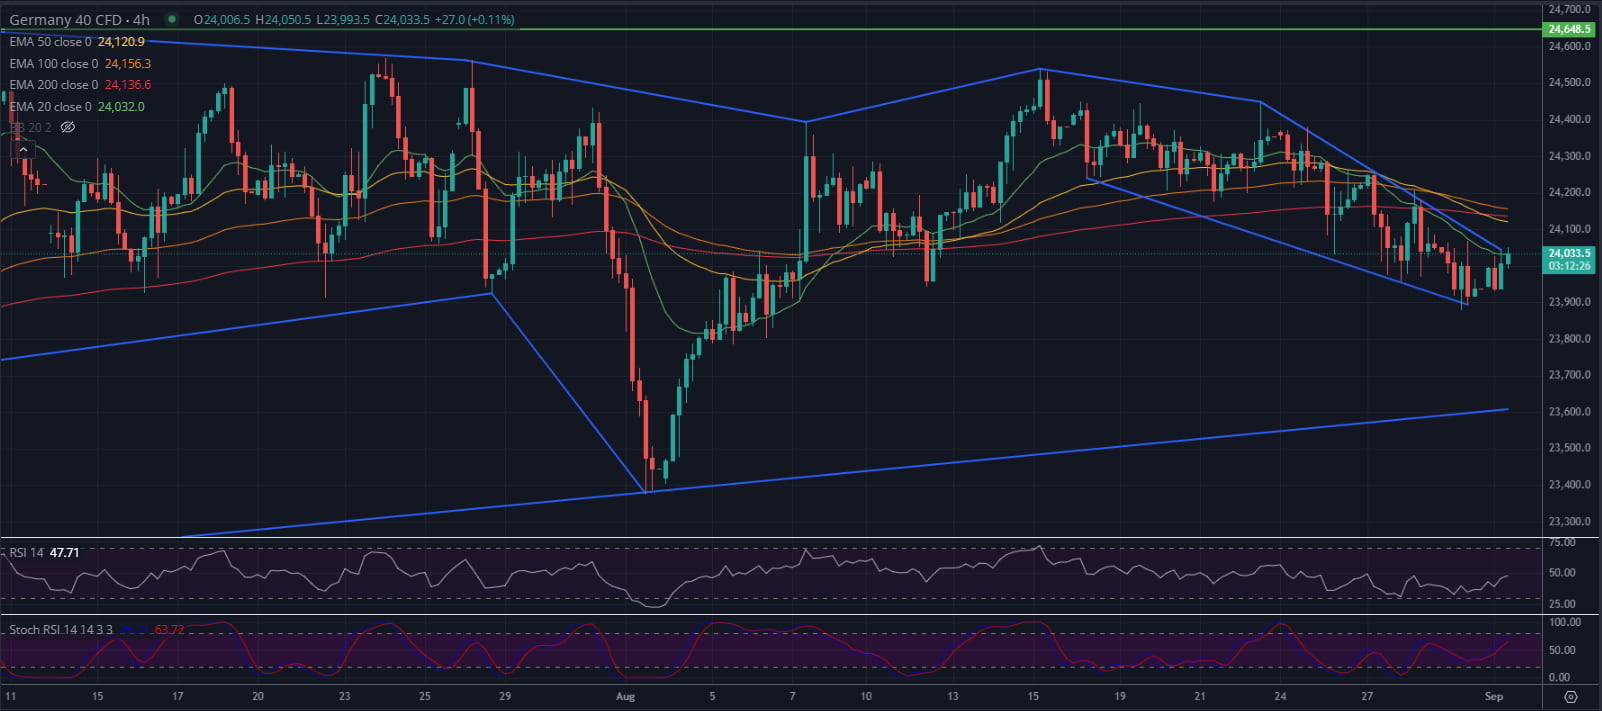
The Germany 40 (DAX) index remains within a broad ascending channel, but price action has grown increasingly compressed. A series of lower highs and sideways consolidation beneath the 50/100/200 EMAs points to fading bullish momentum. Price has also formed a clear descending structure within the larger uptrend, and while the recent bounce off channel support near 23,600 provided temporary relief, it’s now stalling again near 24,150–24,200 resistance. The RSI remains below 50, and the Stochastic RSI has just curled from overbought, suggesting upside may be limited in the immediate term.
For now, the bias is neutral-to-bearish in the short term, unless bulls can regain the 24,300–24,450 area. A break above this would expose the 24,648 highs, while failure to do so and a breakdown below 23,900 would likely open the door for another leg down toward 23,500 or even 23,200. With moving averages flattening out and price chopping within a narrowing structure, patience is warranted — but bulls need to act quickly to avoid further deterioration.
7. Key Takeaways
- US: Sticky inflation risks but weak business activity & consumer sentiment. Fed focus remains on jobs data.
- Japan: Tech stocks slump and weak industrial data raise concerns, though wages and services offset some drag.
- China: Alibaba signals ambition to fill the AI hardware gap left by Nvidia amid export controls.
- Europe: Inflation picture mixed; ECB still cautious, with limited scope for further easing.
- Global Markets: Tech sector remains the dominant driver of volatility at the start of September.

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Bears Lose Their Grip Ahead of NFP, USD/JPY Vols Elevated
US dollar selling pressure fades ahead of NFP as Fed hike bets retreat. USD/JPY stands out with a 141-pip implied move as FX volatility takes centre stage.

Gold Reclaims $4,000, Bulls Eye Reversal with Seasonality Tailwind
Gold futures rebound above $4,000 as falling US yields, improving sentiment and bullish seasonality raise hopes of a significant reversal.

AUD/USD Remains Vulnerable Despite US Dollar Weakness Amid Midterms
AUD/USD struggles despite a weaker US dollar and falling Treasury yields, as Democratic sweep expectations fuel volatility and Wall Street risk aversion.
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.