



AUD outlook: RBA’s hawkish tone challenges easing expectations
The RBA held rates at 3.6%, but its updated forecasts suggest the easing cycle may already be done. Are traders underestimating the hawkish tone?
Share this:
- RBA left cash rate at 3.6%, as expected
- Trimmed mean inflation not back to 2.5% before 2027
- Unemployment forecast steady at 4.4%, growth outlook solid
- Swaps trim rate cut odds
Summary
The RBA’s November decision was a hold, but not a dovish one. Updated forecasts show inflation staying above target for years, unemployment barely rising, and growth holding firm despite fewer cuts than previously assumed. Markets have pared back easing expectations, and AUD/USD is probing key technical levels. With momentum signals neutral, price action will dictate the next move.
RBA Cash Rate May Have Bottomed
The RBA kept Australia’s cash rate steady at 3.6% in November, as widely expected by markets and economists. However, despite suggesting last week’s hot Q3 inflation report was in part driven by temporary factors, it does not see underlying inflation returning to the midpoint of its 2–3% target band by the end of 2027, pointing to the potential they may have already delivered the last rate cut for the cycle.
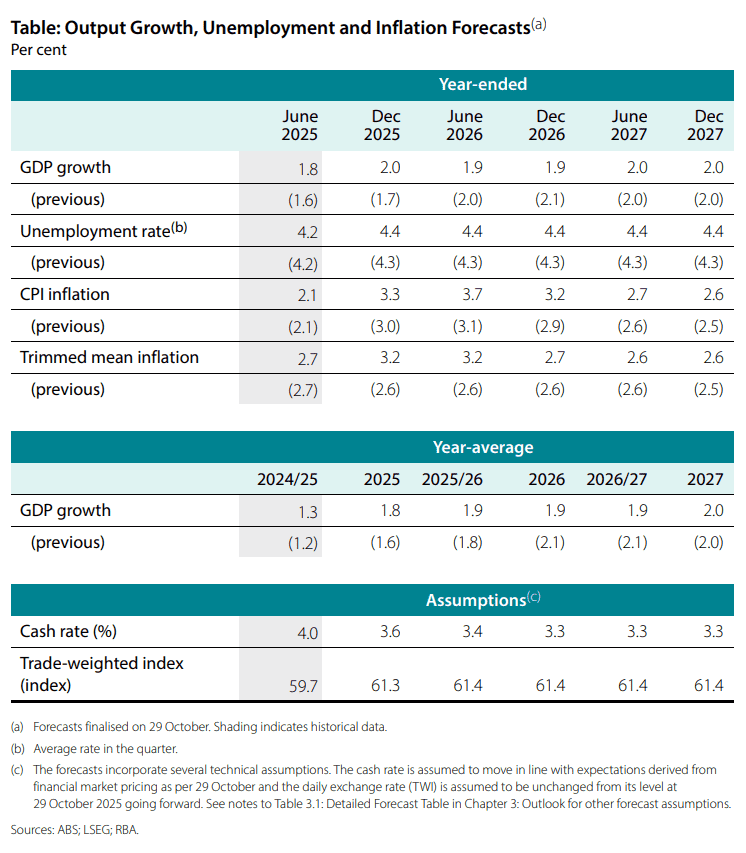
As this meeting coincides with the release of updated economic forecasts from the RBA, a lot of its commentary was devoted to the changes to the outlook for GDP growth, unemployment and inflation. The new update is found below.
Source: RBA
On the hotter-than-expected Q3 consumer price inflation report released last week, the RBA described it as “materially higher” than its prior forecasts. However, it noted “some of the increase in underlying inflation…was due to temporary factors.” Initially, markets took that line as being dovish, but that’s where the bank’s dovishness ended. For a start, despite pointing to temporary factors partly driving the acceleration, its updated trimmed mean inflation profile does not have it returning to the 2.5% target before the end of 2027, deviating from the view presented three months earlier. And that was with two fewer rate cuts than what were factored in previously, a substantial hawkish recalibration that could have seen the RBA easily forecast it returning to the midpoint or even lower.
The RBA also refrained from forecasting a material increase in unemployment despite the shallower rate cut profile, pinning it at 4.4% out to the end of 2027, a tenth lower than the 4.5% level it sits today. Even its growth forecasts remained solid, with near-term expectations revised higher with only minor changes elsewhere. The RBA could have signalled growth risks from continued slightly restrictive policy settings but didn’t. That’s not dovish.


A Slightly Hawkish Hold
Considering trimmed mean inflation is not seen returning to the midpoint over the forecast horizon, and with little weakness seen in the labour market and economy, it hints the RBA may have already delivered its last rate cut for the cycle even though one more was incorporated into the latest forecasts. That view is bolstered by its acknowledgement that “it will take some time to see the full effects of earlier cash rate reductions.” It also repeated that labour market conditions “remain a little tight” with the recovery in household consumption “ongoing” and the housing market “continuing to strengthen.”
Given those statements, and considering what it could have forecast with the shallower rate cut profile, the broad assessment is this was a marginally hawkish hold from the RBA relative to market pricing.
Source: Bloomberg
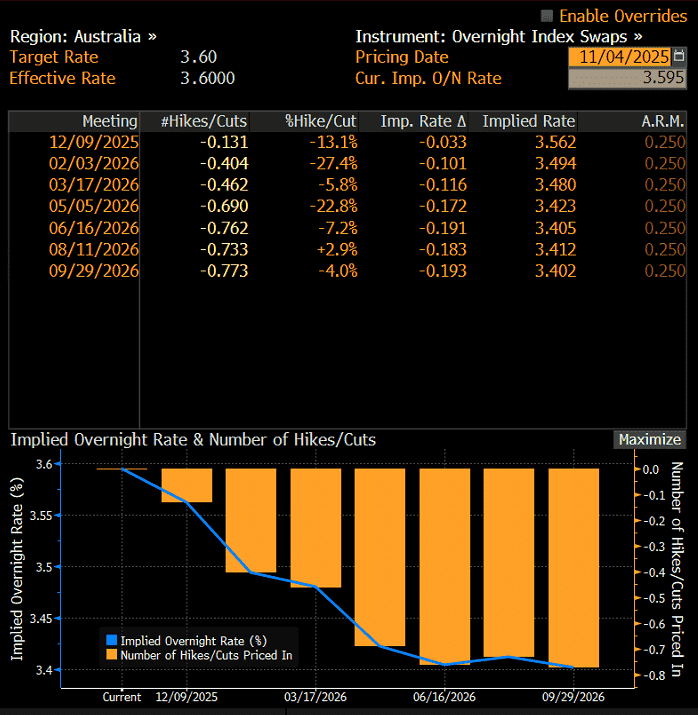
Swaps agree at this stage with a minor hawkish recalibration across the AUD OIS curve, with a 25bp cut by September next year now priced at 77%, down from a touch over 80% beforehand.
AUD/USD Bounces from Support
Source: TradingView
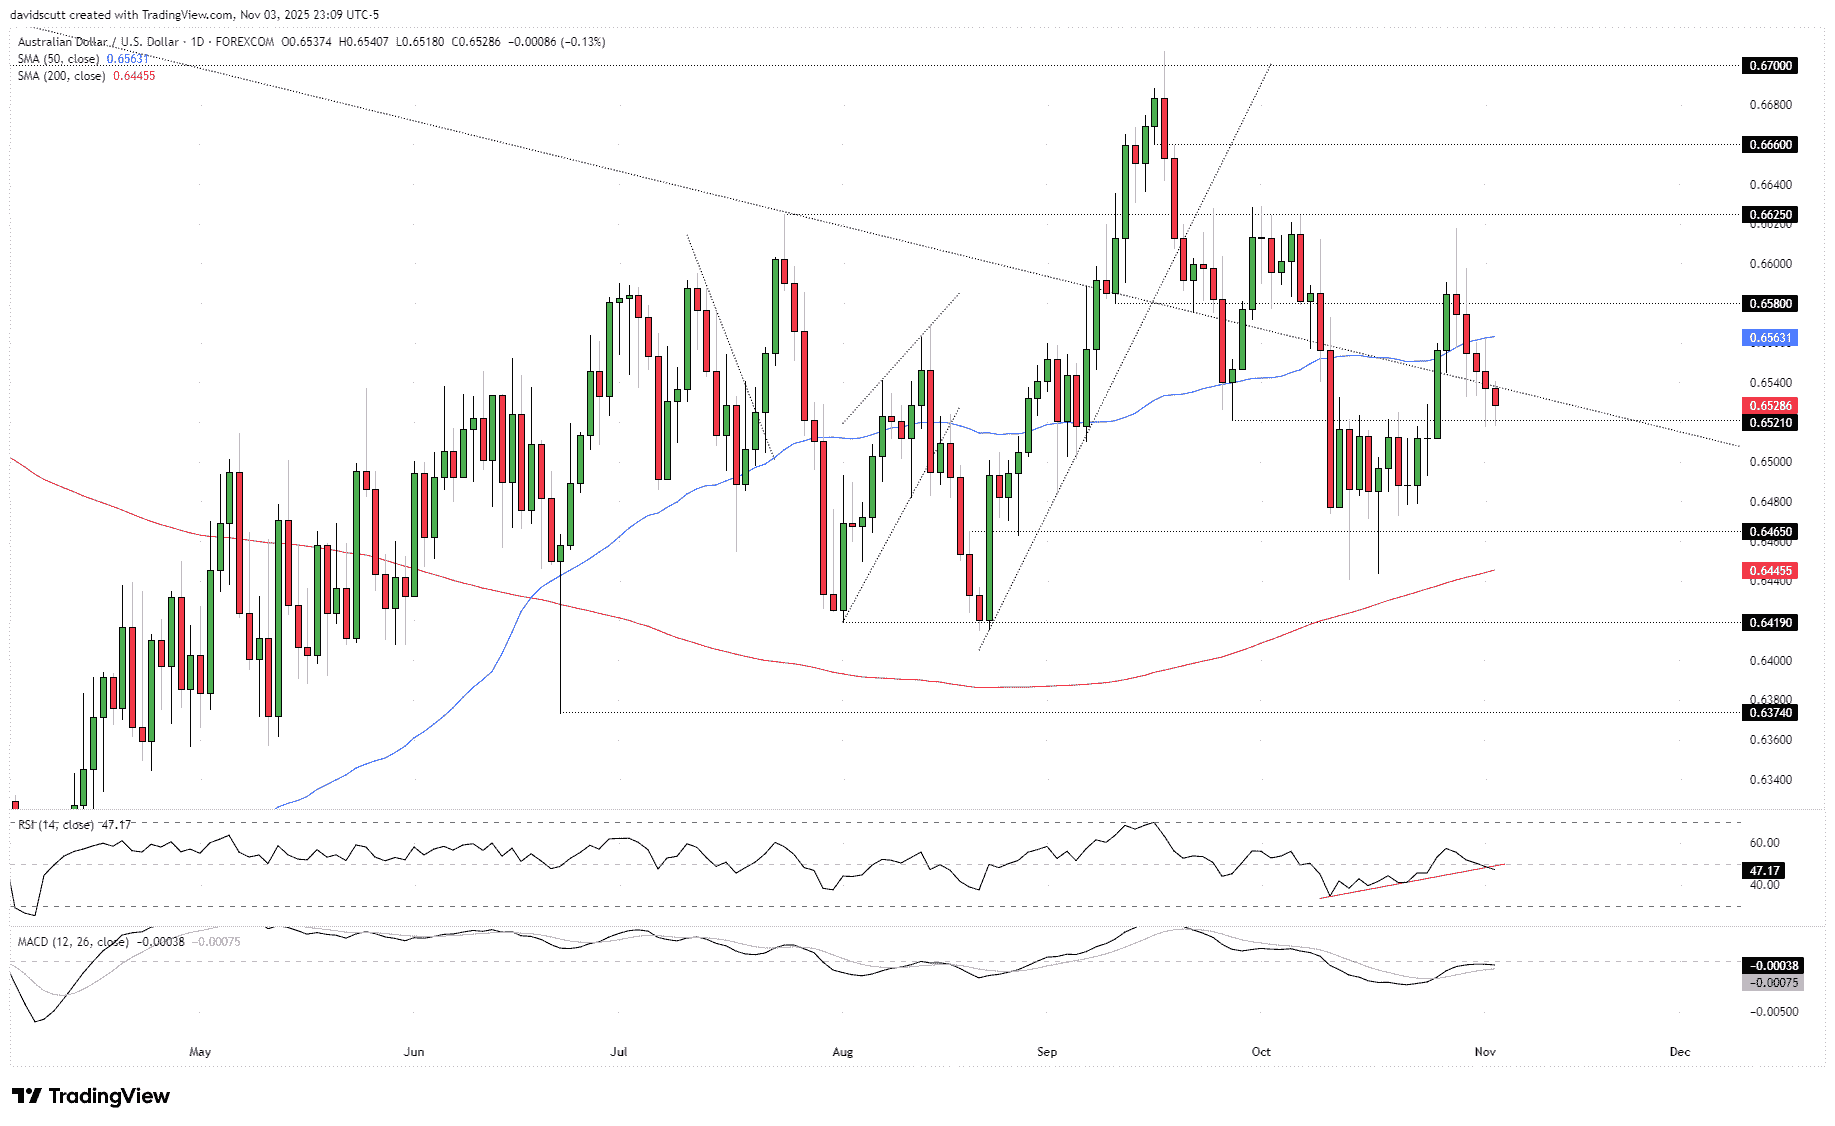
After testing support at .6521 immediately following the RBA decision, AUD/USD has bounced to trade at .6529. Topside levels to consider when assessing setups include the 2021 downtrend around 10 pips higher, the 50-day moving average and .6625 resistance. Beneath .6521 support, .6465 and 200-day moving average are the levels to watch.
There are signs emerging the retreat in bearish momentum seen in recent weeks may be starting to turn again, although the overall message from RSI (14) and MACD is neutral when it comes to directional bias. Putting more emphasis on price signals is therefore warranted.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.