



AUD/USD weekly outlook: US CPI and Aussie Jobs in Focus
AUD/USD eyes employment and US inflation data after the RBA wrongfoots markets with a cautious hold and keeps rate cut timing uncertain.
Share this:
It’s been a while since I was on the wrong side of an RBA decision, but last week they decided to hold the cash rate at 3.85% instead of delivering the 25bp cut I had envisaged. They likely want to wait for the quarterly CPI figures on 30 July, which I suspect will be soft enough to justify a rate cut—something the monthly inflation figures have already hinted at.
But given the typically cautious tone struck by the RBA in their statement, I doubt they’ll deliver much of a dovish cut anyway. That will keep traders guessing as to whether they really will deliver another two rate cuts in the second half. Personally, I wouldn’t be surprised if they only deliver another 50bp of cuts this year, taking the cash rate down to 3.35%. And if a third were to arrive, perhaps they’ll opt for a 15bp move to bring the cash rate back in line with the traditional quarter-point scale.
View related analysis:
View related analysis:

Chart prepared by Matt Simpson, source: LSEG
Australian Employment Report in Focus as RBA Doves Await Cracks
Australia’s robust employment situation has of course been a supporting feature behind the RBA’s higher cash rate. The unemployment rate remained at a healthy 4.1% in May, though the participation rate may have topped in recent months. 41.2k part-time jobs were lost in May (fastest decline in 14 months) was effectively offset the 38.7k full-time rise, making the -2.5k loss of jobs a minor issue. Still, should we see the cracks widen it allows room for RBA doves to breath. June employment figures therefore warrant a look on Thursday.

Chart prepared by Matt Simpson, source: LSEG
Key US Inflation Data Could Sway Fed’s September Rate Cut Odds
There’s no shortage of FOMC speakers this week, and markets have plenty of relevant data to digest. Fed Chair Jerome Powell recently suggested the inflationary impact of Trump’s tariffs could begin to emerge during the summer months — making June’s CPI release on Tuesday particularly important for the US dollar outlook.
If CPI data comes in softer than expected, and is accompanied by weaker retail sales and producer prices, traders may increase their bets on a September rate cut. Current pricing implies ~60% odds of a cut, but that could rise above 70% if inflation trends continue to moderate. It could also weigh on the US dollar as traders refocus their attention to Fed cuts, assuming Trump’s tariffs return to the rear-view mirror as deals are made.
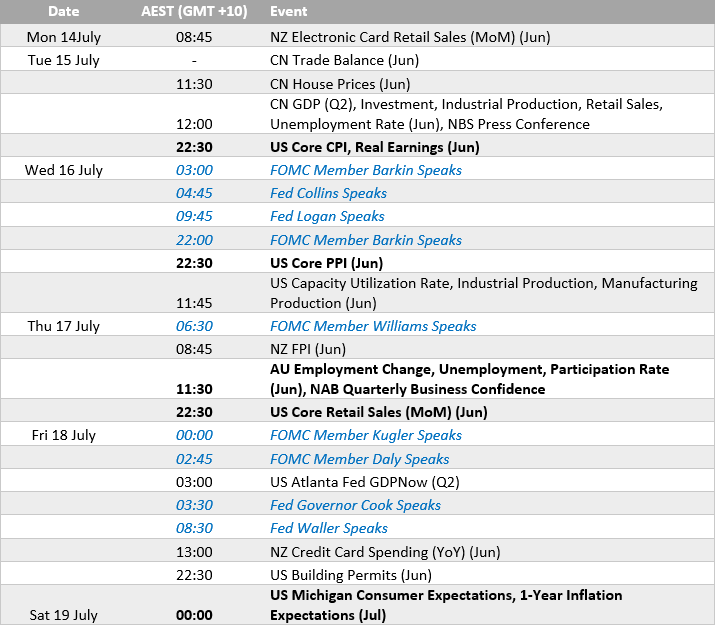
Chart prepared by Matt Simpson, source: LSEG
AUD/USD Correlations Suggest Bullish Bias, Unless Aussie Jobs Disappoint
Correlations between AUD/USD and usual suspects like NZD, CNY and DXY have weakened post-RBA, but the Aussie has held up. AUD/NZD surged 1.3% last week—the strongest since September—and AUD/USD booked a third straight weekly gain. Unless Thursday’s jobs data underwhelms, AUD/USD dips may be shallow and short-lived.
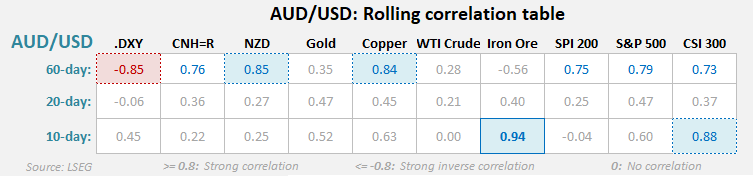
Chart prepared by Matt Simpson, source: LSEG
AUD/USD Futures: COT Report Shows Bears Add Shorts Ahead of Jobs Risk
• Net-short exposure by large speculators rose to a 15-week high of 74.3k contracts
• Asset managers’ net-short positions also hit a 15-week high at 38.2k contracts
• Gross-longs rose by 5k contracts while gross-shorts fell by -2.2k, showing mixed positioning bias
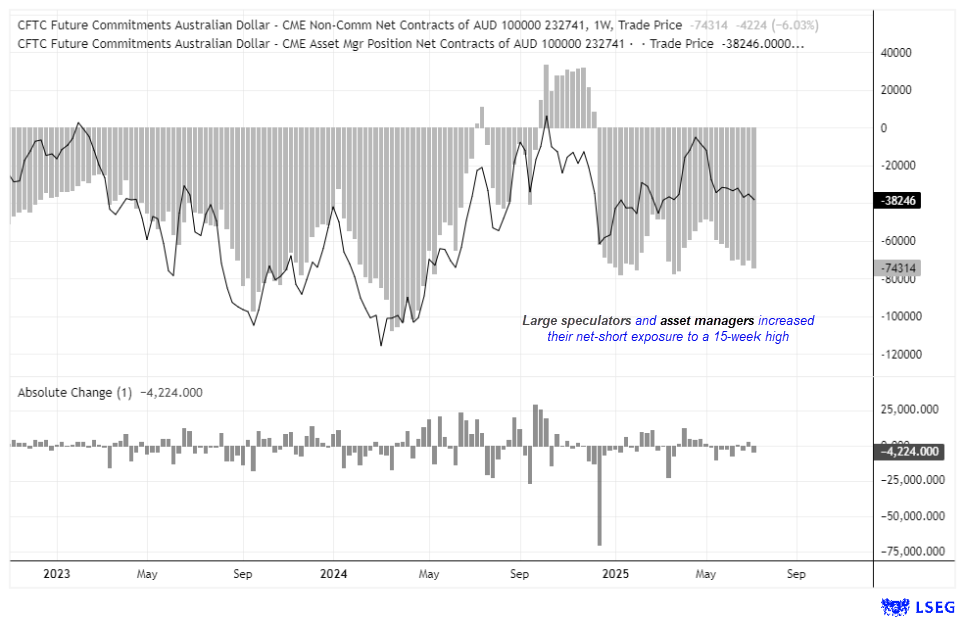
Chart prepared by Matt Simpson, source: LSEG
AUD/USD Technical Analysis: Bulls Defend 65c as Short-Sellers Get Squeezed
The Australian dollar has continued to grind higher for a third week, with bears being lulled into futile shorts before prices whip higher once again. It seems that 65c is an important support area for bulls, given it sits near the high-volume node of the choppy rise since late April, and close to last week’s low.
Therefore, any dips towards 65c could entice fresh long bets—unless a compellingly bearish case arises for the ‘battler’. That seems unlikely from the RBA, but more plausible from the Fed.
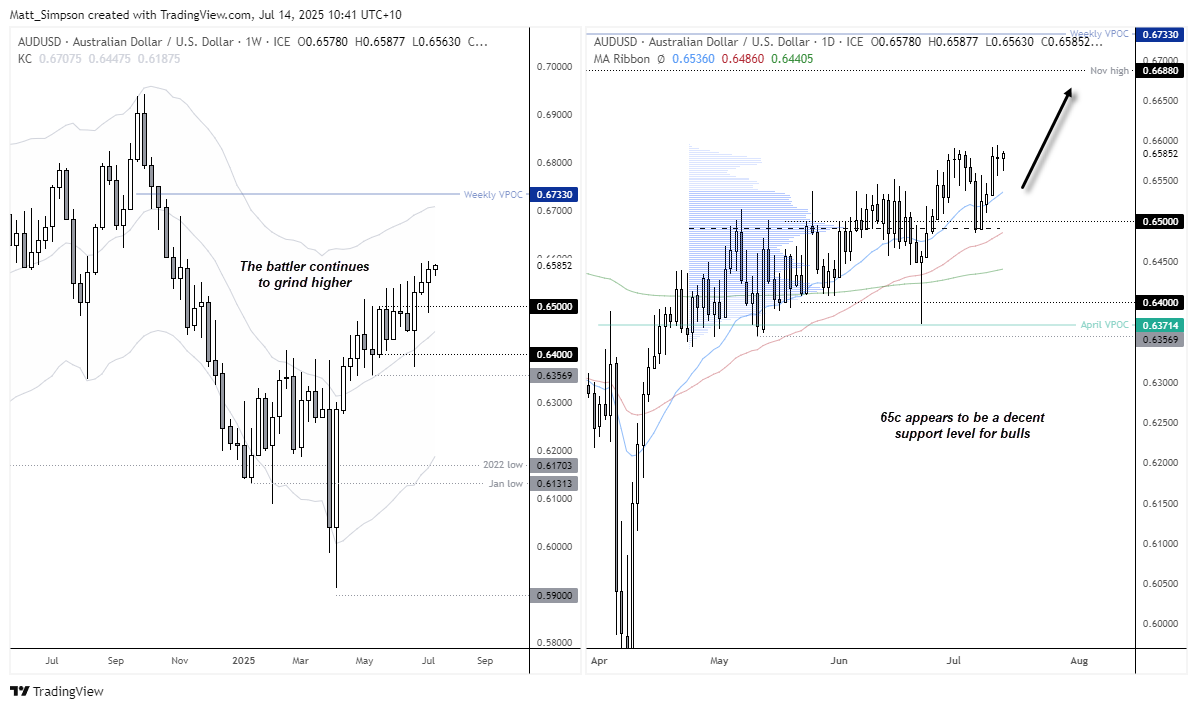
Analysis by Matt Simpson, source: TradingView
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.


AUD/USD Crushed Ahead of Jobs Report as US Dollar, Yields Surge
AUD/USD slumps towards 70c as surging US yields and a stronger dollar overshadow Australian jobs data and the RBA outlook.

USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.