


DAX at Key Level; Alibaba Surges, Japan Tech Slumps
Markets opened September mixed. US inflation risks remain sticky, while weak consumer sentiment and PMI data weigh on the Fed outlook. Japan’s tech-heavy Nikkei dropped sharply on chip sector losses, while Alibaba surged in Hong Kong on new AI chip development. In Europe, inflation was mixed, with Germany seeing a slight rise. The DAX remains stuck below resistance, signaling fading bullish momentum unless bulls reclaim 24,300.
Share this:
1. Market Holidays
- USA: Markets closed for Labor Day.
- Canada: Markets also closed for Labor Day.
2. US Market Recap (Friday)
- Equities:
- US stocks closed lower.
- Nasdaq underperformed due to tech weakness.
- Sectors:
- Losses: Tech, Consumer Discretionary.
- Gains: Consumer Staples, Health Care.
- Data Highlights:
- PCE inflation came in line with expectations, but “supercore” measure rose for a third consecutive month → concerns about sticky inflation amid tariffs.
- Chicago PMI: Fell to 41.5 (vs. 47.1 prior), well below forecasts, signaling contraction.
- Trade deficit: Widened due to higher imports.
- University of Michigan Sentiment (final, Aug): Revised down to 58.2 (from 61.7), expectations component weakened.
- Inflation expectations: Revised lower.
- Market Impact:
- Fed expectations unchanged—focus remains on August jobs report (due Friday).
- Short-term Treasury yields and the US dollar eased after weak data.
3. Japan: Market & Economy
- Nikkei 225:
- Dropped 2%+ to a 3-week low, driven by heavy selling in chip-related stocks.
- Major contributors:
- Advantest (chip-testing/Nvidia supplier) plunged 9%, dragging 280 points off the Nikkei.
- SoftBank Group fell 6%, alongside losses in Disco, Socionext, Furukawa Electric.
- Topix Index: Fell only 0.8%, showing the sell-off was concentrated in tech.
- Economic Data:
- Industrial production (July): -1.6% MoM (worse than expected).
- Auto sector: -6.7%, hurt by new US tariffs.
- Retail sales: -1.6%, missing forecasts.
- Inflation (Tokyo, Aug): Slowed to 2.6%, largely due to energy subsidies. Core inflation (ex-food & energy) held at 3.0%.
- BoJ Outlook: Governor Ueda sees scope for further rate hikes as wages rise and labor market stays tight.
- Sectoral Trends:
- Export industries pressured by tariffs.
- Domestic demand: Supported by higher wages, benefiting services and banks.
4. China & Alibaba
- Alibaba Stock Surge:
- Shares jumped ~19% in Hong Kong on cloud and semiconductor optimism.
- New Chip Development:
- Alibaba unveiled a new AI chip, more advanced than prior models, aiming to reduce reliance on US semiconductors restricted by export bans.
- Limitations: Designed for running AI applications, not training large AI models (where Nvidia remains dominant).
- Competitive Context: Raises competitive concerns for Nvidia, while highlighting China’s drive for AI self-sufficiency.
5. Europe & Inflation
- Germany (Aug CPI):
- Rose to 2.2% YoY (vs. 2.0% prior months).
- Food prices: +2.5%.
- Energy prices: -2.7%.
- Core inflation: Steady at 2.7% for the third month.
- Services: +3.1%.
- Other Countries:
- France: Inflation eased slightly.
- Italy & Spain: Unchanged from prior month.
- Eurozone Outlook:
- Analysts expect August inflation to rise modestly to 2.1%.
- ECB likely to remain cautious; markets price only ~35% chance of another cut by year-end.
6. DAX Technical Analysis 4 hours
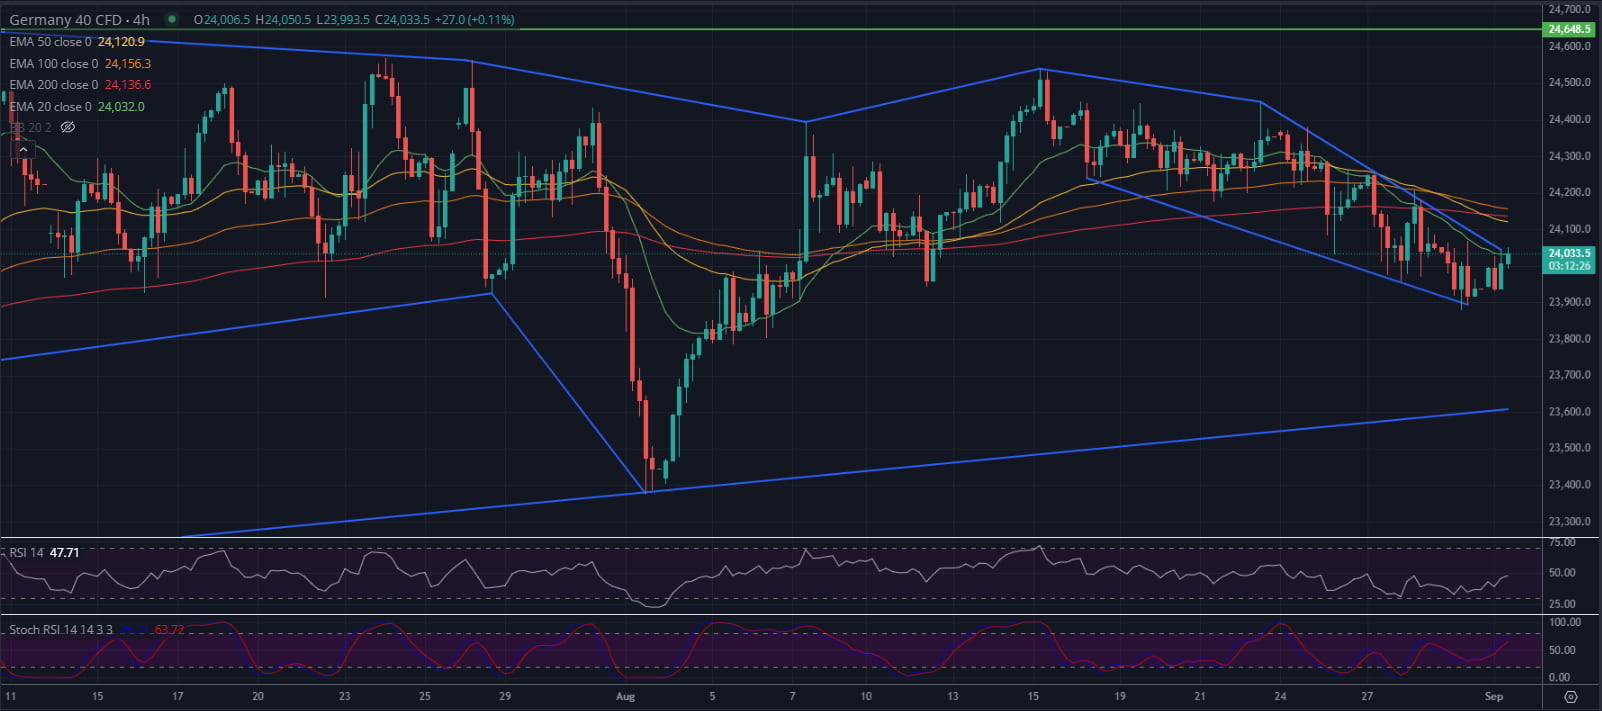
The Germany 40 (DAX) index remains within a broad ascending channel, but price action has grown increasingly compressed. A series of lower highs and sideways consolidation beneath the 50/100/200 EMAs points to fading bullish momentum. Price has also formed a clear descending structure within the larger uptrend, and while the recent bounce off channel support near 23,600 provided temporary relief, it’s now stalling again near 24,150–24,200 resistance. The RSI remains below 50, and the Stochastic RSI has just curled from overbought, suggesting upside may be limited in the immediate term.
For now, the bias is neutral-to-bearish in the short term, unless bulls can regain the 24,300–24,450 area. A break above this would expose the 24,648 highs, while failure to do so and a breakdown below 23,900 would likely open the door for another leg down toward 23,500 or even 23,200. With moving averages flattening out and price chopping within a narrowing structure, patience is warranted — but bulls need to act quickly to avoid further deterioration.
7. Key Takeaways
- US: Sticky inflation risks but weak business activity & consumer sentiment. Fed focus remains on jobs data.
- Japan: Tech stocks slump and weak industrial data raise concerns, though wages and services offset some drag.
- China: Alibaba signals ambition to fill the AI hardware gap left by Nvidia amid export controls.
- Europe: Inflation picture mixed; ECB still cautious, with limited scope for further easing.
- Global Markets: Tech sector remains the dominant driver of volatility at the start of September.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD Crushed Ahead of Jobs Report as US Dollar, Yields Surge
AUD/USD slumps towards 70c as surging US yields and a stronger dollar overshadow Australian jobs data and the RBA outlook.

GBP/USD, DAX Forecast Two trades to watch 220926
GBP/USD struggles as UK government borrowing exceeds forecasts, putting pressure on Healey ahead of the Budget. DAX eases back after yesterday's gains as oil prices and political headwinds rise.

USD/CAD Analysis: Is the Canadian Dollar Running Out of Support?
A new trading week is underway, and the Canadian dollar continues to show signs of weakening momentum. This can be seen in recent USD/CAD price action, with the pair gaining nearly 0.7% over the last four trading sessions.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.