



Easing Optimism Boosts Markets
Investors are taking stock of the gradual reopening of economies whilst oil also picks up on greater fuel demands.
Share this:

Following a late rebound on Wall Street and a rise in Asian stocks overnight, European bourses are heading towards a stronger start on the open. Investors are taking stock of the gradual reopening of economies whilst oil also picks up on greater fuel demands.
Optimism surrounding the gradual easing of lockdown restrictions and the impending economic recovery is outweighing rising US – Chinese tensions, which had dragged on sentiment in trading on Monday.
Italy and Spain are gradually reopening their economies, Germany is moving towards the second phase with large shops set to reopen, joining smaller shops which have already started trading. In the UK, blueprints of how Britain will ease out of lockdown have also been leaked, although more details are expected from Boris Johnson later in the week.
Oil back over $20pb
The rebound in oil has been largely driven by an increase in demand as governments ease lockdown restrictions. Data from the Cushing storage (largest oil storage tank in the world, responsible for 13% of total US storage) showed inventories rose 1.88mb last week, the smallest increase since mid-March and the surest indication that oil demand is slowly picking up.
The rebound in oil has been largely driven by an increase in demand as governments ease lockdown restrictions. Data from the Cushing storage (largest oil storage tank in the world, responsible for 13% of total US storage) showed inventories rose 1.88mb last week, the smallest increase since mid-March and the surest indication that oil demand is slowly picking up.
Whilst April was all about the collapse of demand and approaching storage capacity limits, expect May and June to be about rising demand and rising storage capacity as more oil is consumed. As economies reopen demand will gradually pick up. However, any rapid bounce back is looking highly unlikely, this will be a gradual advance, unless OPEC+ manages to pull together another production cut.
Attention will now turn to tomorrow’s API data and then EIA data, which could well confirm that a gradual recovery is underway.

Attention will now turn to tomorrow’s API data and then EIA data, which could well confirm that a gradual recovery is underway.
Service sector PMI bottom
The pound is pushing higher, snapping a three-day losing streak against the Dollar as the number of coronavirus daily deaths fall to levels last seen at the end of March as the UK awaits further details on the UK’s exit strategy.
Today the service sector PMI is expected to drop to 12.2 in April (final), reflecting a full month of lockdown. The very measures implemented to slow the spread of covid-19 caused services sector demand to evaporate. With the UK economy set to gradually reopen this should represent a bottom. With the market expecting a horrifying number, its unlikely to rock the boat much at these levels. A significantly worse reading (if possible?!) could.
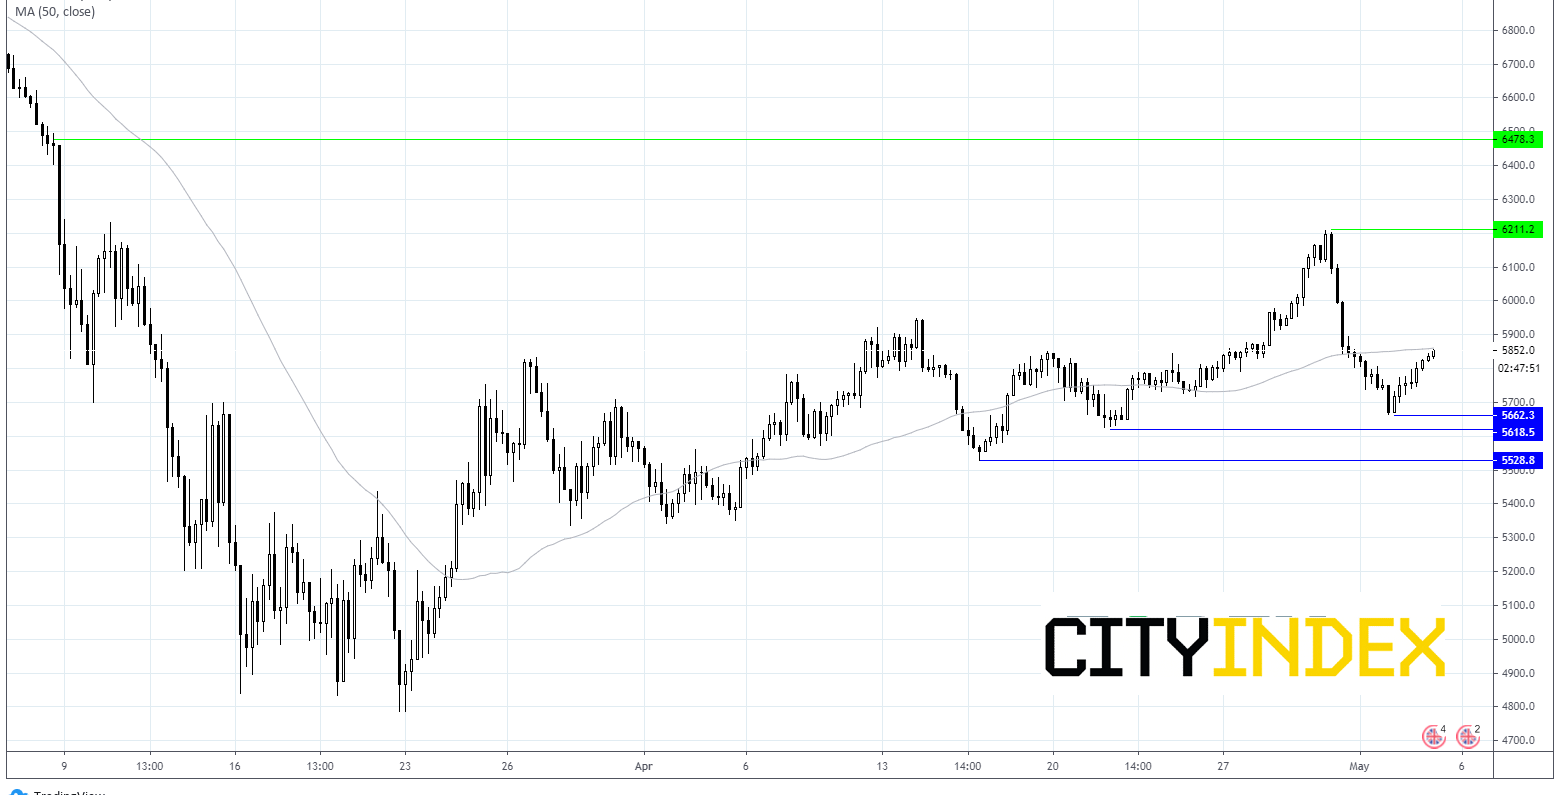
FTSE chart
Following a late rebound on Wall Street and a rise in Asian stocks overnight, European bourses are heading towards a stronger start on the open. Investors are taking stock of the gradual reopening of economies whilst oil also picks up on greater fuel demands.
Optimism surrounding the gradual easing of lockdown restrictions and the impending economic recovery is outweighing rising US – Chinese tensions, which had dragged on sentiment in trading on Monday.
Italy and Spain are gradually reopening their economies, Germany is moving towards the second phase with large shops set to reopen, joining smaller shops which have already started trading. In the UK, blueprints of how Britain will ease out of lockdown have also been leaked, although more details are expected from Boris Johnson later in the week.
Oil back over $20pb
The rebound in oil has been largely driven by an increase in demand as governments ease lockdown restrictions. Data from the Cushing storage (largest oil storage tank in the world, responsible for 13% of total US storage) showed inventories rose 1.88mb last week, the smallest increase since mid-March and the surest indication that oil demand is slowly picking up.
The rebound in oil has been largely driven by an increase in demand as governments ease lockdown restrictions. Data from the Cushing storage (largest oil storage tank in the world, responsible for 13% of total US storage) showed inventories rose 1.88mb last week, the smallest increase since mid-March and the surest indication that oil demand is slowly picking up.
Whilst April was all about the collapse of demand and approaching storage capacity limits, expect May and June to be about rising demand and rising storage capacity as more oil is consumed. As economies reopen demand will gradually pick up. However, any rapid bounce back is looking highly unlikely, this will be a gradual advance, unless OPEC+ manages to pull together another production cut.
Attention will now turn to tomorrow’s API data and then EIA data, which could well confirm that a gradual recovery is underway.
Attention will now turn to tomorrow’s API data and then EIA data, which could well confirm that a gradual recovery is underway.
Service sector PMI bottom
The pound is pushing higher, snapping a three-day losing streak against the Dollar as the number of coronavirus daily deaths fall to levels last seen at the end of March as the UK awaits further details on the UK’s exit strategy.
Today the service sector PMI is expected to drop to 12.2 in April (final), reflecting a full month of lockdown. The very measures implemented to slow the spread of covid-19 caused services sector demand to evaporate. With the UK economy set to gradually reopen this should represent a bottom. With the market expecting a horrifying number, its unlikely to rock the boat much at these levels. A significantly worse reading (if possible?!) could.
FTSE chart



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.


RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.