

EUR/USD forecast: Rising energy prices strengthen US dollar as downside risks for euro grows
Escalating tensions between the US and Iran have once again pushed crude oil prices higher, providing further support for the US dollar. The greenback has performed particularly well against lower-yielding currencies, such as the Swiss franc, as investors seek both safety and higher returns while reassessing the inflation outlook. Although the euro has held up better than some of its peers, thanks to expectations that the European Central Bank may have to tighten its policy further, the balance of risks remain for the downside.
Share this:
Escalating tensions between the US and Iran have once again pushed crude oil prices higher, providing further support for the US dollar. The greenback has performed particularly well against lower-yielding currencies, such as the Swiss franc, as investors seek both safety and higher returns while reassessing the inflation outlook. Although the euro has held up better than some of its peers, thanks to expectations that the European Central Bank may have to tighten its policy further, the balance of risks remain for the downside. If oil prices continue climbing, energy costs are likely to become a more powerful driver of FX markets than interest rate differentials, leaving the EUR/USD forecast increasingly bearish.
Oil-driven inflation fears revive the dollar
Following that weak US jobs report, the dollar lost some momentum but it had now regained it as markets begin to price in the growing risk that renewed disruptions in the Gulf could tighten global energy supplies. Brent crude has climbed to around $87 a barrel, but current pricing still suggests investors are not fully convinced a major supply shock is imminent.
That leaves scope for both oil and the dollar to extend their gains should tensions escalate further. If you recall, oil prices reached north of $110 at the height of the crisis a few months ago, and spent majority of that time around the $100 level.
But unlike earlier in the year, the Fed is now not offering any forward guidance following its hawkish shift in June. That has encouraged markets to speculate more freely about additional policy tightening, with traders now assigning a meaningful probability to a rate increase before the end of the summer.
Warch or CPI unlikely to cause fireworks
Attention now turns to Chair Kevin Warsh’s testimony before Congress, although he is expected to maintain his preference for avoiding strong policy signals. Several other Fed officials are also due to speak, while the latest US inflation figures could reinforce expectations that policymakers may have to tighten policy. Even if headline inflation eases because of earlier declines in energy prices, sticky core inflation is unlikely to provide much reassurance. What’s more, the latest upsurge in oil prices will shift inflation expectations higher for the coming months.
So, markets may not pay too much attention to a small miss in CPI, if we get one. Anyway, the headline figure is expected to print 3.8% year-on-year for June, down from 4.2% in May. Core CPI is seen easing modestly to 2.8% from 2.9%.
Euro supported by yields, but energy remains a headwind
The euro has avoided sharper losses largely because eurozone bond yields have risen alongside US Treasury yields, preventing a significant widening in transatlantic rate differentials.
Markets continue to expect further ECB tightening this year, although policymakers have adopted a more cautious tone recently. That leaves limited room for expectations to become significantly more hawkish from here.
Meanwhile, the outlook for Europe is becoming increasingly complicated by higher energy prices. Rising natural gas costs pose a much greater challenge for the eurozone economy than for the United States. Should Brent crude climb towards the $100 area, the negative impact on Europe’s economy could easily outweigh any support generated by higher ECB rates, increasing the likelihood of a deeper EUR/USD decline.
Technical EUR/USD forecast: Bearish pattern points to further weakness
The technical picture also continues to favour the bears. The EUR/USD has broken out of bear flag formation, strengthening the case for another leg lower, initially exposing the recent swing low around 1.1324.
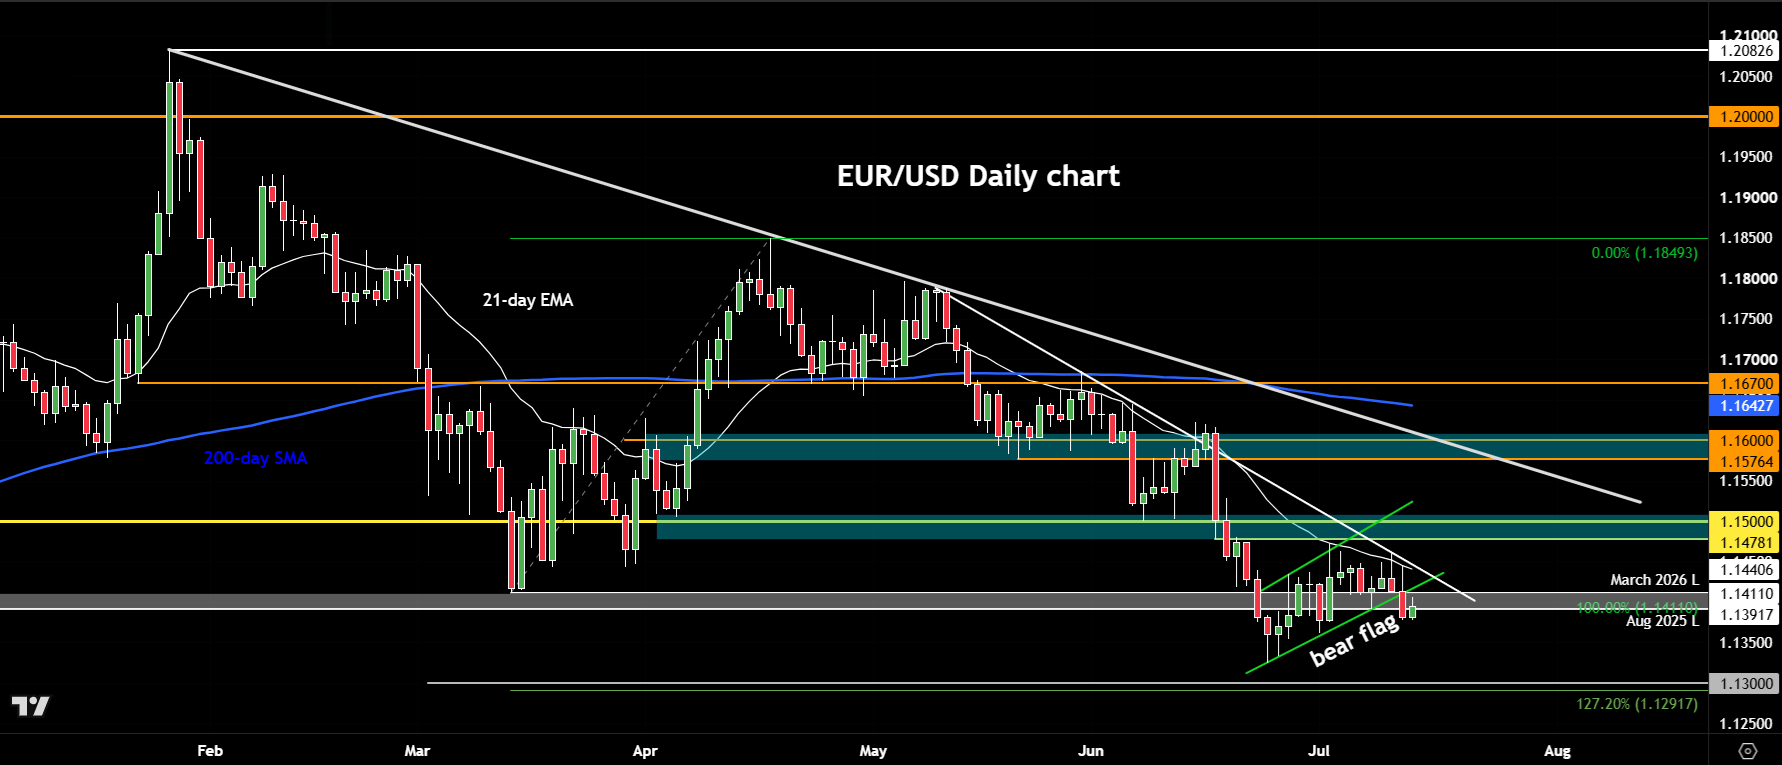
Below there, the 1.1300 area becomes the next key objective for the EURUSD chart. That level also coincides with the 127.2% Fibonacci extension of the March-to-April rally, making it an important technical support zone.
Given the combination of rising energy prices, improving dollar sentiment and the prospect of further Fed tightening, rallies may continue to attract sellers.
On the upside, initial resistance is located around 1.1450, with a stronger barrier between 1.1480 and 1.1500.
With the eurozone economic calendar relatively light in the days ahead, the EUR/USD forecast is tilted to the downside. The pair is likely to remain driven primarily by developments in oil markets, geopolitical headlines and evolving expectations for US monetary policy rather than domestic European data.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 forecast: Tech stocks remain under pressure despite mid terms rally
The Democratic sweep in the US midterms delivered the negative dollar reaction I had anticipated, but that upsurge in stocks was not something I or many others had anticipated. Fears that a Democrat-controlled Congress would trigger a broader sell-off in technology stocks proved premature. Nevertheless, the sector remains under pressure. The political outcome may help explain the Nasdaq’s relative underperformance with futures falling 0.8% today. Sharp falls in shares of Arm and Qualcomm following their results are certainly not helping. While the removal of midterm uncertainty provided a broad-based boost to risk appetite yesterday, investors may be starting to price in the prospect of tighter regulatory scrutiny of Big Tech, particularly around AI, under greater Democratic influence in Congress. This could become a headwind for technology valuations, even if the immediate impact on corporate earnings remains unclear.
Crude Oil, DXY Outlook: Geopolitical Risks Halt Sell-Offs in the Dollar and Oil
The U.S. Dollar Index, Brent and WTI are rebounding from key support levels and oversold conditions after steep sell-offs. U.S.–Iran tensions, inflation risks and rate expectations remain in focus.


GBP/USD forecast: BoE’s hawkish hike, NFP awaited and AI concerns linger
The GBP/USD was holding near the 1.35 handle after the Bank of England raised interest rates to 4% in a unanimous 9-0 vote, against expectations of a 7-2 split. The cable has also benefited from the US dollar's slide after the midterm elections, although Friday's non-farm payrolls report still lies ahead which could have a more meaningful impact.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.