



EUR/USD outlook: Hawkish Fed puts euro on the ropes
The Fed delivered a unanimous hike, stronger economic projections and a more hawkish dot plot, giving markets little reason to unwind aggressive tightening bets and keeping the dollar firmly supported.
Share this:
- Unanimous Fed hike clears a high bar for hawks
- Updated forecasts point to stronger growth, lower unemployment, sticky inflation
- Dot plot validates higher-for-longer pricing across the curve
- Front-end yields surge, driving sharp bear flattening of US curve
- EUR/USD breaks to multi-month lows
After telling markets to figure out the appropriate level for the funds rate themselves, Kevin Warsh and the FOMC duly delivered at the September meeting, hiking rates for the first time in more than three years, as expected, while doing enough to validate the extremely hawkish shift in market pricing seen heading into the decision.
That helped support the US dollar, which ripped higher against a number of the majors, including the euro. With the technical picture for EUR/USD deteriorating sharply, we look at the key levels to watch heading into the weekend.
Fed clears a high bar
Coming into the September FOMC meeting, markets had set a high bar for the Fed to match following the significant hawkish shift in rate expectations over the past month after Warsh’s Jackson Hole speech.
To his credit, Warsh not only met those expectations by following through with a rate hike, but managed to bring the entire FOMC with him. That included influential members such as New York Fed President John Williams, who had been delivering notably dovish commentary heading into the meeting, along with Governor Christopher Waller.
The unanimous vote was the first clear sign that the decision was at least as hawkish as markets had expected, and perhaps even more so.
Stronger growth, lower unemployment, firmer inflation
Source: LSEG
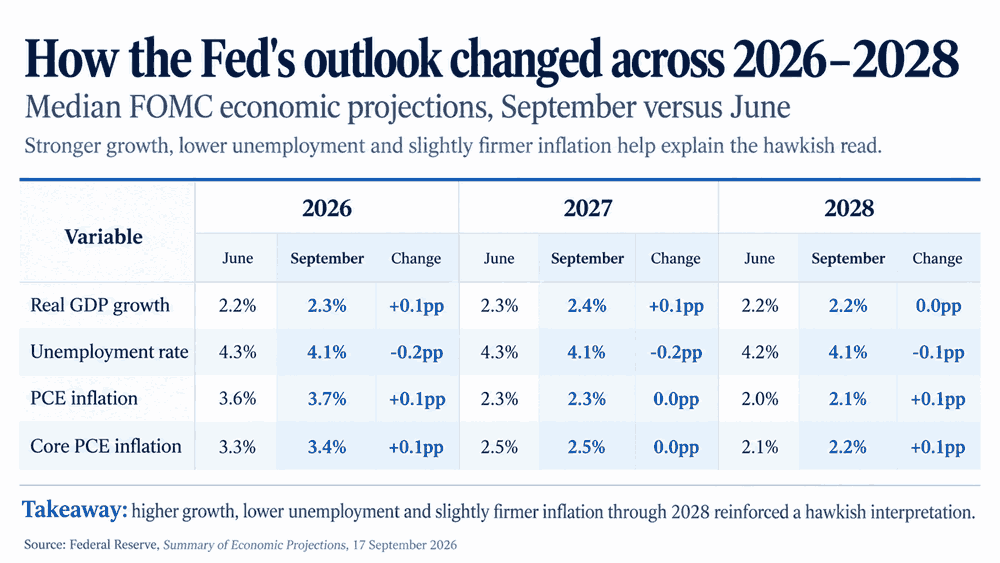
That view was enhanced further by the Fed’s updated economic projections, which upgraded growth this year and next while simultaneously seeing unemployment significantly lower than projected three months earlier in both years.
Importantly, the FOMC also lifted its 2026 core PCE inflation forecast a tenth to 3.4%, and still has it sitting above its 2% target through 2028, even with a far more hawkish rate profile delivered in the accompanying dot plot.
Faster growth, lower unemployment and persistently high inflationary pressures, especially in the near term. That was an entirely hawkish message.
Rates seen staying higher for longer
While Warsh once again declined to provide his own rate forecast, the remaining 18 FOMC participants overwhelmingly saw the need for higher rates moving forward.
Of those 18 participants, only two saw rates remaining at current levels through year-end. Twelve pencilled in one further 25bp hike, while four saw the case for another 50bp of tightening.
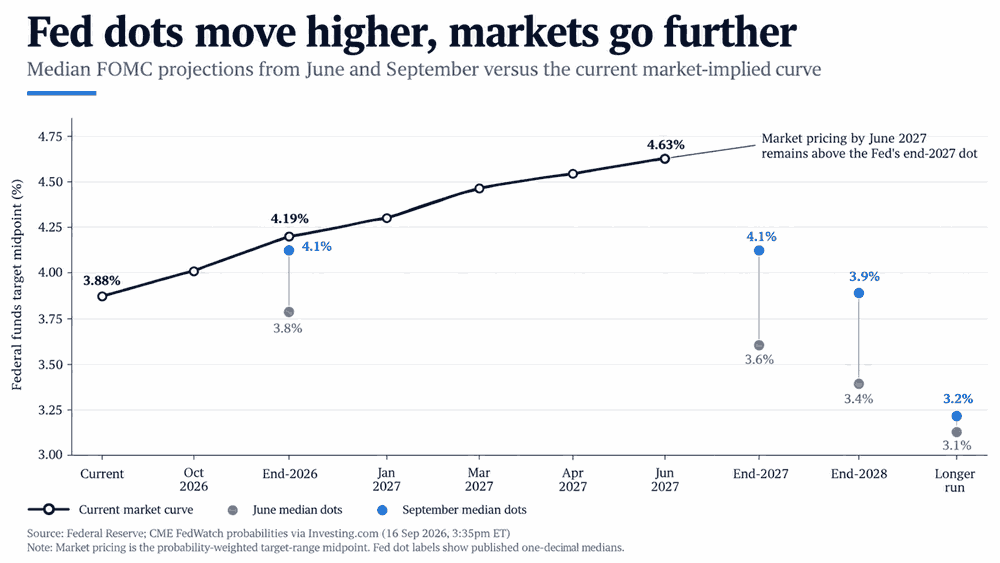
The message remained hawkish further out. The median funds rate was also projected to remain above 4% at the end of 2027, while the longer-run dot was nudged up a tenth to 3.2%, reinforcing the message that policy rates may need to remain higher for longer.
Source: LSEG
While the updated median dot plot path was not as aggressive as what markets had priced heading into the meeting for this year and next, it was hawkish enough to validate the broader direction of travel. Markets not only maintained that hawkish pricing but added to it in response, with another three hikes now expected by June next year.
Undoubtedly, the broader message from the dots was hawkish. But once the dust settles, it may be difficult for the Fed to out-hawk what is already priced into the curve unless we see clear evidence of renewed strength in labour market conditions and another acceleration in inflation over the coming months.
That’s not out of the realms of possibility, but it’s also not the base case. That may eventually create downside risk for the US dollar and front-end Treasury yields, something to keep in mind when assessing directional risks for markets that are heavily influenced by those markets.
Warsh sees little sign of restriction
To ram home the point, Warsh delivered an unequivocally hawkish message in the press conference. He said he would be “hard pressed to describe broad financial conditions as restrictive”, a view he said was widely shared by the Committee, before adding that the September hike had “removed a dose of accommodation”.
Read between the lines, that suggests Warsh does not regard current policy as being particularly restrictive even after the hike. It also leaves the impression that his own stance may be more hawkish than the median FOMC member, even if he declined to provide any guidance.
Front end takes the brunt
Source: LSEG
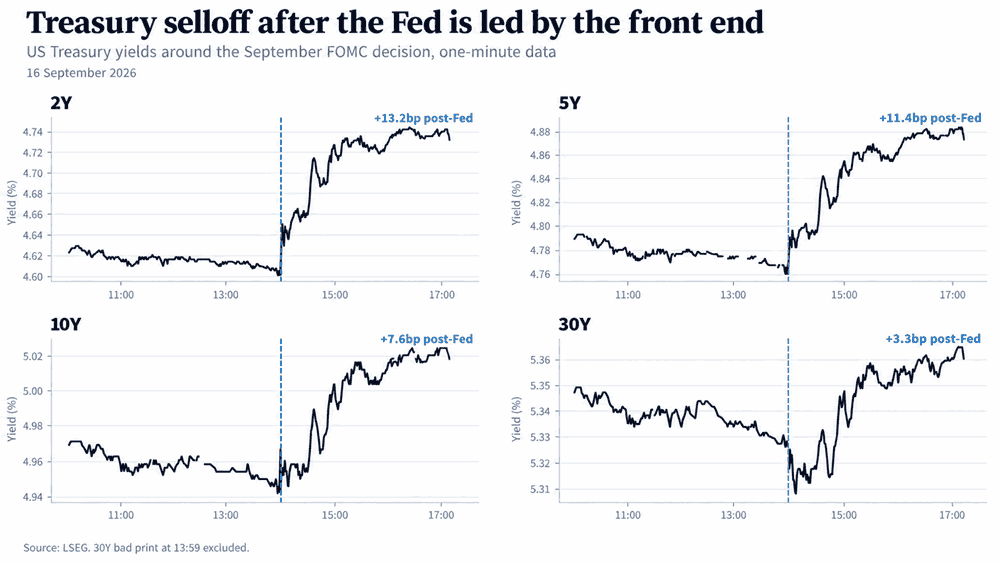
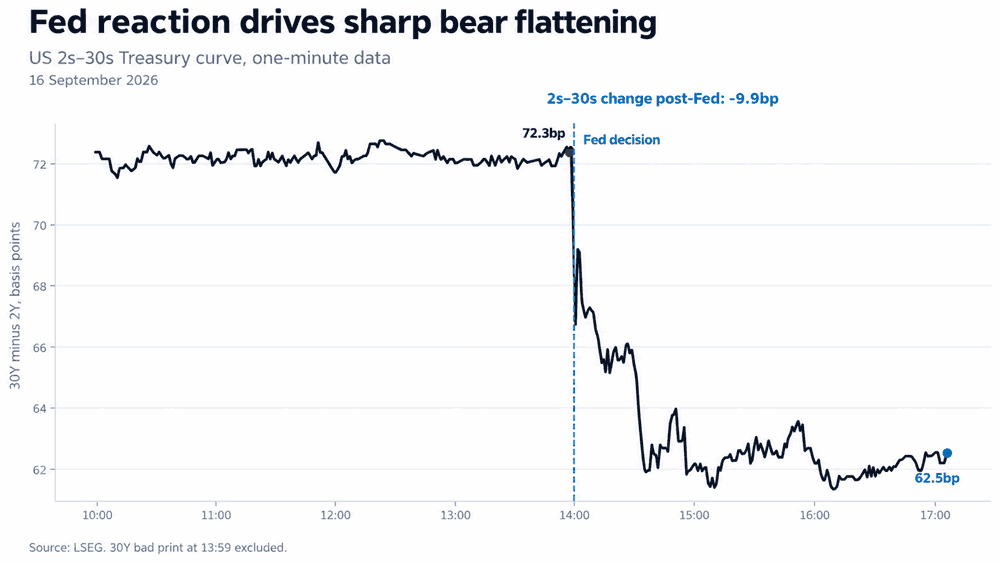
The reaction in US rates was entirely as you would expect, with yields lurching higher across the curve, led by the front end. Two-year yields rose 13.2bp from immediately before the decision, compared with 11.4bp for five-year yields, 7.6bp for tens and just 3.3bp for the 30-year.
The net result was a sharp bear flattening of the Treasury curve, with the 2s–30s differential narrowing from 72.3bp immediately before the decision to 62.5bp afterwards. With the selloff heavily concentrated at the front end, long-dated yields remained beneath the highs seen earlier this month.
Source: LSEG
On the back of the lift in yields across the curve, the US dollar also strengthened rapidly, placing pressure on all G10 FX names, including the euro.
EUR/USD downside pressure builds
Source: TradingView
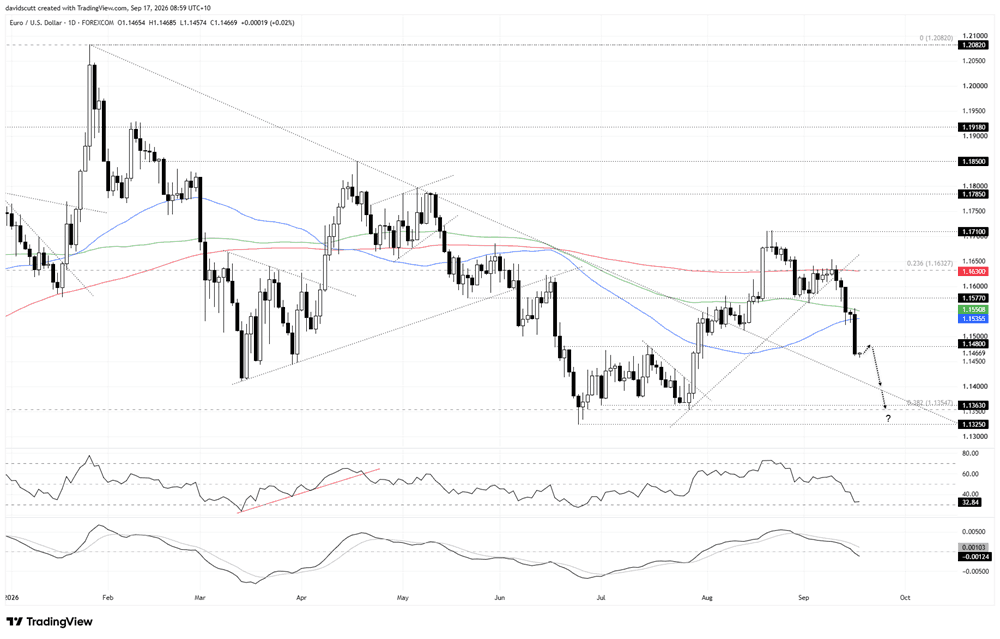
Heading into the FOMC meeting, EUR/USD was already under pressure, losing support at 1.1577 early in the week before settling into a range between the 50-day moving average underneath and the 100-day moving average overhead.
However, on the back of the hawkish hike, the pair was sent sharply lower, hitting levels not seen since late July while simultaneously slicing beneath support at 1.1480.
That’s now the immediate level to watch overhead and can be used as a reference point when establishing potential setups depending on price action around it. If we were to see a retest of 1.1480 and failure, it may provide an opportunity to establish shorts with a tight stop above the level for protection, seeking lower levels.
Those to watch underneath include former downtrend resistance running from the January highs, found today around 1.1420, followed by a much more pronounced support zone beginning around the 38.2% Fibonacci retracement of the January 2025 to January 2026 low-high move and extending down to the June 24 swing low around 1.1325. A breach of the latter would add to the risk of a far deeper unwind back towards support at 1.1200.
If EUR/USD were to reverse back above 1.1480 and hold there, the option is also available to establish longs with a tight stop beneath the level for protection. The 50-day moving average comes across as the first potential upside target, found today around 1.1535.
However, longs are the least preferred of the available options right now, a message backed up by the oscillators, which continue to suggest increasing downside pressure. RSI (14) continues to trend lower and is sitting just above oversold territory around 33, while MACD has now flipped negative after already staging a bearish crossover in late August.
That favours, in the short term, selling into strength and downside breaks.

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.


EUR/USD, Gold Forecast: Two trades to watch
EUR/USD falls to a 2-month low despite Eurozone growth picking up. Gold under pressure as a stronger USD offsets falling oil prices.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.