


FTSE 100 forecast: Technical Tuesday August 12, 2025
n this version of Technical Tuesday, we’re looking at the key drivers shaping global markets, UK economic data, and what technical signals are telling us about the near-term FTSE 100 forecast. Markets were quite quiet in the early parts of Tuesday’s trade, awaiting the release of key US CPI report, which later came in slightly lower than expected and that was enough to send US futures sharply higher....
Share this:
Markets were quite quiet in the early parts of Tuesday’s trade, awaiting the release of key US CPI report, which later came in slightly lower than expected and that was enough to send US futures sharply higher. Despite a weaker start to the day, sentiment was overall positive, as Trump extended the pause on China’s tariffs for another 90. In the UK, we had some mixed data earlier, which kept the FTSE and pound supported, while the weakness in German ZEW data hurt both the DAX and the euro. In this version of Technical Tuesday, we’re looking at the key drivers shaping global markets, UK economic data, and what technical signals are telling us about the near-term FTSE 100 forecast.
Chinese tariffs pause extended
The big news overnight was that Donald Trump has indeed extended the pause on higher tariffs on Chinese goods for another 90 days, until November 10. This was hardly surprising truth be told. The extension gives both sides more time to negotiate and aims to stabilise trade relations between the world’s two largest economies. Had this truce not been extended, the consequences for China and the markets would have been dire. US tariffs on Chinese goods would have jumped to at least 54% today. So, this is clearly a relief for markets. Yet, the lack of a more meaningful rally in global markets overnight suggests the move was priced in. But is the extension really good news? On the one hand, the extension does provide relief that another trade war is averted. But on the other, some would argue it prolongs uncertainty. So, markets didn’t know how to react to the news, although the lack of volatility suggests calm remains the order of the day.
What about inflation concerns?
Since April, markets worldwide, including the FTSE 100, have rallied strongly. This is partly due to easing fears around the trade war and central banks gradually cutting interest rates, which has further fuelled the rally. Inflation concerns, however, have not gone away. Many economists believe Trump’s tariffs will eventually be passed on to consumers. But this wasn’t clearly evidenced in yet another inflation report from the US, released moments ago.
US CPI came in unchanged at 2.7% on a year-over-year basis compared to 2.8% expected, while the month-over-month rate was in line at 0.2% in July. Core measure of CPI was little bit higher than expected, with a print of 0.3% m/m, which helped to push up the y/y rate to 3.1% from 3.0%.
If US and global inflation starts to accelerate again in the coming months, consumers’ purchasing power will be squeezed even more. Meanwhile, central banks might have to keep interest rates higher than they’d like to, which means borrowing costs remain high.
This combination could hit consumer spending hard, ultimately hurting company profits and their share prices.
UK wages fall more than expected
Earlier today, we had some mixed data from the UK following last week’s Bank of England rate cut, which was a very close call when policymakers were sharply divided but ultimately agreed to cut rates.
Today’s data showed average earnings increased by 4.6% in the three months to June compared to a year ago — weaker than the 5.0% rise we saw the previous month. On the jobs front, employment has now fallen eight times in the past nine months. However, the latest drop of 8,000 jobs is the smallest decline so far, suggesting the labour market may be stabilising.
A weakening jobs market could ease wage inflation pressures and open the door to further rate cuts, but whether this happens at November’s meeting remains uncertain following that hawkish cut last week, meaning the chance of another cut in November is now lower.
Meanwhile, a UK data dump is scheduled for Thursday when we will have Q2 GDP as well as monthly data on construction output, manufacturing production and a few other indicators to look forward to. The odds of a further BoE rate cut this year will continue to tumble in the event we see stronger data from the UK this week. Whether this will weigh on the FTSE 100 forecast is difficult to say, given that the index’s components are major global corporations that rely more on sales out of the UK.
FTSE 100 forecast: Key levels to watch
From a technical point of view, the FTSE 100 forecast remains positive for now. The FTSE is holding steady inside a short-term consolidation pattern near its recent record high of 9,191.
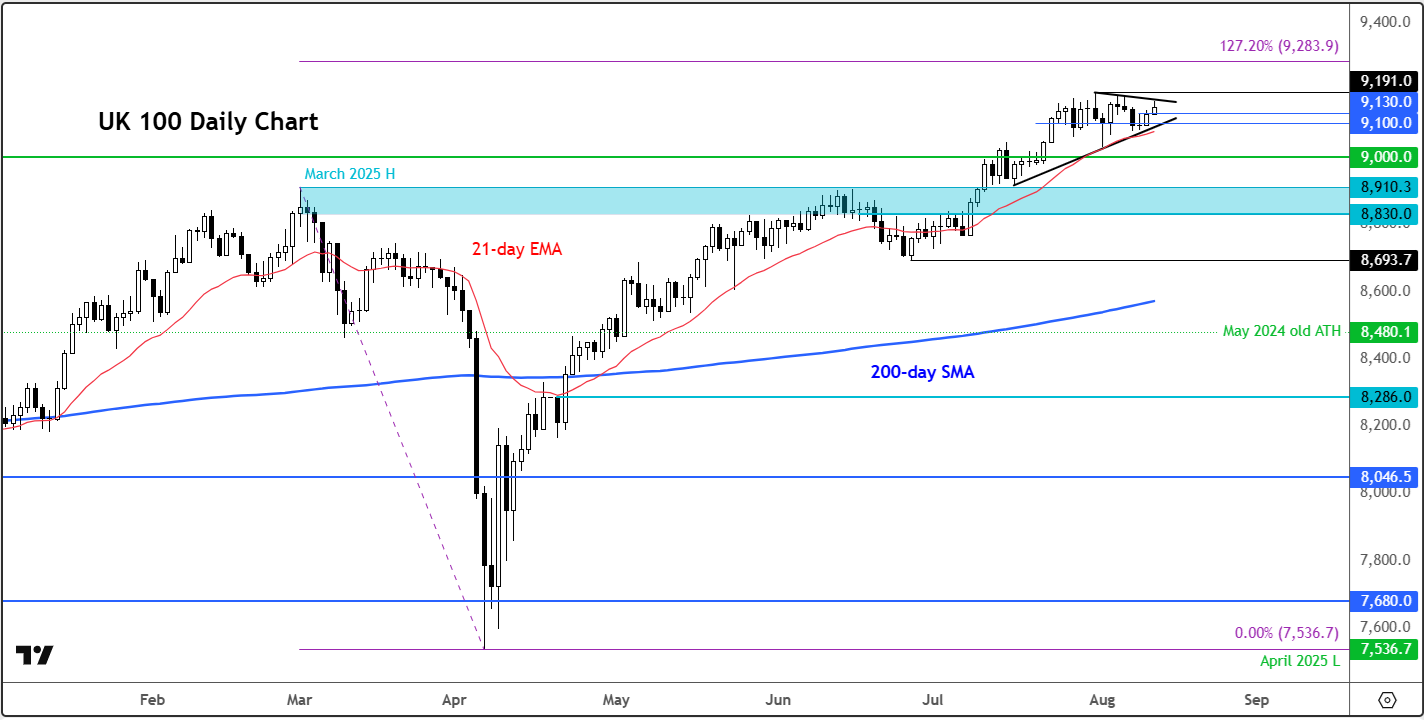
This consolidation is helping to ease overbought conditions on short-term indicators — which is generally a bullish sign.
The FTSE remains above its main moving averages and has broken through several resistance levels.
This means the path of least resistance points clearly upwards.
Until we see clear signs of a market top, the strategy remains to look for dip-buying opportunities and target new highs.
Key short-term support levels to watch are 9,135, 9,100, and 9,050. Longer-term support is seen around 9,000 and the area between 8,830 to 8,910 (shaded in blue on the chart).
On the upside, resistance comes in at 9,165/75, marking the bearish trend line of the consolidation pattern, then the all-time high of 9,191 will be in focus next.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.