

Gold weekly outlook: XAU/USD remains stuck between a rock and a hard place
Gold remains at risk of staging a deeper correction. Though the dollar has eased back a bit along with yields, both still remain fundamentally supported.
Share this:
Gold remains at risk of staging a deeper correction. Though the dollar has eased back a bit along with yields, both still remain fundamentally supported. The US 10-year yield holds support around 5% and a late surge in oil prices on Friday revives inflation concerns. In fact, both precious metals reversed lower on Friday after initially extending Thursday's broad-based recovery, a sign that the sellers have not gone away. With crude elevated and yields still near recent highs, the risk to the near-term gold forecast is tilted to the downside, although central bank buying could limit the damage.
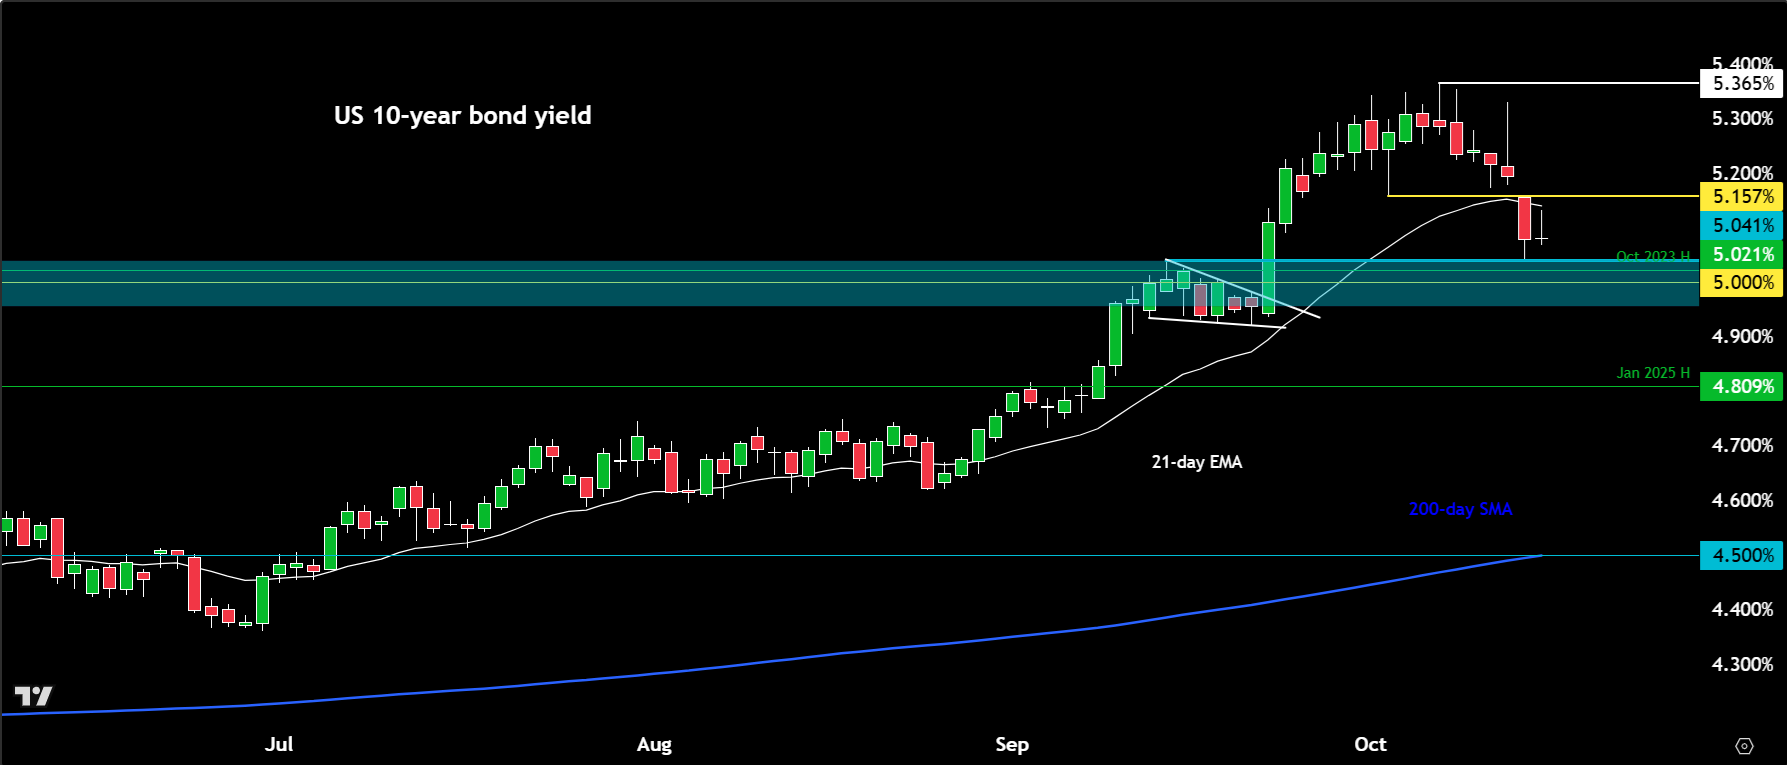
- The US 10-year yield is testing former resistance between 5.00% and 5.05% as support.
- Crude added around $3 late on Friday as concerns over a potential US attack on Iran resurfaced.
- Central bank demand, including from the People's Bank of China, could provide a floor under gold.
Watch the Full Video
Oil rally revives the risk premium
Oil prices surged in the final hours of Friday's session, with crude adding around $3 as concerns over a potential US attack on Iran resurfaced. With no obvious new catalyst in the headlines, the move appears to reflect lingering anxiety over the possibility of US military action, particularly after reports that the Pentagon was preparing for potential ‘mother of all bombs’ strikes on Iran.
Donald Trump did not directly push back against those reports when given the opportunity, although he has previously said the US would not attack Iran before the midterm elections. That leaves markets trying to reconcile two conflicting signals, while the risk premium in crude remains elevated. Iran itself could also seek to escalate tensions, since higher oil prices and the squeeze on global consumers could give Tehran additional leverage, even at considerable cost.
Whatever the explanation, the oil move is increasingly spilling into other markets. Higher crude prices reinforce inflation concerns and complicate the outlook for interest rates. The Nasdaq suffered one of its worst sessions of the year, falling around 2.2%. Any further gains for oil could be particularly problematic for equities, and it could also limit the downside in bond yields, creating a more favourable backdrop for the dollar and a difficult one for gold.
Bond yields find a floor around 5%
The US 10-year yield is meanwhile holding its own above a major area of support between 5.00% and 5.05%, which acted as resistance until the big breakout on 23 September. The pullback in yields earlier in the week, despite hotter-than-expected CPI and PPI readings, raised questions over whether yields had topped out. I don't think they have. With no change in the underlying macro backdrop, the path of least resistance for yields remains higher, and a renewed climb from this former resistance area could allow the dollar to make a comeback at gold's expense.
With a light US calendar next week, oil and Treasury yields are likely to dominate the outlook for the dollar and gold.
Central bank buying could put a floor under gold
That said, the fundamental backdrop is more complicated than the short-term price action suggests. China provides the main macro event on Monday. The world's second-largest economy grew 4.3% year on year in the second quarter, slightly below expectations, while third-quarter growth is forecast to edge up to 4.4%. Industrial production, retail sales and employment data are also due. A weak set of numbers would probably weigh on metals, particularly industrial metals such as copper and silver, and gold could also come under pressure if concerns over Chinese demand intensify.
For gold, however, Chinese demand is only part of the story. Continued buying by the People's Bank of China and other central banks remains an important structural support, and there is little evidence so far that official-sector demand is about to disappear in the final months of the year. If purchases remain strong, investors and speculators could attempt to front-run that demand through ETFs, spot and futures markets. In other words, while the near-term technical picture has deteriorated, central bank buying could provide an important floor under gold.
Technical gold outlook and key levels to watch
From a technical analysis point of view, gold staged a decent recovery from key support around $4,075 to $4,100, the base of the rally that began in early August, before reversing lower on Friday. Friday's bearish close suggests the sellers are still active, and silver's collapse through key support at $59 earlier in the week is a warning that gold could follow.
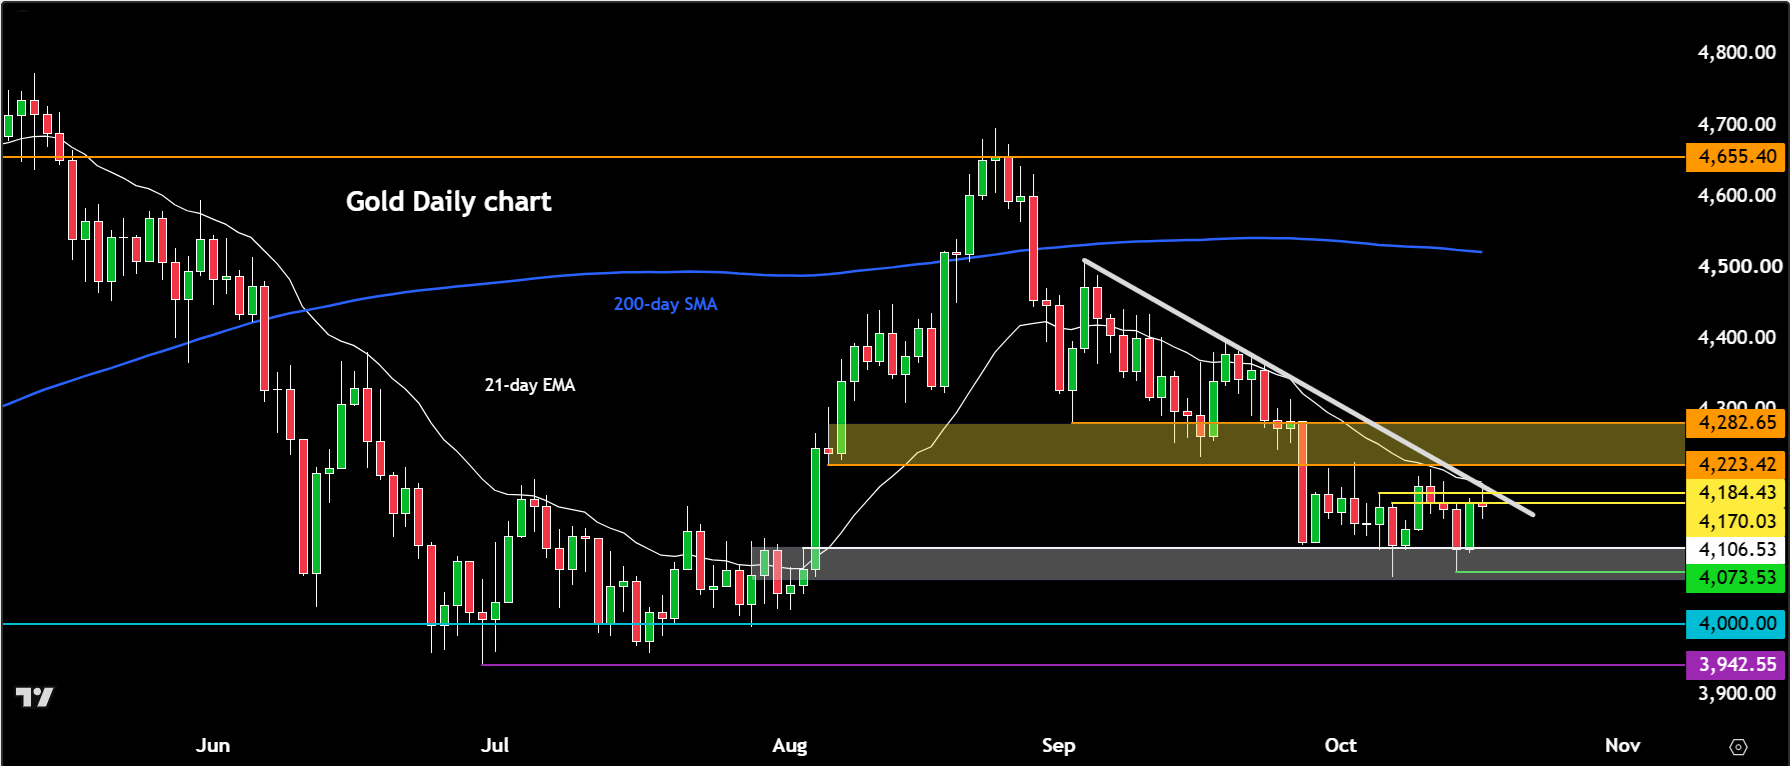
For gold, a move above the trend line would be a constructive signal, but the area of resistance above it near $4,223-$4,282 also needs to be taken out before a bottom can be confirmed. Until then, XAUUSD could face another bout of selling early next week, especailly if oil remains elevated and Treasury yields recover.
Consolidation remains the name of the game until gold clears resistance or loses its August base.
Frequently Asked Questions
Why could higher oil prices weigh on gold?
Higher crude prices reinforce inflation concerns and could limit the downside in bond yields, which in turn could help the dollar recover at gold's expense.
How could China's GDP data affect gold?
Weak Chinese data would probably weigh on metals, particularly copper and silver, and gold could also suffer if concerns over Chinese demand intensify.
Could central bank buying support gold prices?
Continued purchases by the People's Bank of China and other central banks remain an important structural support. If that demand holds up, it could cushion gold even if the dollar strengthens or yields rise.
-- Written by Fawad Razaqzada, Market Analyst | Follow Fawad on Twitter @Trader_F_R

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold weekly outlook: XAU/USD remains stuck between a rock and a hard place
Gold remains at risk of staging a deeper correction. Though the dollar has eased back a bit along with yields, both still remain fundamentally supported.
USD/JPY Weekly Outlook: Volatility Has Left the Building
The yen has ignored broad dollar weakness, falling Treasury yields and renewed market turbulence. Yet its relationship with US interest rates remains intact. So why is USD/JPY going absolutely nowhere fast?

Gold Analysis: XAU/USD Ends the Week Without a Clear Trend
The trading week is coming to an end, and a sense of neutrality remains evident around gold's short-term price action. Over the last five trading sessions, the metal has posted a move of barely -0.3%, a situation that continues to highlight a growing phase of indecision and reflects a clear lack of direction across the market.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.