



Markets Brace for Nvidia Earnings | DAX Near Oversold Zone, Trump buys Bonds
Global markets traded cautiously ahead of Nvidia’s earnings, expected to trigger a record USD 320 bn market-cap swing. US stocks fell, led by tech weakness and fading rate-cut hopes. The DAX extended its slide toward 23,000, entering oversold territory with momentum still weak. Fed officials flagged liquidity stress and hinted at early 2026 balance-sheet expansion. Washington’s tariff cuts and US–Brazil rare-earth cooperation added geopolitical texture, while Apple, Google, and AMD led corporate highlights. Focus shifts to Nvidia’s results and the December FOMC outlook.
Share this:

Market Summary – 19 November 2025
Nvidia Earnings Preview
- Record stakes: Options imply a ~7 % post-earnings move in Nvidia, equivalent to a USD 320 bn market-cap swing—potentially the largest single-day change ever for any company.
- Focus: Investors seek clarity on whether the AI boom is accelerating or cooling. Results are due after the US close Wednesday.
- Context: At ~USD 4.6 trn valuation, Nvidia’s report is viewed as the key sentiment driver for the AI sector this quarter.
Corporate & Sector Highlights
- Apple: Captured 25 % of China’s smartphone market in October, with iPhone 17 sales up 37 % YoY. Overall Chinese smartphone sales rose 8 % YoY.
- Google: Shares hit new highs after Berkshire Hathaway revealed a USD 4.9 bn stake, reinforcing confidence following strong earnings and resilience during the AI pullback.
- US Small Business Sentiment (BoA):
- 74 % of small/mid-sized firms expect higher revenue next year; ~60 % plan expansion.
- Confidence hinges on tariff stability (53 %), cooling inflation (52 %), and lower rates (52 %).
- Profitability for small firms remains resilient in 2025.
Germany: Q3 Earnings Season
- DAX companies: Aggregate profit +2 % YoY, driven by financials, healthcare, and energy tech.
- Auto sector: Earnings –60 % YoY, offsetting broader strength; without autos, total growth would have been +15 ppt higher.
- Outlook: Analysts see –9 % Q4 profit decline, but potential rebound +14 % in 2026 as exports and sentiment stabilize.
Germany 40 Technical Analysis
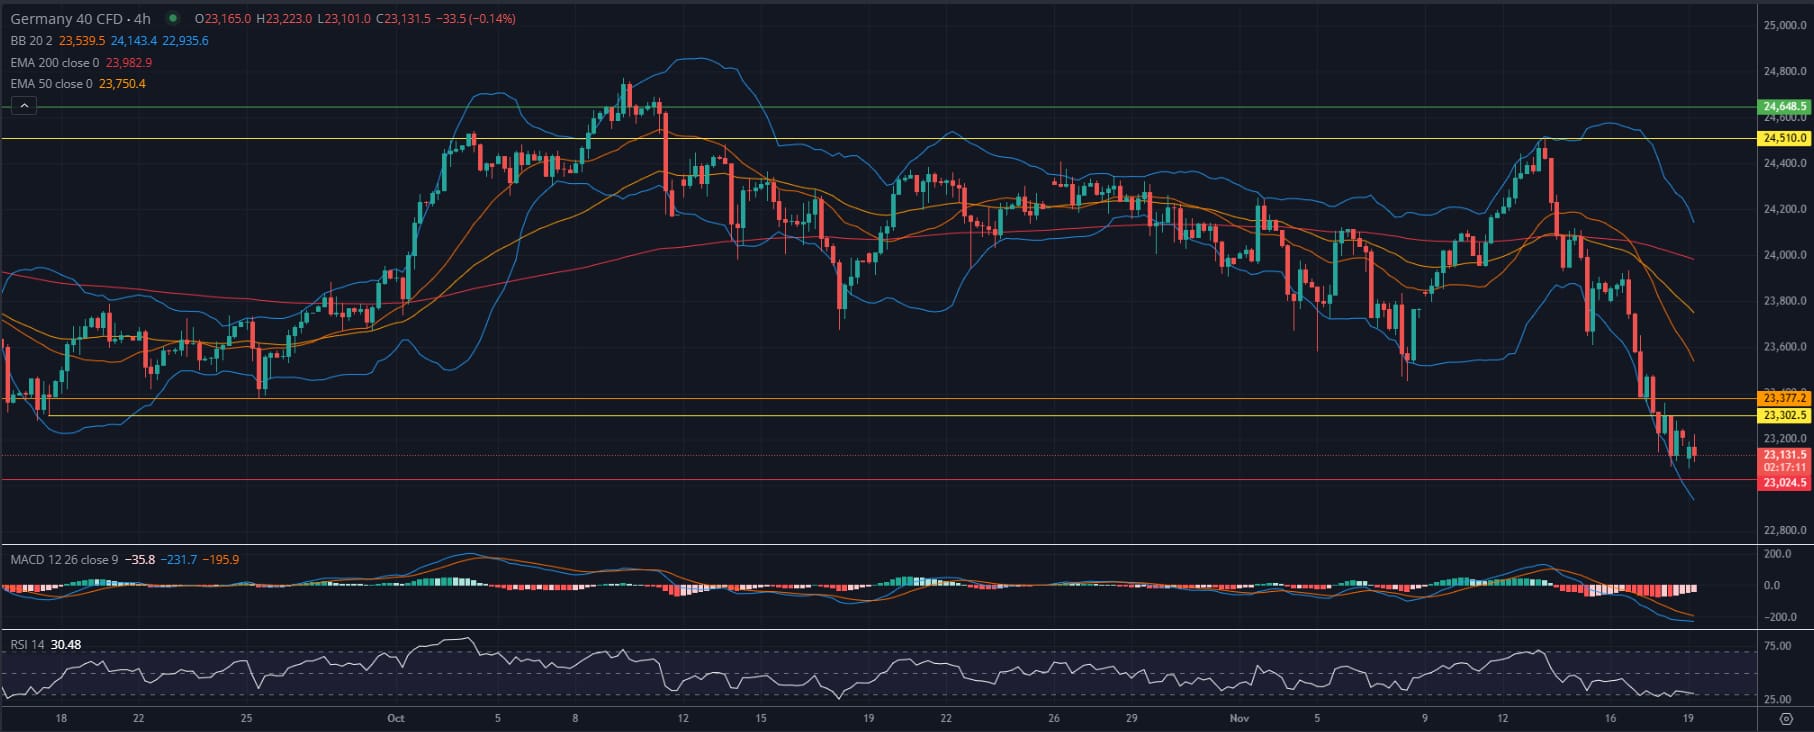
The Germany 40 CFD (4H) remains in a downtrend, extending its decline after breaking below key support at 23,300. Price is now testing the 23,100–23,000 zone, aligning with the lower Bollinger Band and near the March swing low, a critical support area. The RSI (30) is deeply oversold, indicating potential for a technical rebound, though momentum remains weak. The MACD is entrenched in negative territory, confirming persistent downside pressure.
Immediate resistance sits at 23,300–23,380, with stronger supply expected near 23,750 (50 EMA). A recovery above those levels would signal stabilization, while a breakdown below 23,000 risks further downside toward 22,800–22,600. Tone: bearish trend intact, but nearing oversold rebound territory.
Federal Reserve – Rates & Liquidity
- Policy tension: Debate over a possible December rate cut continues as liquidity pressures rise.
- Repo strains: Overnight repo rates exceeding the Fed’s Interest on Reserve Balances (IORB) indicate tight bank reserves.
- Likely response: Market expects the Fed to expand its balance sheet from Jan 2026, adding USD 20 bn/month in T-bills and USD 15 bn/month in MBS reinvestments to prevent year-end repo stress.
- Short-term relief: Treasury’s general account drawdown (~USD 100 bn) and Standing Repo Facility (SRF) usage should temporarily ease pressure.
- Key focus for December FOMC: not only rates, but also liquidity-management guidance.
US Tariffs & Trade
- Food imports: Tariffs cut on coffee, bananas, tomatoes, beef, reducing the average agricultural duty 13.0 % → 10.3 %.
- Swiss goods: Tariffs reduced 39 % → 15 %; Switzerland pledges USD 200 bn US investment (mainly pharma) by 2028.
- Growth impact: Lower tariffs could lift Swiss GDP +0.3–0.5 ppt annually from 2026; CHF strength (0.918/EUR) remains a drag.
Rare Earths & Brazil
- Brazil–US partnership talks: Brazil, holder of the world’s second-largest rare-earth reserves (21 mt), aims to boost output from 20 t to rival China’s 270 t.
- Sector outlook: Brazilian mining P/E 7.1 vs China 13.0—seen as undervalued; new cooperation could diversify US supply chains away from China.
US Real Estate
- Commercial rebound: Q3 2025 transactions +17 % YoY, driven by multifamily, logistics, and data-centre assets.
- Catalyst: September’s 25 bp Fed rate cut improved sentiment; investors favour income-producing, inflation-resilient assets.
Trump’s Portfolio Disclosure
- Total new investments: ≥ USD 82 mn (Aug–Oct), spanning corporate and municipal bonds.
- 175 transactions filed under federal ethics rules.
- Corporate bonds purchased: Broadcom, Qualcomm, Meta, Intel, Home Depot, CVS, Goldman Sachs, Morgan Stanley, JPMorgan.
- Strategic link: Intel bond purchase followed government stake acquisition under Trump’s direction, prompting scrutiny over overlap.
- Theme: Positions align with domestic manufacturing, tech independence, and infrastructure priorities.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.