



Markets Rally on Softer US CPI | Tech Leads, DAX Reclaims Bullish Structure
US equities rebounded on softer CPI, lifting rate-cut expectations and powering a tech-led rally, with semiconductors outperforming. Shutdown-distorted labour and consumption data kept macro uncertainty elevated, while Japan’s rate hike pushed yields to multi-year highs. Eurozone inflation stayed near target, resource stocks surged, and the DAX regained bullish momentum above key Fibonacci levels. Market tone: constructive but prone to near-term volatility.
Share this:
Market Summary
Equities & Rates
- US equities rebounded after softer-than-expected November CPI boosted rate-cut expectations.
- Nasdaq +1.38%, S&P 500 +0.79%, Dow +0.14%.
- Markets now price a 58% chance of Fed easing by March.
- Tech outperformed:
- Micron +10.2% on strong AI-driven profit guidance, lifting semiconductor peers; the Philadelphia Semi Index +2.6%.
- Trump Media +41% after announcing a $6bn all-share merger with TAE Technologies.
- Lululemon +3.5% on reports of a major activist stake.
Asia
- Asian markets followed the US tech rally.
- Nikkei +1%+ after the BoJ hiked rates to 0.75% and hinted at further tightening; Topix +0.8%.
- JGB yields hit ~2%, highest since 2006, as investors assess the BoJ’s tightening trajectory.
Macro
US labour, inflation, and consumption data were distorted by the shutdown
- Jobs:
- October’s reported –105k jobs entirely reflected the DOGE deferred resignation program, which removed 162k federal jobs on paper.
- Private payrolls were actually +52k in Oct and +69k in Nov.
- Unemployment rose to 4.6% mostly due to temporary layoffs of furloughed federal workers.
- Retail sales:
- Headline flat in October, but:
- Auto sales –1.6% after EV credit expiry pulled demand forward.
- Gasoline spending –0.8% thanks to lower prices.
- Online sales +1.5%, showing early holiday buying strength.
- Headline flat in October, but:
- Inflation:
- Headline CPI eased to 2.7% YoY (vs 3.0% Sep).
- Core CPI slowed to 2.6% (vs 3.0% expected).
- Shutdown disruptions — with data collection beginning only Nov 14 — may have artificially depressed some categories such as core goods.
- Market reaction:
- Treasury yields fell only slightly (10-yr ~4.1%).
- Equity indices, still down ~2% on the week, remain driven by concerns about AI investment intensity, not macro relief alone.
Nasdaq-100 Reconstitution (December)
Removed: TTD, LULU, ON, CDW, GFS, BIIB
Added: FER, MPWR, ALNY, WDC, STX, INSM
Eurozone
Inflation near target — ECB on hold
- November Eurozone CPI to be published tomorrow, but major countries released early data:
- Germany HICP: 2.6% (highest in nine months; above 2.4% consensus).
- Spain: 3.1% (above consensus).
- Italy: 1.1% (well below consensus).
- ECB sees stable inflation path and expects moderate growth (2025–2028: 1.2–1.4%).
- Markets showed little reaction as US CPI dominated attention.
Europe – Resources Sector
- European resource stocks gained >20% over the last three months.
- Drivers: sharp rises in copper, aluminium, silver, gold; copper boosted by supply disruptions at a major mine and low inventories.
- After ~14% earnings decline in 2025, analysts expect >30% EPS growth in 2026.
- Sector trades at ~14x forward earnings, ~25% above its 20-year median → increased risk of volatility next year.
DAX
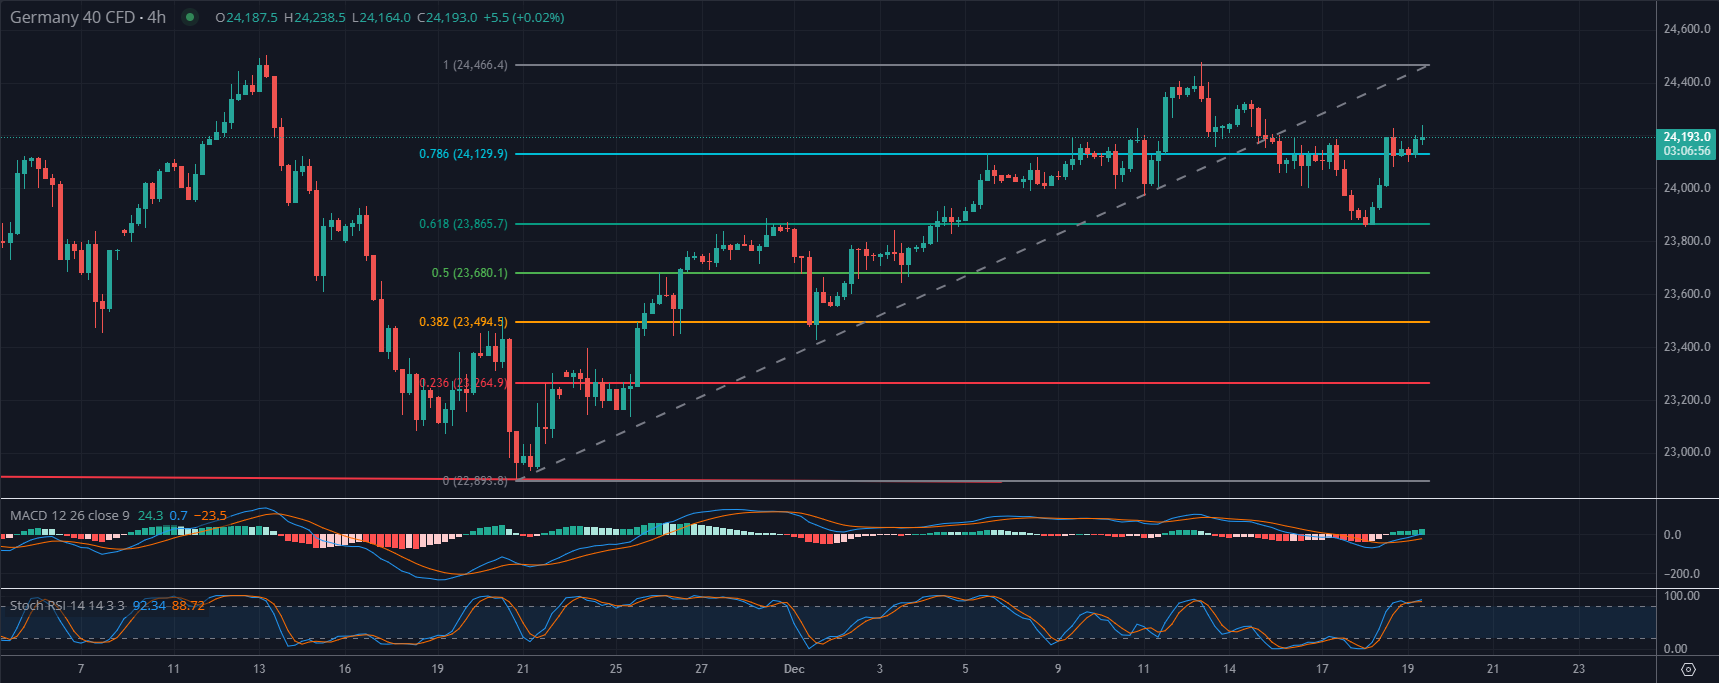
The 4-hour chart for Germany 40 shows a strong recovery after the recent correction, with price now trading at 24,193.6 and holding above the ascending trendline drawn from late November. The index has reclaimed the 24,129 level, which corresponds to the 78.6% Fibonacci retracement of the prior bullish leg, signaling renewed buying pressure. The short-term structure is bullish again, as price is consolidating above the broken trendline and near the upper retracement zone. The next resistance is the recent high at 24,466.4, while immediate support lies at 24,129 and then 23,857 (61.8% Fib).
Momentum indicators confirm the bullish shift. MACD has crossed into positive territory, with the histogram expanding, indicating strengthening upward momentum. Stochastic RSI at 88.72 is in overbought territory, suggesting the rally may face short-term exhaustion or consolidation before another leg higher. If price sustains above 24,129, the next upside target is 24,466.4; failure to hold this level could trigger a pullback toward 23,857 and 23,681 (50% Fib). The technical bias favors continuation toward the recent high, but overbought conditions warrant caution for near-term volatility.
In short: Markets rallied on softer US inflation and strong semiconductor momentum, even as underlying US data remain distorted by the shutdown. Japan tightened policy, pushing yields to multi-year highs. Eurozone inflation remains close to target, resource stocks surged on supply tightness, and the Nasdaq-100 will see notable constituent changes.
-Philip Papageorgiou – Market Analyst
--X ex Twitter: PhilipForexCom
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.