






PCE inflation, NFP and ISM manufacturing in focus: The Week Ahead – 25/08/2023
It's the last trading week of August, and it's fair to say that market conditions were more volatile and eventful than this time of year tends to provide. At the time of writing, we're yet to hear what Fed Chair Jerome Powell has to say, but it could certainly set the tone for next week's trade. And there is no shortage of data to kick off September, including US PCE inflation, GDP, and the ISM manufacturing survey. Final PMIs are also published for the US, UK, Europe, Japan, and Australia. And incoming RBA Governor Bullock speaks, and a host of Australian data includes CPI, retail sales, home loans, and capex.
Share this:
PCE inflation, NFP and ISM manufacturing in focus: The Week Ahead – 25/08/2023
It's the last trading week of August, and it's fair to say that market conditions were more volatile and eventful than this time of year tends to provide. At the time of writing, we're yet to hear what Fed Chair Jerome Powell has to say, but it could certainly set the tone for next week's trade. And there is no shortage of data to kick off September, including US PCE inflation, GDP, and the ISM manufacturing survey. Final PMIs are also published for the US, UK, Europe, Japan, and Australia. And incoming RBA Governor Bullock speaks, and a host of Australian data includes CPI, retail sales, home loans, and capex.
The week that was:
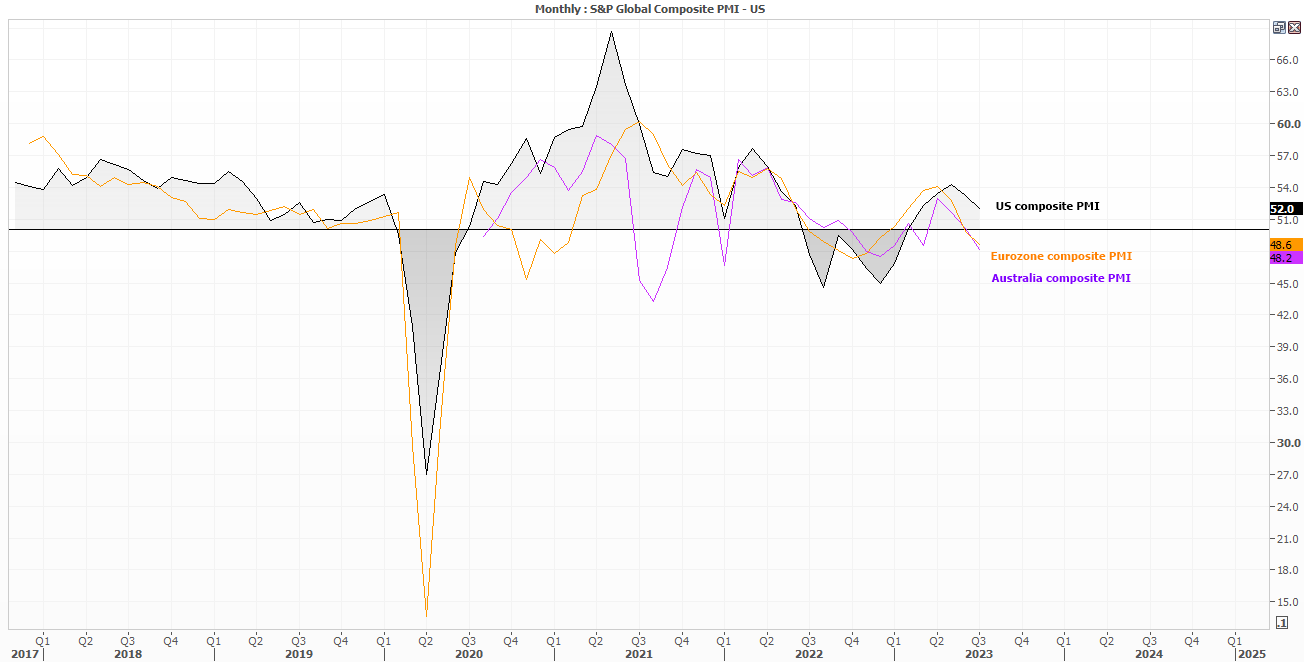
- Flash PMIs mostly disappointed to the downside for both manufacturing and survey reports, dragging composites lower for US, Europe, UK and Australia
- Whilst the weaker PMIs played into the hands of those calling for a peak RBA rate at 4.1%, it also saw bets for another 25bp hike or 50bp BOE hike scaled back
- It also weakened the US dollar and yields ahead of the Jerome Powell’s Jackson Hole speech, as it took the sting out of anticipations of his ‘higher for longer’ narrative
-
Nvidia delivered a blowout earnings report to send shares 10% higher to a new ATH during after hours trade (although those gains were promptly returned during risk-off trade on Thursday)
-
Rising yields and a higher dollar weighed on Wall Street on Thursday, sending the Nasdaq over -2% lower and forming a bearish engulfing day to erase the week’s gains
The week ahead (calendar):
Please note that it is a public holiday in the UK on Monday 28th August 2023


This content will only appear on City Index websites!
Earnings This Week
Look at the corporate calendar and find out what stocks will be reporting results in Earnings This Week.
The week ahead (key events and themes):
- US PCE inflation
- Nonfarm payroll
- ISM manufacturing PMI
- Final PMIs
- US GDP
- Australian data (CPI, retail sales, home loans capex and bullock speech)
US PCE inflation
Inflation data continues to be the key metric that drives expectations for monetary policies, and therefore drives sentiment for global markets. US inflation data is at the top of the pile of significance, and PCE data is ‘top of the top’ given it is generally the Federal Reserve’s preferred measure.
The significance of this particular PCE inflation report may hinge upon how hawkish Jerome Powell is at his Jackson Hole speech. But in a nutshell, the quicker inflation decelerates, the less hawkish the Fed needs to be and the US dollar could falter.
Last month we saw the annual rate of core PCE fall to a 21-month low of 4.1%, which was its fastest decline since the pandemic. But it remains debatable as to whether we’d see another drop of a similar magnitude next week (as nice as that would be). Looking through the data, services PCE has risen 0.3% m/m three in the last four months. Therefore, a print of 0.2% or lower would be a welcome development.
US employment data (Nonfarm payroll, ADP payrolls, jobless claims)
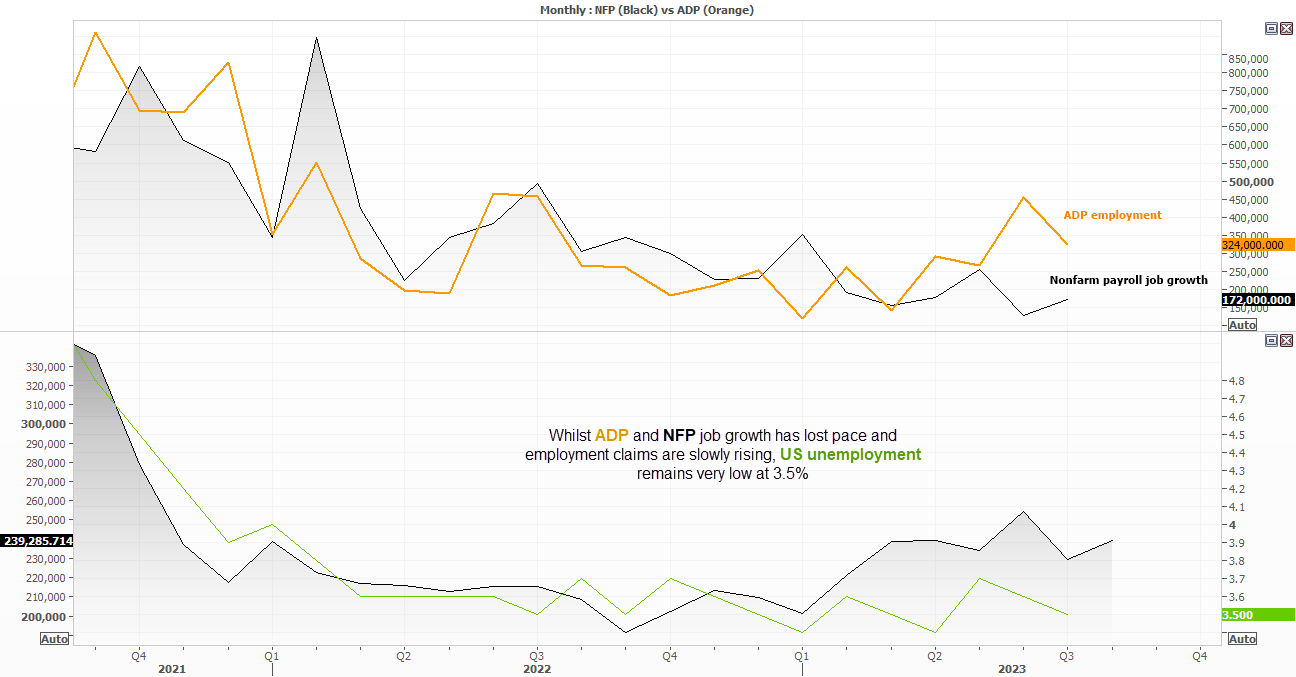
PMIs aside, we’re just not seeing enough weakness in headline employment data to get too excited about the Fed cutting rates any time soon. Whilst there has been plenty of speculation of weakness using other employment metrics, they do not carry as much weight as they perhaps should as the Fed seem to make decisions on lagging indicators such as the unemployment rate. And an unemployment rate of 3.5% hardly screams recession to the Fed, which is a key reason why rate cuts any time soon remain unrealistic.
Still, the monthly nonfarm payroll report is released on Friday and still warrants attention. But we also have other employment metrics which can help shape the tone, because if they come in stronger than expected traders may try to front-run a hotter NFP report (and visa versa). Job openings is released on Tuesday, ADP payroll on Wednesday and jobless claims are on Thursday.
Market to watch: USD/JPY, EUR/USD, S&P 500, Nasdaq 100, Dow Jones, WTI crude oil, gold
ISM manufacturing PMI
The US manufacturing sector topped out in early 2021 according to the ISM (Institute for Supply Management) and been contracting for nine months. Another weak print may not change much, unless it falls at a much faster pace and backs up the weak data seen on the S&P Global PMI survey. However, new orders are contracting at a much slower pace, so if there is any hope to be gleaned it would be to see new orders move closer to 50 (or above it to denote expansion for the future).
Market to watch: EUR/USD, GBP/USD, USD/JPY, S&P 500, Nasdaq 100, Down Jones, WTI crude oil, gold
Final PMIs
Given that flash PMIs generally include around 80-90% of all survey respondents, final PMIs are easily forgotten as they tend not to deviate too far from the flash estimates. Yet with the general theme of deterioration for manufacturing and services PMIs for the UK, Europe and US this week, traders may take a bit more notice of these final report. Perhaps the original reports were too gloomy, and that leaves some hopes that they may be revised slightly higher. Otherwise, that just leaves the scenario where final PMIs confirm just how bad the flash reports were, or even worse they decline at a faster rate.
Market to watch: EUR/USD, GBP/USD, EUR/GBP, USD/JPY, S&P 500, Nasdaq 100, WTI crude oil
US GDP (2nd revision)
Whilst it seems unlikely to be a major event, GDP should at least be mentioned as the preliminary release far exceeded expectations. On one hand it alleviated concerns of a hard landing, on the other it pushed out expectations of Fed cuts further into 2024. SO we at least get to find out whether GDP really did rise 2.4% in Q2, or if it needs to be downgraded and fan more fears of a hard(er) landing for the US economy.
Australian data (CPI, retail sales, home loans capex and bullock speech)
As things stand, many suspect that the RBA have indeed reached their peak rate at 4.1% - although that doesn’t mean the threat of further hikes does not remain. Yet with household spending down around -10% y/y by some measure, cracks forming in Australia’s headline employment figures and China’s data going from bad to worse, the threat of an imminent hike is dead in the water.
However, there is enough data next week to potentially change things if they are one sided enough. The monthly inflation report on Wednesday is the key event, and with a weighted CPI of 5.4% it clearly remains “too high”. With housing up 7.4% y/y and food up 7% y/y, we’re not expecting miracles. But it needs to pull back at a faster pace to truly remove the threat of another hike. But we also have retail sales on Monday, and if household spending is a guide then we may see it contract at a faster pace than last month’s -0.8% fall. It could also take some of the wind out of Wednesday’s CPI sails if it is soft enough.
Building approvals is unlikely to be knocking out strong figures on Thursday, but there is a case that is it around a cycle low looking at a 15-year chart. Capex data also provides a lead on GDP and is released alongside building approvals.
Incoming governor Michelle Bullock speaks on Tuesday at 5:40 AEDT (07:40 GMT). Titled “Climate Change and Central Banks”, it may not be ground breaking in terms of policy. But her words will carry great importance when she takes over the helm in a few weeks from now.
Market to watch: AUD/USD, NZD/USD, AUD/NZD, NZD/JPY, AUD/JPY, ASX 200
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD forecast: US Mid-terms, NFP and BoE put cable in sharp focus
The US dollar has been a standout loser in the FX space today. A Democrat-controlled Congress is widely seen as being at least mildly negative for the dollar, partly because of the potential implications for the AI investment story and partly because of the risk of another prolonged government funding standoff, potentially from next summer. This has allowed the likes of the GBP/USD to rally alongside gold and silver.

AUD/USD Weekly Outlook: RBA Hike, US Midterms and NFP Collide
AUD/USD faces a pivotal week as an expected RBA hike, US midterm elections and nonfarm payrolls test the Australian dollar's recovery.
Australian Dollar Outlook: AUD/USD Screams Sentiment Extreme Into Fed, CPI
AUD/USD rebounds despite record bearish futures positioning, with Australian Q3 CPI and the Fed meeting threatening to trigger another short squeeze.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.