





Q4 US Dollar Outlook: US Economic Exceptionalism to End?
The US dollar has surged on US economic exceptionalism so far this year, but that trend may change in Q4...
Share this:
US Dollar Takeaways
- The US dollar has surged on US economic exceptionalism so far this year, while economies in the Eurozone have underperformed.
- The Fed is either done or nearly done raising interest rates, but the full impact of rate hikes on the financial sector may still be coming in Q4.
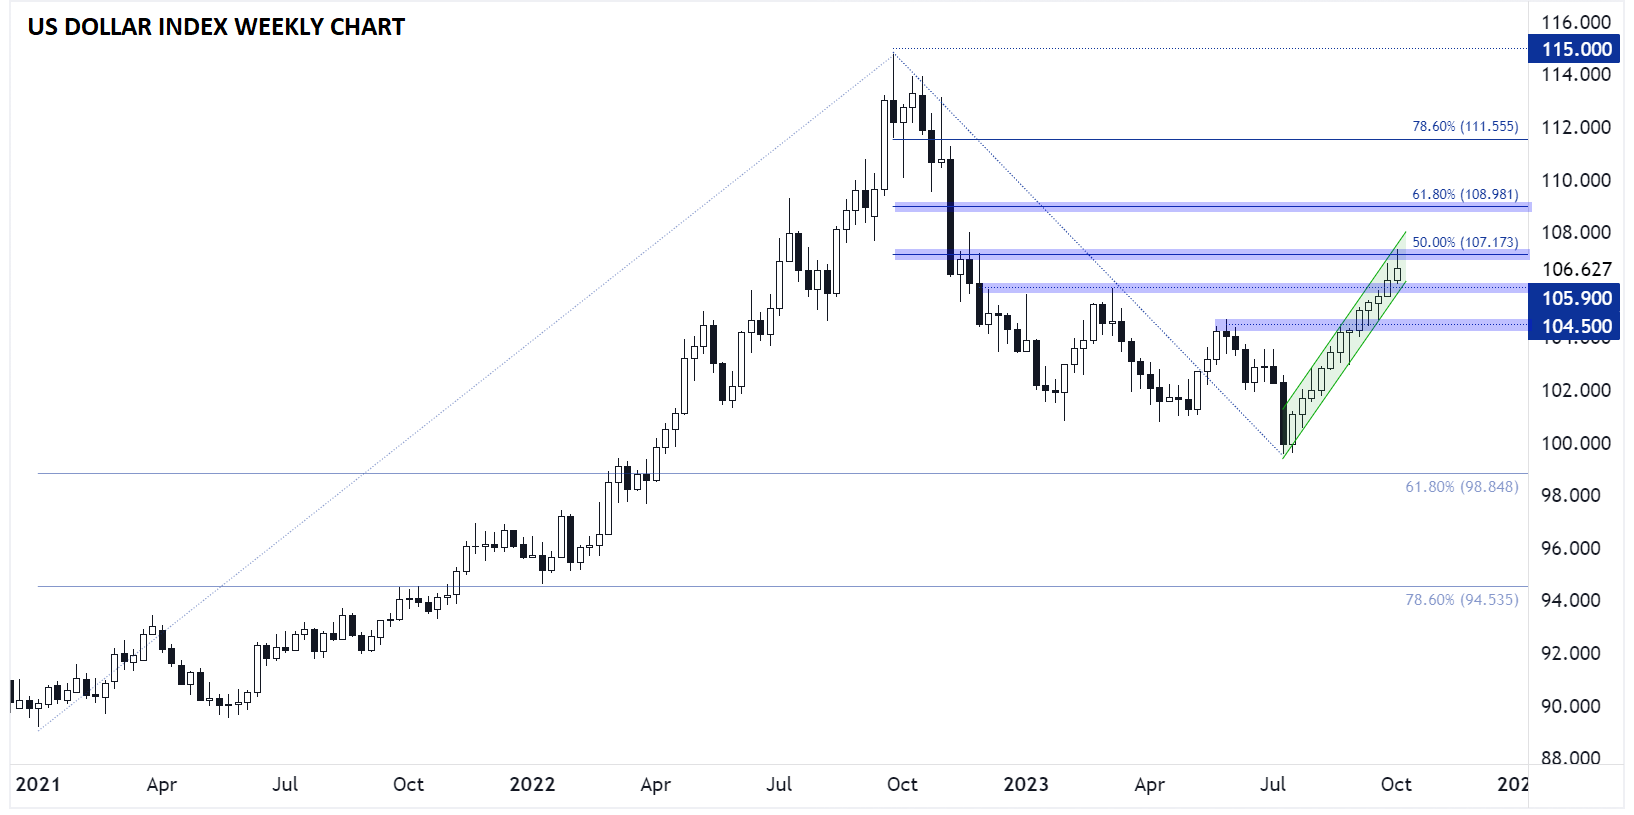
- As long as the US Dollar Index remains above 105.90, the path of least resistance remains to the upside from a technical perspective.
US Dollar Fundamental Analysis
Heading into 2023, the big debate about the US economy was whether it would experience a “hard landing” (read: deep recession) or a “soft landing” (read: growth slowdown/mild recession) as a result of all monetary and fiscal tightening over the previous 18 months. Now, three quarters of the way through the year, the market has seemingly decided that the hard landing scenario is entirely off the table, and, based on strong US data of late, even the soft landing scenario may be too pessimistic.
We’re hesitant to wave the proverbial “all clear” flag for the US economy heading into the end of the year – monetary policy acts with “long and variable” lags after all, and there still is the potential for a government shutdown in November – but it’s clear that the US economy is outperforming its major rivals. As the chart below shows, composite PMI readings in the US have turned definitively higher, at the same time that readings on the European economy have rolled over:
Source: TradingView, StoneX
Looking at monetary policy in more detail, the Federal Reserve has seemingly pushed back on fears of a sharp slowdown any time soon, leaving a potential interest rate hike on the table by the new year and removing two of its projected rate cuts from the 2024 “dot plot.”
While central bankers seemingly believe everything will be hunky dory (and are accordingly still engaging in quantitative tightening” to the tune of nearly $120B/mo), the key flashpoint to watch in the fourth quarter will be the financial sector. As the chart below shows, deposits are fleeing the banking sector at an unprecedented rate, and many small regional banks (remember those?) are facing large unrealized losses after the fastest interest rate rise in decades:
Source: Apollo
Ultimately, all modern capitalist economies run on debt and lending, so if we see another panic centered on the banks, it could pour cold water on the “US economic exceptionalism” theme…though as we saw in March, that doesn’t necessarily mean that the US dollar will fall!
Key developments to watch in Q4:
- We anticipate that the Fed will NOT hike interest rates again this year, but it’s certainly still possible if inflation or jobs data comes in elevated relative to expectations.
- Concerns over the health of the banking sector play a role in the above, with tighter credit taking a toll on growth more broadly.
- The economic exceptionalism of the US moderates as the US economy “catches down” to slowing growth in other regions
US Dollar Technical Analysis – DXY Weekly Chart
Source: TradingView, StoneX
Turning our attention to the weekly chart, the US Dollar Index (DXY) remains within a tight bullish channel as we go to press; indeed the market is in the midst of a 12-week winning streak, showing investors’ clear preference for the relatively strong growth and high yields offered by the US economy.
In terms of the levels to watch on the US Dollar Index, previous-resistance-turned-support at 105.90 could well put a floor under any near-term dips; a similar dynamic could emerge around 104.50 if that level gives way.
To the topside, there’s little in the way of nearby highs and lows, so traders will likely look to the Fibonacci retracements of the 2022-23 pullback, including 107.20 (50%), 109.00 (61.8%), or even 111.50 (78.6%) if the bulls are able to maintain the recent bullish momentum. As long prices can hold above the late-September breakout level at 105.90, the path of least resistance for the US Dollar Index will remain to the upside.
-- Written by Matt Weller, Global Head of Research
Follow Matt on Twitter: @MWellerFX
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Analysis: Resilient U.S. Labor Market Continues to Pressure XAU/USD
Recent trading sessions have not been particularly favorable for gold in the short term. XAU/USD has fallen nearly 2.5% over the last three sessions, reflecting that selling pressure is once again gaining relevance and that the metal continues to struggle to regain momentum.


US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.


USD/JPY Analysis: Rising U.S. Yields Leave the Yen on the Defensive
As the first week of November progresses, renewed weakness in the Japanese yen is once again becoming evident in the short term. This dynamic can be seen in the recent performance of USD/JPY, which has posted two consecutive bullish sessions and gained more than 0.7%, reflecting a return of buying interest in the dollar while the yen continues to lose momentum.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.