



RBA Hikes, Signals More to Come as Inflation Stays Sticky
The RBA is back hiking, lifting rates to 3.85% as expected. With inflation forecasts refusing to cooperate, markets are now bracing for more tightening as Governor Bullock prepares to face the media.
Share this:
- RBA Cash rate lifted 25bp to 3.85%, first hike since Nov 2023
- Inflation forecasts signal price pressures remain sticky
- Markets now price further hikes this year
- AUD jumps back above 0.7000
- Bullock presser at 3.30pm the next key risk even
The RBA is back hiking. A 25bp move lifts the cash rate to 3.85% for the first time since November 2023, as expected, but the real signal sits in the forecasts. With inflation projected to stay sticky, the door is open to multiple hikes this cycle, putting extra focus on Governor Michele Bullock’s 3.30pm press conference.
RBA Hawks Circle
On inflation, the RBA’s language clearly hardened relative to December. Then, the Board stressed uncertainty, saying inflation had “picked up more recently,” with only “some signs” of a broader lift and an emphasis on monitoring persistence. In February, that conditional framing is gone. Inflation is now described as having “picked up materially in the second half of 2025,” with the increase tied directly to “greater capacity pressures” and an explicit judgement that inflation is “likely to remain above target for some time.”
The labour market story has also shifted. December acknowledged conditions were “a little tight” but leaned on easing dynamics, pointing to rising unemployment, slower employment growth and “further modest easing” ahead. February removes that bias. Labour market conditions are deemed still “a little tight,” but are now said to have “stabilised,” with unemployment “a little lower than expected.” References to easing or slowing momentum were dropped.
On productivity, December relied on indirect signals, but February was more direct. While productivity is still not mentioned explicitly, the Board now says growth in the economy’s “supply capacity remains limited,” and that capacity pressures are “greater than previously assessed,” shifting constraints from a risk to a reality.
Finally, its language on economic growth strengthened noticeably. December framed activity as a recovery, with private demand having “strengthened” and momentum better than expected. February sharpens this materially, saying private demand has strengthened “substantially more than expected” and is “growing more quickly than expected,” explicitly linking stronger growth to rising capacity pressures.
Inflation Sticky, Higher for Longer
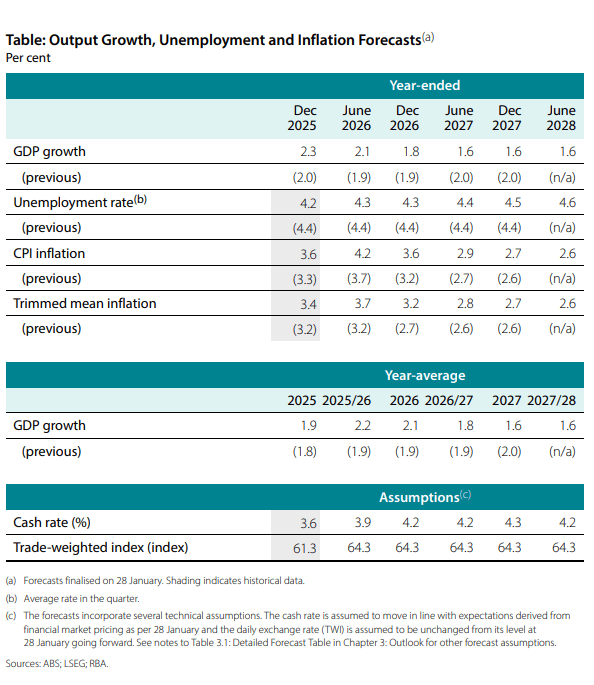
That firmer assessment is reflected clearly in the updated forecasts, which quietly point to a more extended tightening phase than the February hike alone would suggest.
Source: RBA
The big takeaway is that February looks unlikely to be a one-and-done. The RBA’s updated trimmed mean inflation forecasts do not show inflation returning to the 2.5% midpoint of its 2–3% target range by mid-2028, even after factoring in a stronger Australian dollar, lower crude oil prices and an assumption that the cash rate peaks at 4.3% in the final quarter of 2027.
Notably, the profile implies trimmed mean inflation running at 0.9% in each of the next two quarters, underlining the Bank’s concern that disinflation remains slow.
With the cash rate at 3.85%, that forecast path implies the Bank may ultimately unwind all three rate reductions delivered in 2024.
Consistent with policy remaining restrictive for longer, the RBA has revised down its GDP forecasts, with growth expected to slow to 1.6% from the middle of next year, down from 2% previously. The unemployment rate is forecast to drift higher over the projection period, reaching 4.6% by mid-2028, although the outlook for this year was trimmed slightly to 4.3%.
While the Bank is using market pricing to generate these forecasts, the detail sends a clear implicit signal: returning inflation to target under current conditions is likely to require more than a single rate hike.
Markets Price Multiple Rate Hikes
Source: Bloomberg
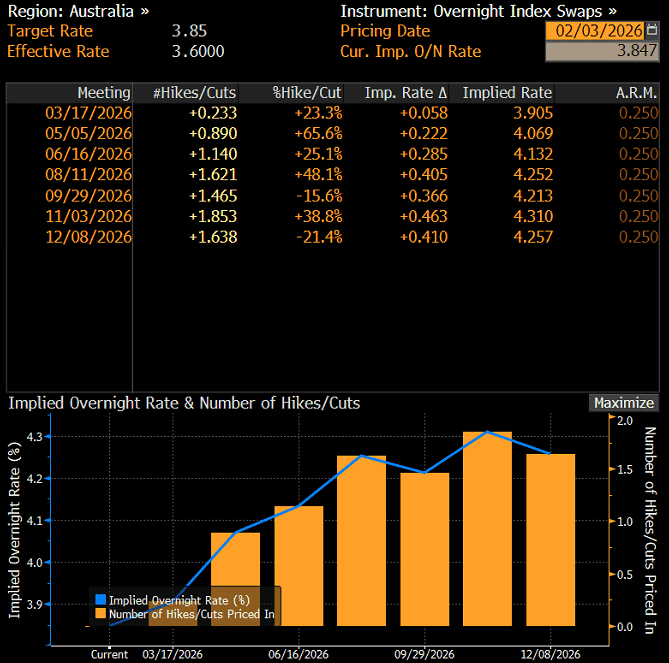
Markets have moved quickly to price a longer tightening cycle. By the RBA’s May meeting, when the Q1 inflation data is available, a follow-up 25bp hike is bordering on a lock at 89%, according to swaps markets. That’s not unusual given the RBA has often delivered multiple moves early in a cycle following quarterly inflation reports.
By August, when the Q2 data is available, an additional hike to 4.35% is seen as a roughly two-in-three chance. That looks about right given the run of data recently, which has come in on the firm side of expectations more often than not for key indicators.
The risk around whether we see fewer or more hikes this cycle appears premised on fiscal policy decisions in the federal budget, labour market trends and developments offshore.
Neutral policy settings, where inflation and unemployment are stable, arguably sit above the current cash rate. That raises the risk the RBA may need to deliver more hikes than are currently priced to re-establish equilibrium in the economy.
AUD/USD Surges, Reclaiming .7000

Source: TradingView
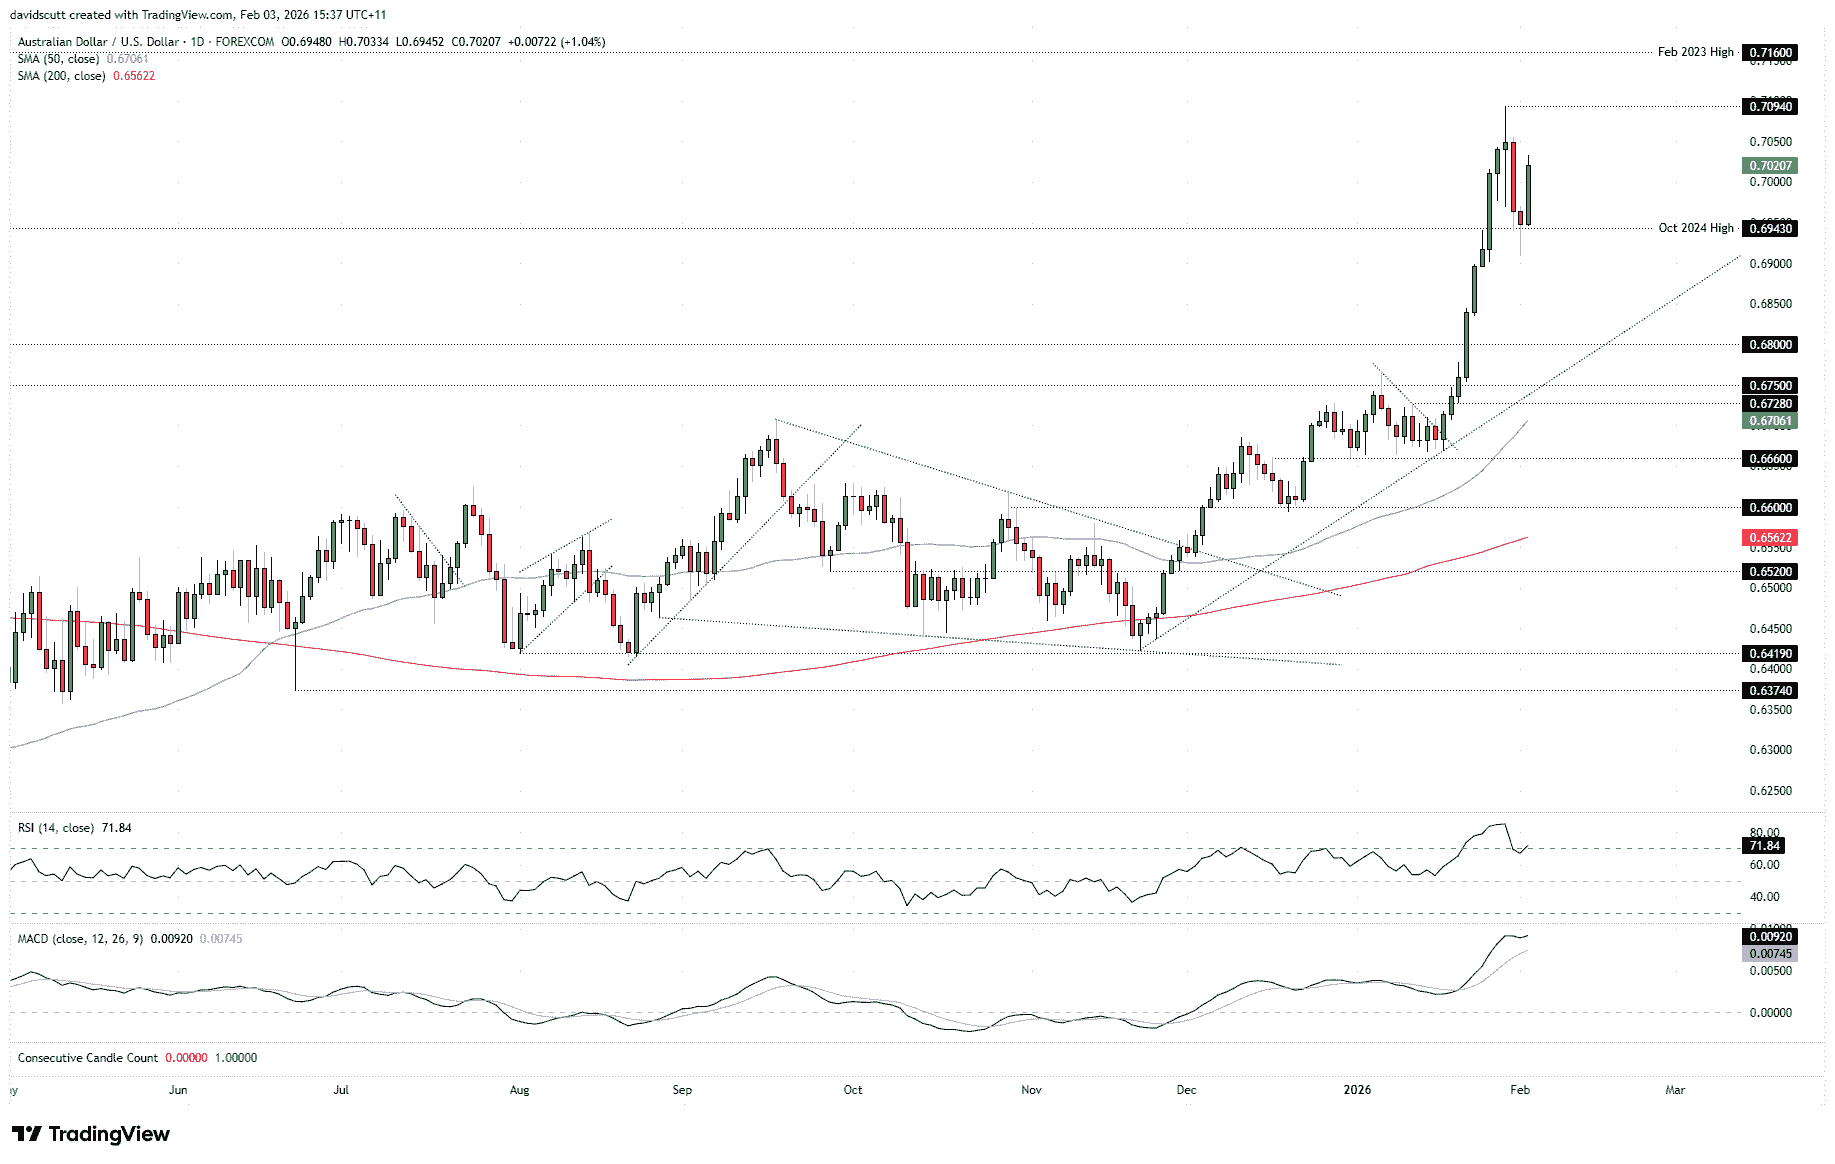
Naturally, the RBA’s hawkish hike delivered a sharp upside response in AUD/USD, pushing the pair back above the psychologically important 0.7000 level. Momentum indicators are confirming the move, with both RSI (14) and MACD showing upside strength accelerating. From here, bulls will be eyeing a retest of the January 29 high at 0.7094, particularly after the failed bearish break below the October 2024 high earlier this week, which produced a clear hammer candle on the daily chart.
While there is little to dislike about the Aussie from a domestic perspective, broader risk appetite remains fragile, which may limit how far the rally can extend in the near term, especially with the pair already looking somewhat stretched. That said, a sustained break above 0.7094 would put a retest of the February 2023 high back into play, with the 0.7250–0.7280 zone another key area to watch after marking multiple failed bullish breakout attempts in prior years.
On the downside, initial support sits at 0.6943, with 0.6900 and 0.6800 next on the radar should we see a deeper pullback. For now, the technical picture continues to favour buying dips rather than chasing strength.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?

Euro Technical Outlook: EUR/USD Support Reversal Sets Up Breakout Test Ahead of NFP 11 4 2026
Euro bulls are attempting to build on the rebound from recent lows, but pivotal resistance still stands in the way of a larger EUR/USD recovery.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.