



S&P 500 forecast: Technical Tuesday | September 1, 2026
Risk appetite has been hurt today with global stocks, gold, bonds and bitcoin all falling. On the ascendency were the usual suspects: Oil and the US dollar amid further escalating tensions between the US and Iran. Stock investors are cementing hawkish Fed expectations to an extent that it is starting to hurt their appetite for risk. Also unnerving investors is the continued rise in global bond yields – which kind of goes hand in hand with oil prices.
Share this:
Risk appetite has been hurt today with global stocks, gold, bonds and bitcoin all falling. On the ascendency were the usual suspects: Oil and the US dollar amid further escalating tensions between the US and Iran. Stock investors are cementing hawkish Fed expectations to an extent that it is starting to hurt their appetite for risk. Also unnerving investors is the continued rise in global bond yields – which kind of goes hand in hand with oil prices. Against this backdrop, the near-term risks to our S&P 500 forecast remains tilted to the downside.
Before discussing the macro risks further, let’s have a quick look at the chart of the S&P 500 first.
Technical S&P 500 forecast and key levels to watch
From a technical analysis point of view, the S&P 500 forecast is yet to turn bearish despite some not-so-strong price action in the last few days. But is it about to succumb to rising macro risks?
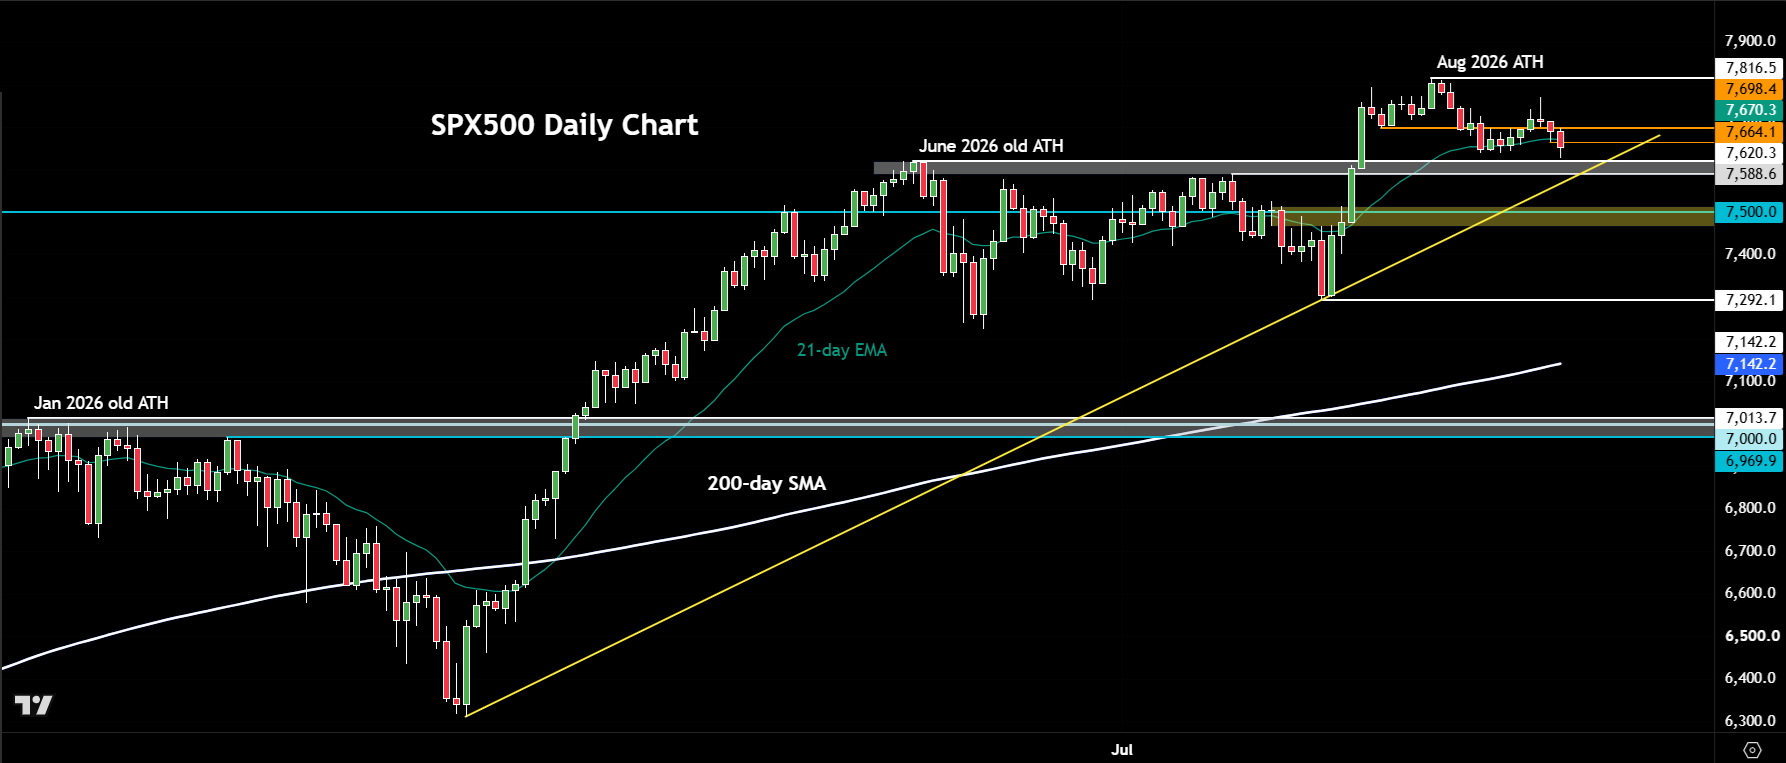
We have seen our US SP 500 index, which is derived from the underlying S&P 500 futures, make a lower high at 7771, relative to its all-time high at 7816 that was hit in mid-August. That has left traders wondering whether we will now see a proper correction.
Well, a lot now depends on the key support zone that is approaching between 7588 to 7620. Here, the index had made its previous all-time high in June, which led to a period of consolidation before the index broke out. Once resistance, will we see this zone turn into support now? If not, and we go below it, then that would be a bearish technical development. in that scenario, we could see some follow-up technical selling towards 7500 next. Below that the July low of 7292 would then come into focus.
On the upside, resistance is seen around 7664, marking Monday’s low. Above that, 7698 is the next resistance. That level held yesterday, leading to the latest drop.
For now, there are some tentative bearish signals but with the larger bullish structure still intact, it is far too early to declare the end of the bullish S&P 500 forecast from a technical analysis point of view. But that could change soon.
Rising oil prices reignite inflation worries
Higher oil prices are threatening to reignite inflation, raising the risks of righter monetary policy. Fed Chair Kevin Warsh’s hawkish Jackson Hole speech has already put a September rate hike firmly back on the table. This is reflected in the global bond markers selling off, sending yields higher across the curve.
In the US, the 10-year bond yield has climbed to a fresh 19-month high and is now only a couple of basis points below its highest level since 2007.
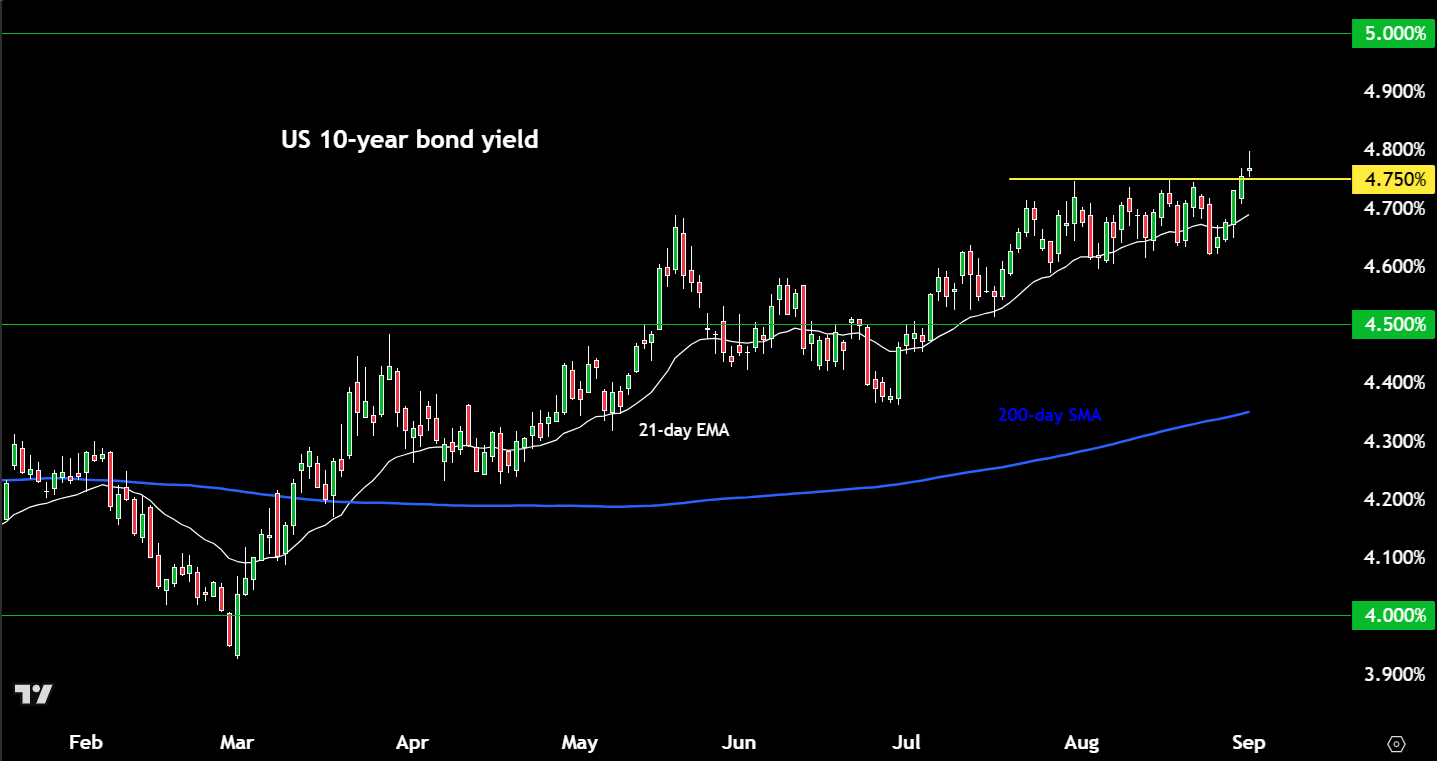
A classis ascending triangle breakout is what we have just seen. Usually, this sort of a breakout precedes further gains.
The 30-year yield has also pushed through recent highs, while Japan’s 30-year yield has broken above 4.18%, a record.
It was only two weeks ago that the US Treasury announced measures aimed at supporting the bond market, yet yields have continued to climb. The market increasingly appears willing to test the authorities’ tolerance for higher borrowing costs. With US debt now above $40tn, a sustained move in the 10-year yield towards 5% would have meaningful fiscal consequences.
With yields on the rise, this is increasing the opportunity cost of holding stocks and putting particular pressure on higher-valued, long-duration sectors such as technology.
Jobs and CPI hold the key
The question now is whether incoming US data can further cement expectations of a September rate hike. Markets have one more payrolls report, due on Friday, and one more CPI release, due next week, before the September 16 FOMC meeting, alongside several secondary indicators this week.
The payrolls report on Friday will be particularly important. With the Fed increasingly data dependent, the market is likely to react sharply to any meaningful surprise. Ahead of that, the focus will be on oil prices and bond markets for fresh signals. Any further gains in either of those markets could weigh on equity markets.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.


Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.