



USD/JPY intervention changes little as yen headwinds remain
The intervention may have delivered a sharp reversal, but the forces that drove USD/JPY higher haven't gone away. Until they do, betting against the broader trend remains a risky proposition.
Share this:
- BOJ misses chance to back stronger yen
- Weak JGB demand reinforces higher yield pressure
- Intervention changes little beneath the surface
- 200DMA becomes pivotal for USD/JPY
The macro backdrop hasn't changed
Despite all the headlines, speculation and the artificial move lower in yen pairs over the past week following the first coordinated intervention between the US and Japan in decades, the truth is that the fundamental backdrop that drove USD/JPY and other yen crosses higher has barely changed. That leaves me thinking it's only a matter of when, not if, USD/JPY and other yen crosses resume the gradual grind higher that was underway before the intervention episode.
Japan's policy problem
It's hardly a revolutionary view, but Japan continues to run some of the loosest monetary policy settings in the developed world. Interest rates remain well below those elsewhere, real rates are still negative and the Bank of Japan passed up what looked like the perfect opportunity last week to send a shot across the bows that it was serious about continuing to normalise policy, instead producing another muddled and cautious performance even though markets have more than one full hike priced into the OIS curve by December.
Why not just get on with it? Inflation has been above target for years and the yen has been weakening for even longer. Yet instead of tackling one of the underlying drivers through faster policy normalisation, Japanese authorities, backed by the United States, opted to intervene in the FX market instead.
Fiscal policy isn't helping the yen's cause either. While Japan isn't running the most expansionary fiscal settings relative to other developed economies, it's the starting point that matters. Government debt is already enormous, leaving the country far more vulnerable than most if an external shock were to emerge. That's one reason investors continue demanding higher yields to own Japanese government debt.
Yesterday's weak 10-year JGB auction reinforced that message. Demand softened noticeably, with the bid-to-cover ratio slipping to 2.56 from 3.13 at the previous sale, while the auction tail blew out to its widest since August 2024, signalling investors demanded greater compensation to absorb the debt ahead of Thursday's 30-year auction.
Then there's the buoyancy of global markets. Risk appetite continues to rip higher, encouraging investors to borrow in one of the world's cheapest funding currencies and invest elsewhere. That's carry trade 101. As long as Japan continues to offer ultra-low interest rates, volatility suppressed while asset prices remain well supported, one of the structural forces that has weighed on the yen remains firmly in place.
No such thing as a free lunch
US Treasury Secretary Scott Bessent attempted to justify the rationale behind US involvement in the first coordinated intervention with Japan in decades during a CNBC interview overnight. He spoke about preserving financial stability across Asia, giving Japan the breathing room to continue investing overseas and expressed confidence that the BOJ would ultimately do what was right for the Japanese economy.
But if I'm being honest, I don't think the explanation stacks up, or at least not entirely. The most interesting part of the interview wasn't what Bessent said, it was what he didn't. There was no mention whatsoever of the risk that Japan, left to defend the yen on its own, may eventually have been forced to sell US dollar assets to fund further intervention.
Instead, he repeatedly returned to Japan's ability to continue investing in the United States, immediately catching my attention given the enormous investment commitments made under last year's trade agreement. Call me cynical, but this administration has shown time and again there's no such thing as a free lunch. If it's prepared to scratch your back, it's usually because there's something much larger in it for the US. Protecting those investment flows while the long end of the US Treasury curve is already under pressure may have been every bit as important as stabilising the yen itself.
Where did the correlations go?
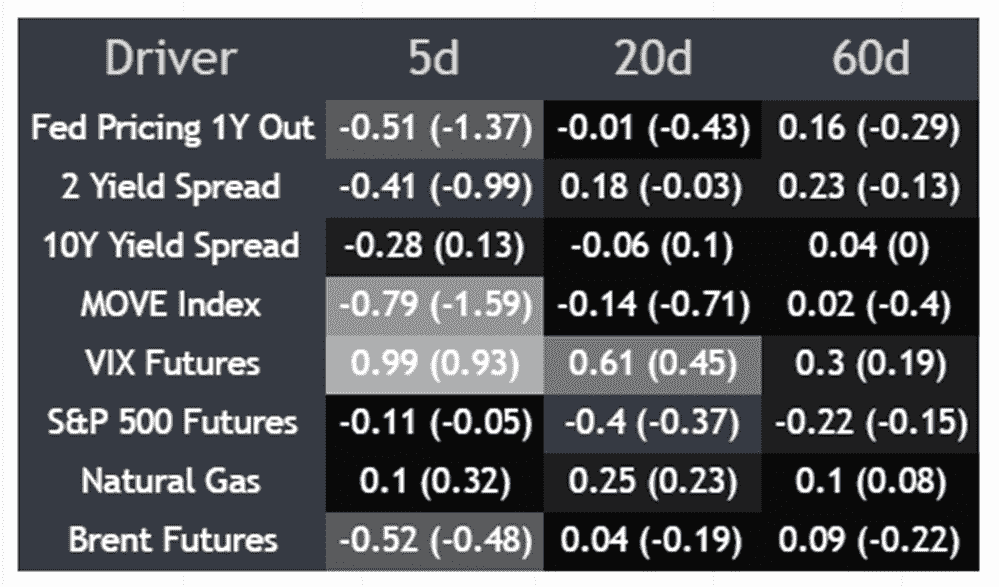
Looking ahead, despite the apparent rationale behind the decision, there's no guarantee the intervention marks the start of a more sustained move lower in USD/JPY. Traditional macro drivers have shown little to no relationship with the pair recently.
Source: Tradingview
As the correlation matrix above highlights, yield differentials, Fed pricing, index futures and energy prices have shown little to no relationship with USD/JPY over both the short and medium-term, while volatility measures are providing mixed and incoherent messaging. That suggests the argument that a softer run of US economic data or stronger Japanese data will be enough to trigger a sustained decline in USD/JPY is not overly convincing.
Eyes on the US calendar
Source: TradingView
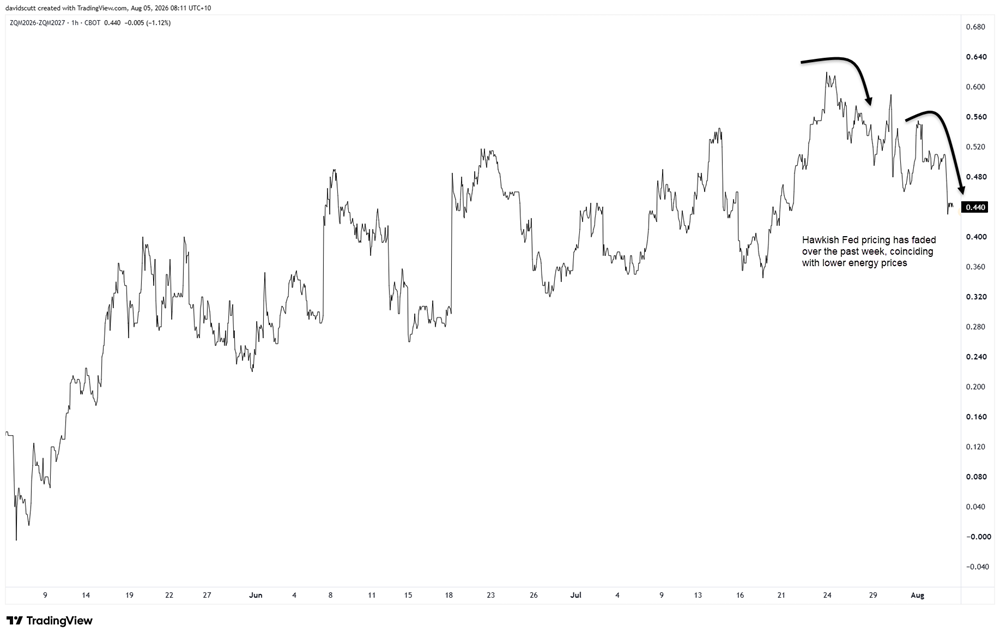
More broadly, the direction of the US dollar is likely to be influenced by the incoming economic data flow. Some of the softness overnight coincided with a notable pullback in Fed rate expectations, with pricing for the June meeting next year falling to around 44 basis points, down more than 10 basis points from where it sat a week ago. That likely reflects the sharp decline in energy prices over recent days rather than anything contained in Tuesday's JOLTS report.
Source: TradingView
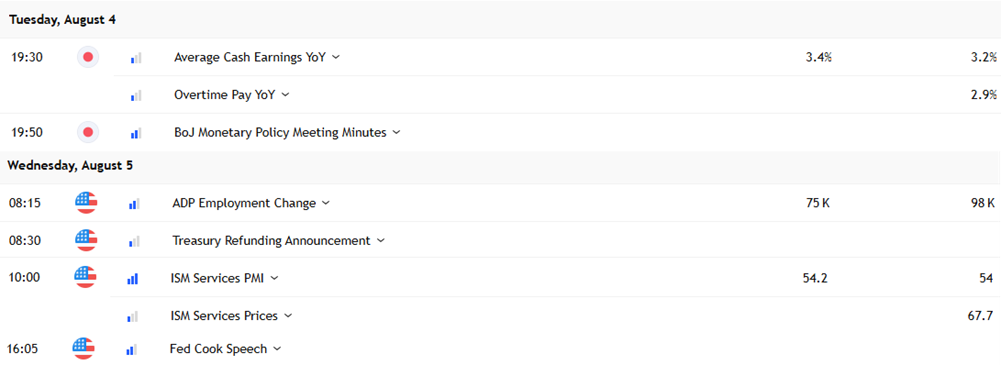
ADP employment will be watched closely after doing a reasonable job of predicting private sector payrolls growth in the official government figures in recent months. ISM services PMI is also important given the sector's significance to the broader US economy, with the prices paid and new orders components likely to provide the best read on inflationary pressures and the near-term growth outlook.
In Japan, wages data is unlikely to move the dial on its own. However, it remains a necessary ingredient if the BOJ is to continue normalising policy, relying on firmer wage growth to support demand, generate inflationary pressures and create the virtuous cycle policymakers have been trying to encourage.
Déjà vu for USD/JPY
Source: TradingView
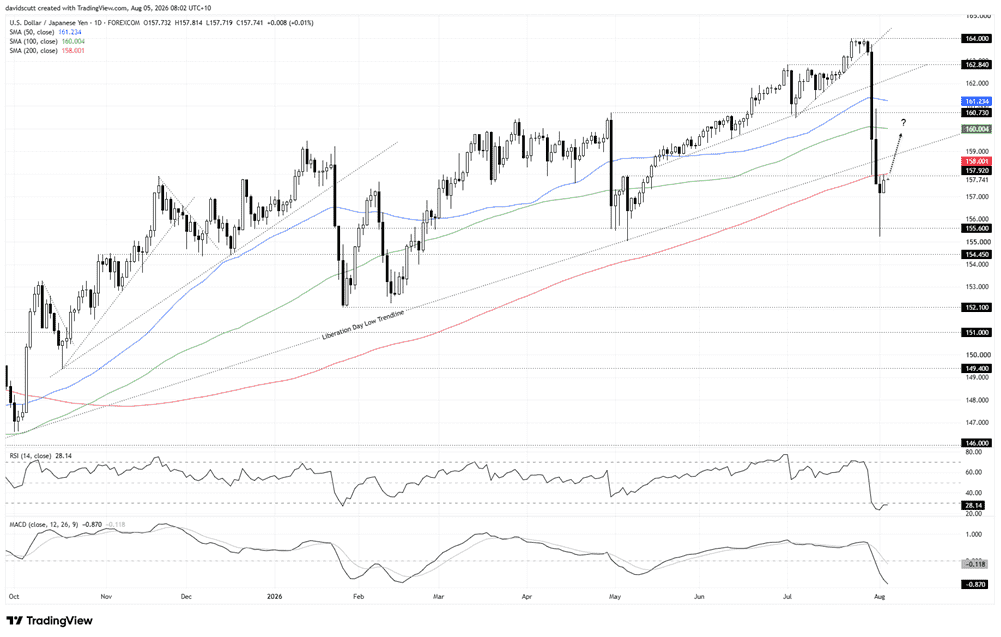
USD/JPY staged a dramatic bounce from the support zone beneath 155.60 on Monday after what looked like a third straight day of intervention. Importantly, that's almost exactly where the pair stabilised after the intervention episode in late April and early May before going on to fully retrace the move over subsequent weeks.
Monday's capitulation-style candle was followed immediately by a bullish engulfing candle on Tuesday, suggesting selling pressure may already be fading. The price now finds itself wedged beneath an important resistance zone formed by the 200-day simple moving average and 157.92, the breakout level that paved the way for the surge to fresh multi-decade highs following the April-May intervention episode.
Given the historical significance of those levels, I get the sense the resistance zone overhead, particularly the 200-day moving average, will act like a dam wall. If the price can break and hold above it, it would reinforce the view the intervention episode is over for now, opening the door for a push towards the 100-day moving average near 160 before bringing the former record high at 160.73, a level that has acted as both support and resistance this year, into view.
While RSI (14) and MACD have weakened sharply following the intervention-induced flush of speculative longs, that alone shouldn't be interpreted as a signal the downside move will persist. If anything, the violent washout leaves positioning looking far less stretched than it did only a week ago. If renewed selling does emerge, which at this stage feels like the less likely outcome, the support zone beneath 155.60 remains the level to watch.
EUR/JPY eyes further retracement
Source: TradingView
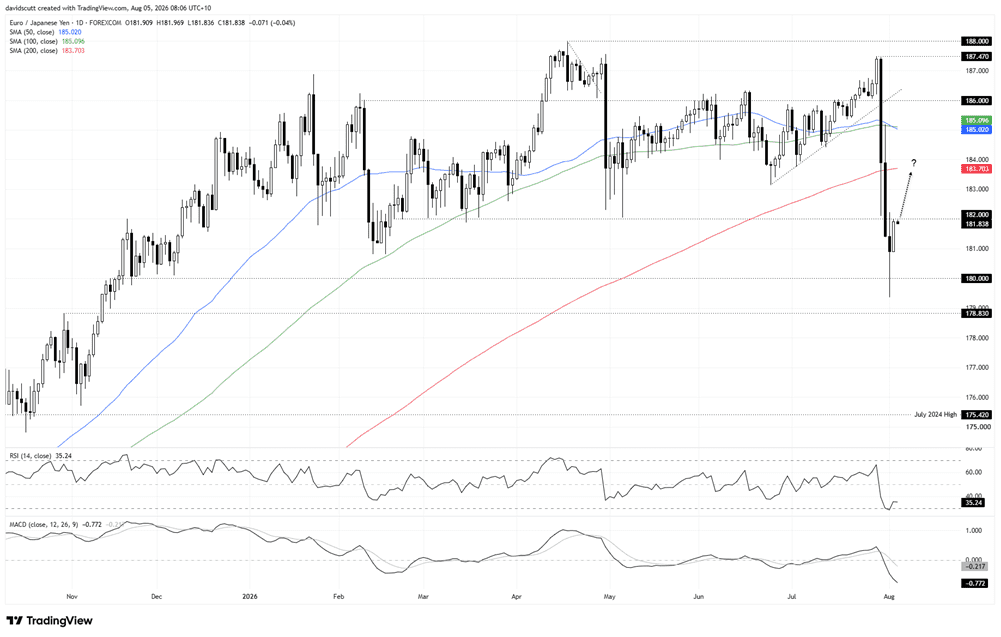
The technical picture for EUR/JPY is similar, with a bullish engulfing candle printing on Tuesday and the pair now sitting just beneath 182, a level that acted as support for extended periods earlier this year before giving way during the intervention episode.
Like USD/JPY, that resistance zone feels like a dam wall. If the price can break and hold above 182, it would reinforce the bullish engulfing signal, opening the door for a push towards the 200-day simple moving average at 183.70. Beyond that, the confluence of the 50 and 100-day simple moving averages around 185 comes into view, followed by 186, another level of note given it acted as resistance for extended periods before flipping to support ahead of the intervention episode.
On the downside, the pair bounced violently after a brief foray beneath 180 during Monday's likely intervention. That leaves the area around 180 as the first support zone to watch, followed by 178.83, the breakout level from October last year.


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

USD/JPY Bulls Continue to Push as Markets ‘Bet Against the House’
USD/JPY is now up by more than 500 pips from the low taken the day that Scott Bessent taunted markets, saying ‘you can bet against me if you want.’


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.