
USD/JPY Update: Can the Japanese Yen Sustain Its Recovery?
Short-term price action around the Japanese yen has started to show some relative improvement over recent sessions. This can be seen in the recent performance of USD/JPY, which has now recorded three consecutive daily declines in favor of the Japanese currency, resulting in a depreciation of roughly 0.35% over the period.
Share this:
Short-term price action around the Japanese yen has started to show some relative improvement over recent sessions. This can be seen in the recent performance of USD/JPY, which has now recorded three consecutive daily declines in favor of the Japanese currency, resulting in a depreciation of roughly 0.35% over the period.
However, the most important point to consider is that this recovery has not been strong enough to change the broader market picture. The yen has benefited from a temporary loss of momentum in the U.S. dollar, but the pair continues to trade within a phase of indecision where neither currency has managed to establish clear dominance. Much of this dynamic remains linked to the recent moderation in U.S. Treasury yields, meaning any meaningful shift in the bond market could continue to have an important impact on USD/JPY price action in the coming sessions.

Are U.S. Bond Yields Starting to Slow Down?
Yesterday's session proved particularly important for financial markets following the release of U.S. inflation data. Initially, the figures came in slightly above expectations, temporarily reinforcing expectations of a more aggressive Federal Reserve and pushing Treasury yields higher.
However, the market reaction began to change shortly afterward. Several Federal Reserve officials, including Michelle Bowman, indicated that there is still room to maintain a restrictive policy stance, although that does not necessarily imply an immediate rate hike in October. These comments helped moderate expectations of a faster pace of monetary tightening.
At the same time, growing concerns surrounding the U.S. equity market, particularly within the technology sector, have started to emerge due to fears of potential overheating. This environment may have encouraged a short-term flight toward defensive assets and boosted demand for bonds, a dynamic that tends to push yields lower.
As a result, 10-year U.S. Treasury yields have begun to show a meaningful moderation. Following the initial inflation-driven move higher, yields have retreated toward the 5.0% area, moving away from recent highs and reflecting a loss of momentum within the bond market in the short term.
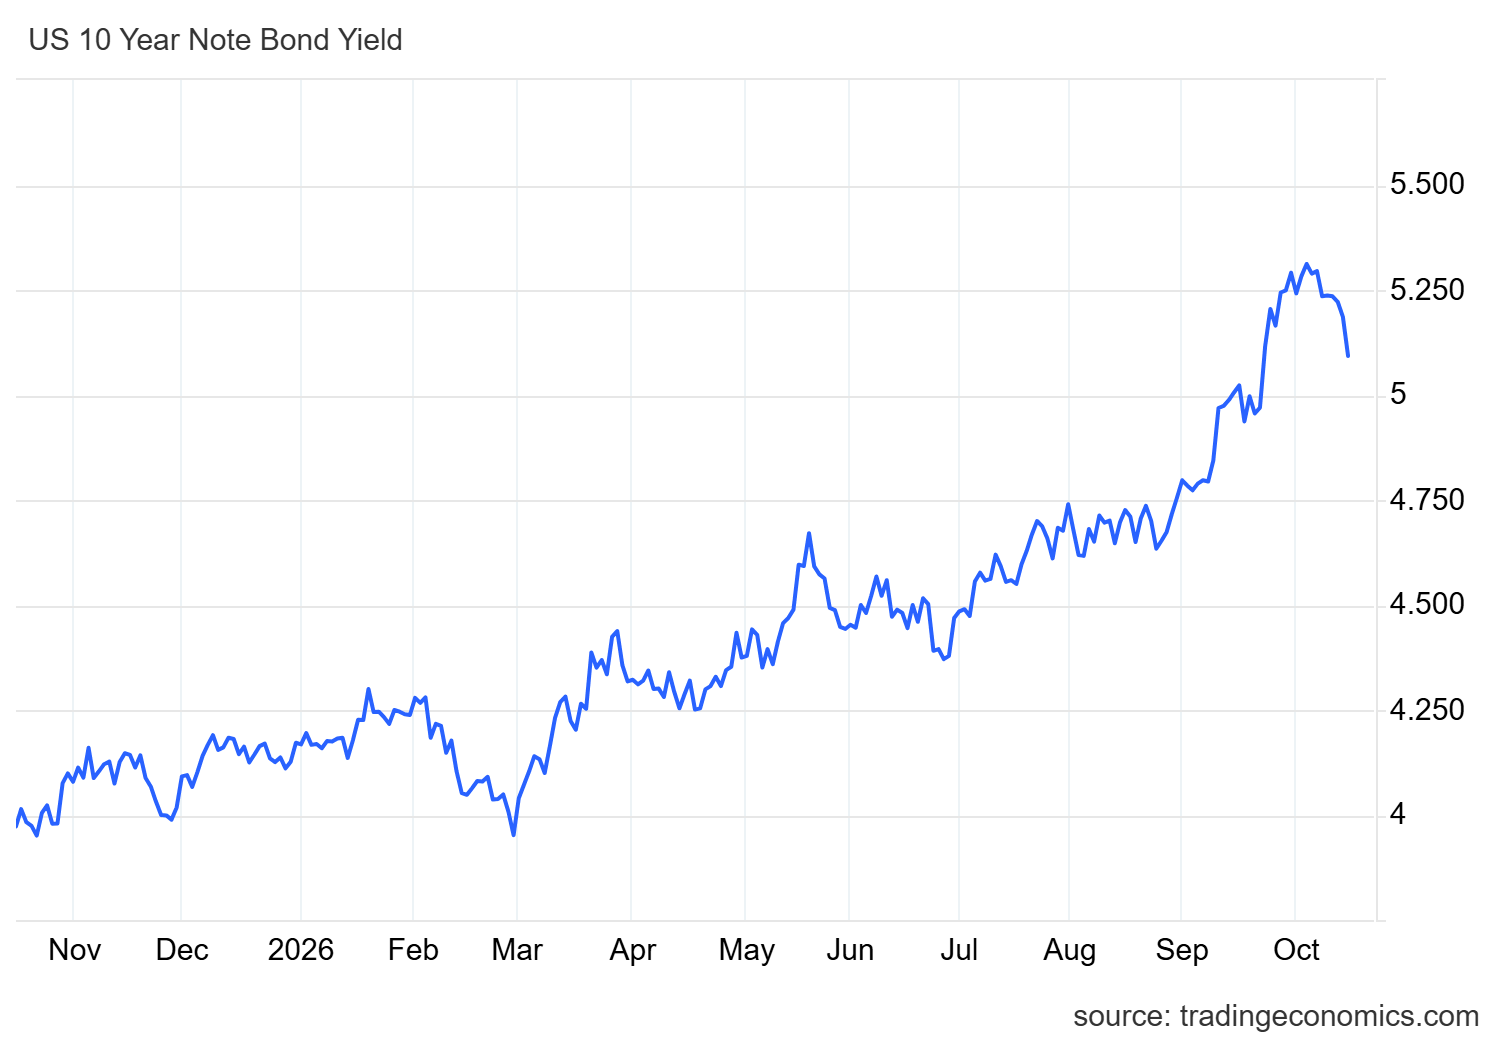
Source: TradingEconomics
This development is important not only for bonds but also for the U.S. dollar. Slower Treasury yields tend to reduce part of the relative attractiveness of dollar-denominated assets, and this has started to appear in the recent behavior of the DXY, the index that measures the dollar against its main peers.
Over the last few sessions, the index has eased from recent highs and has moved back toward the 102-point area, a situation that could be allowing the yen to regain part of the ground it lost during previous weeks.
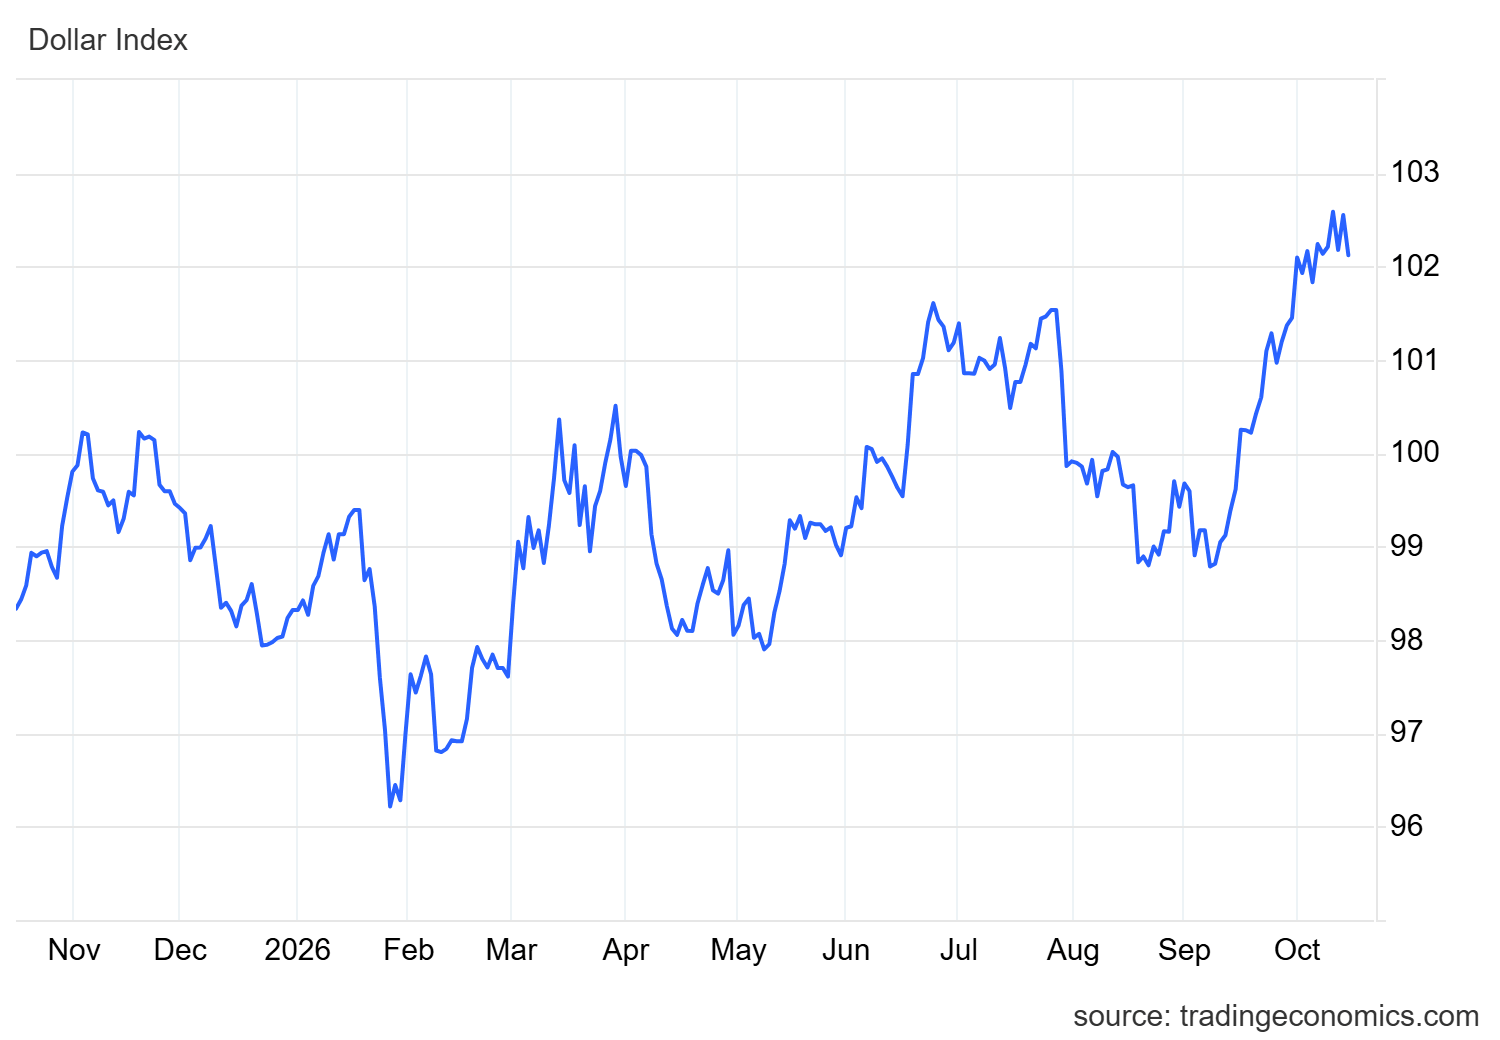
Source: TradingEconomics
Taking all of this into account, it appears that the yen is benefiting from a period of relative dollar weakness driven mainly by softer U.S. yields. However, the recovery seen so far remains limited and is still not enough to change the broader phase of indecision that continues to dominate USD/JPY price action. As long as the moderation in the U.S. bond market remains in place, this lack of direction could continue to be relevant in the coming sessions. Nevertheless, if Treasury yields regain strength, yen weakness could once again become more evident over the weeks ahead.
Does the Bank of Japan Still Matter?
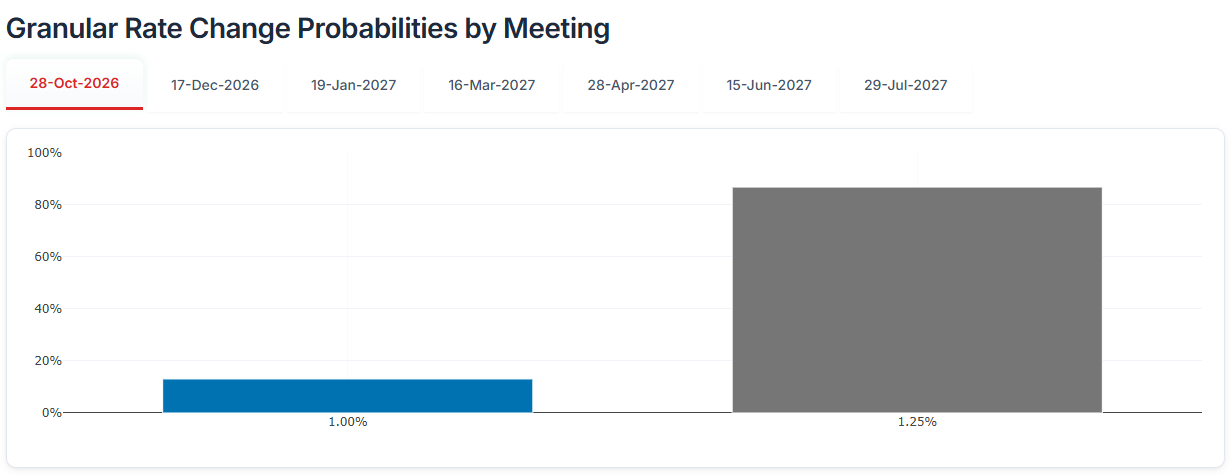
Despite the yen's recent recovery, Japanese monetary policy remains an important factor to monitor. Current market probabilities continue to suggest that the Bank of Japan will leave interest rates unchanged at its October 28 meeting, with the likelihood of policy stability remaining above 80%.
Source: Centralbankwatch
This remains important because Japan's benchmark rate is still near 1.25%, significantly below the current 4.00% reference rate in the United States. As a result, the interest-rate differential continues to favor dollar-denominated investments over yen-denominated assets.
For this reason, although the yen has been able to recover some ground thanks to the recent moderation in U.S. yields, the gap between the monetary policies of both countries remains considerable. If markets once again begin pricing in a more aggressive Federal Reserve while the Bank of Japan maintains its current stance, the rate differential could quickly return as the main driver of USD/JPY.
Under that scenario, buying pressure on the pair could regain relevance over the medium and longer term, particularly if there are no signs of higher rates emerging within the Japanese economy.
USD/JPY Technical Forecast
Source: StoneX, Tradingview
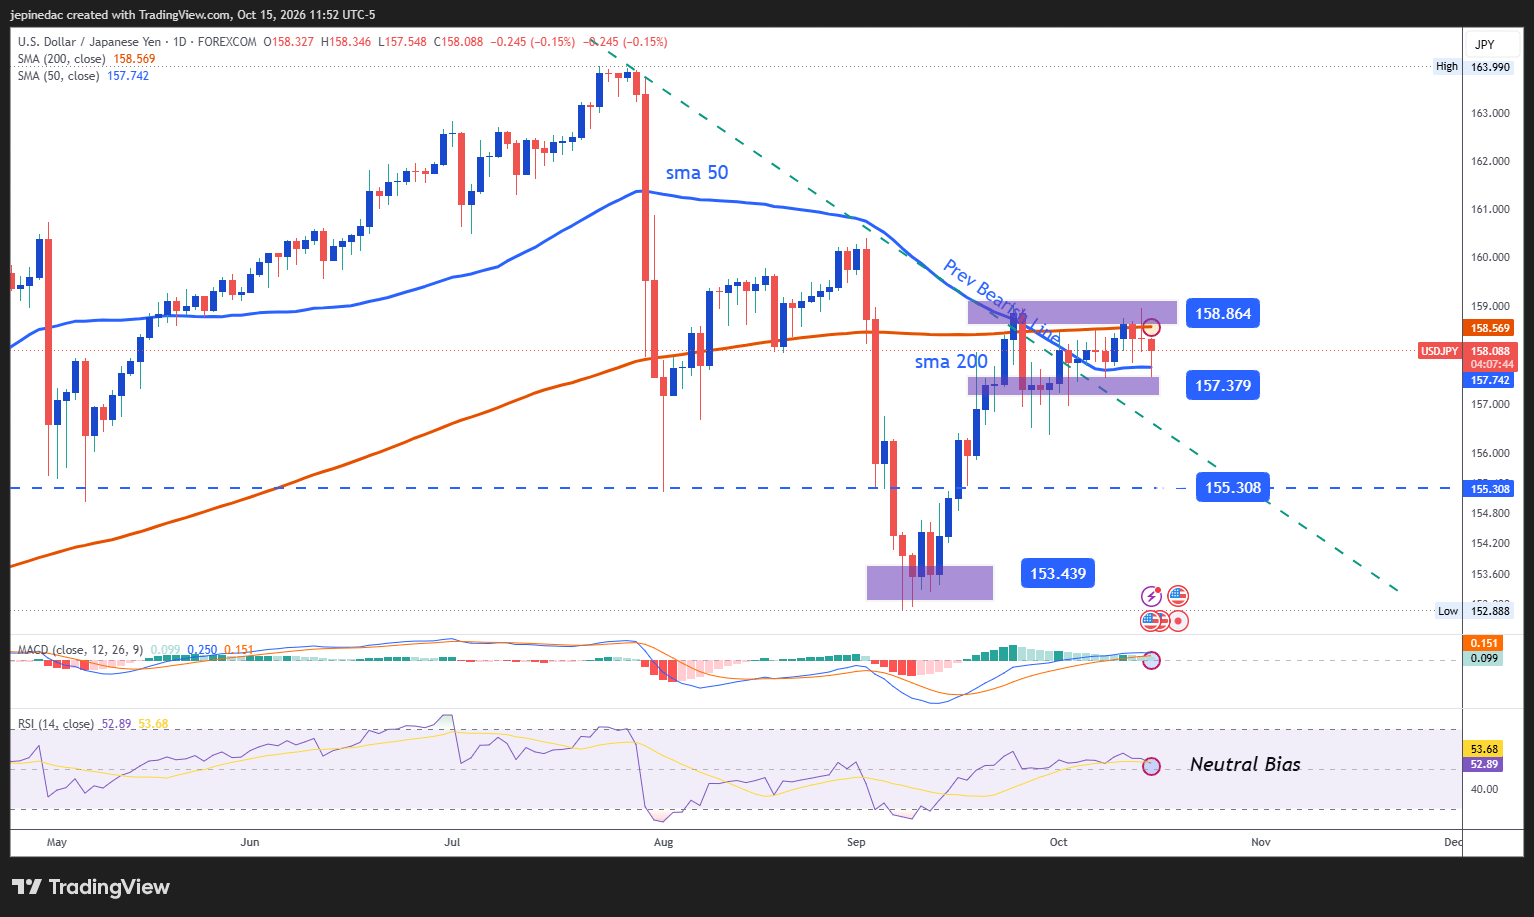
- A short-term trading range is becoming increasingly relevant: Although USD/JPY managed to break above the major bearish trendline that had dominated price action for months, that breakout has not yet been sufficient to establish a new trend. Instead, the pair has gradually developed a relatively consistent trading range around the 200-period moving average. As long as price continues to respect the boundaries of this range, the lack of direction could remain the dominant feature of market behavior over the coming weeks.
- MACD: The MACD histogram continues to trade very close to the 0 neutral line, reflecting an increasingly balanced dynamic in short-term moving-average momentum. This reading supports a phase of indecision that could remain relevant over the coming sessions.
- RSI: A similar situation can be observed in the RSI, which continues to fluctuate near the 50 neutral level. This behavior reflects a relatively balanced environment between buyers and sellers and supports the possibility that indecision may continue to dominate market activity in the short term.
Key Levels:
- 158.86 – Key Resistance: A level that coincides with the 200-period simple moving average and represents the most important short-term upside barrier. Sustained moves above this level could signal a meaningful shift in market structure and open the door to a more established bullish trend over the coming weeks.
- 157.37 – Near-Term BarrierA level that aligns with the lower boundary of the current trading range and also remains close to the 50-period simple moving average. A break below this area could begin to favor a more consistent bearish bias during the coming sessions.
- 155.30 – Key Support: An area of significant lows observed in previous weeks that remains one of the most important downside references on the chart. Moves back toward this zone could restore relevance to the bearish bias and revive the importance of the former downtrend as the dominant market structure over the longer term.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him on: @julianpineda25
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Update: Can the Japanese Yen Sustain Its Recovery?
Short-term price action around the Japanese yen has started to show some relative improvement over recent sessions. This can be seen in the recent performance of USD/JPY, which has now recorded three consecutive daily declines in favor of the Japanese currency, resulting in a depreciation of roughly 0.35% over the period.
US Dollar Technical Outlook: DXY, Treasury Yields Retreat Despite Hot CPI 10 15 2026
The US Dollar is testing major support despite hotter inflation as Fed pushback cools yields and forces markets to reassess the path for tightening.

US Dollar Bulls Got Everything They Wanted. Except a Rally.
Bond bears had every excuse to wreak havoc after September's inflation surprise. Instead, buyers returned aggressively, leaving Treasury futures threatening to bottom and the dollar struggling to extend its rally.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.