




Whats moving the markets on Monday
The FTSE, along with its European peer are heading for a higher start boosted by vaccine optimism and ahead of a key day in Parliament for the Internal Markets Bill.
Share this:
The FTSE, along with its European peer are heading for a higher start boosted by vaccine optimism and ahead of a key day in Parliament for the Internal Markets Bill.
Vaccine trials restart
Over the weekend, Oxford University announced that the joint AstraZeneca covid vaccine trial will restart this week after a routine pause n the previous week. News that the trial is back on track is music to the ears of the market. A vaccine is the surest and quickest, and possibly the only way for the economy to recover to pre-pandemic growth levels. The vaccine news comes as the “Rule of 6” comes into force in the UK, banning meetings of groups of over 6. AstraZeneca shares are on the rise in early trade.
Adding to the upbeat vaccine news Pfizer In Chief executive officer Albert Bourla said its likely that a covid vaccine will be deployed in the US by the end of the year. A more optimistic view than health authorities.
Internal Markets Bill debate
Markets and the Pound are braced for another big Brexit week. The controversial internal markets bill will start to be discussed today in the House of Commons. It is not certain whether the bill will make it through the Commons or even the Lords given that it breaks international law. However, if it does clear Parliaments the Justice Secretary Robert Buckland has already said he will resign. The Pound was the worst performer across the previous week, shedding 3.7% versus the USD in its worst weekly performance since early March. GBP is one of the of performing majors this morning ahead of the debate.
Markets and the Pound are braced for another big Brexit week. The controversial internal markets bill will start to be discussed today in the House of Commons. It is not certain whether the bill will make it through the Commons or even the Lords given that it breaks international law. However, if it does clear Parliaments the Justice Secretary Robert Buckland has already said he will resign. The Pound was the worst performer across the previous week, shedding 3.7% versus the USD in its worst weekly performance since early March. GBP is one of the of performing majors this morning ahead of the debate.
Whilst the 8th round of Brexit talks ended with unsurprisingly little progress, informal Brexit talks are set to continue across the week, ahead of the 9th round beginning on 25th September.
TikTok to partner Oracle, Nvidia buys ARM
Rumours are swirling that TiKTok is choosing to partner up with Oracle rather than Microsoft. Microsoft hasn’t been asked to revise its initial offer amid opposition to the deal from the Chinese government. Has Microsoft managed to dodge a bullet? Could be so according to Bloomberg reports that the deal no longer includes key underlying technologies and the prospect of Chinese government approval is unclear at best.
Nvidia has agreed to buy ARM Holding, SoftBank’s chip division for $40 billion 4 years after the Japanese bank bought it for $32 billion.
Eurozone industrial production
Looking ahead, Eurozone industrial production data will provide some clues as to the health of the sector. Expectations are for growth 10% mom in July, up from 9.1% in June as the sector outperforms services in its recovery.
Looking ahead, Eurozone industrial production data will provide some clues as to the health of the sector. Expectations are for growth 10% mom in July, up from 9.1% in June as the sector outperforms services in its recovery.
FTSE Chart
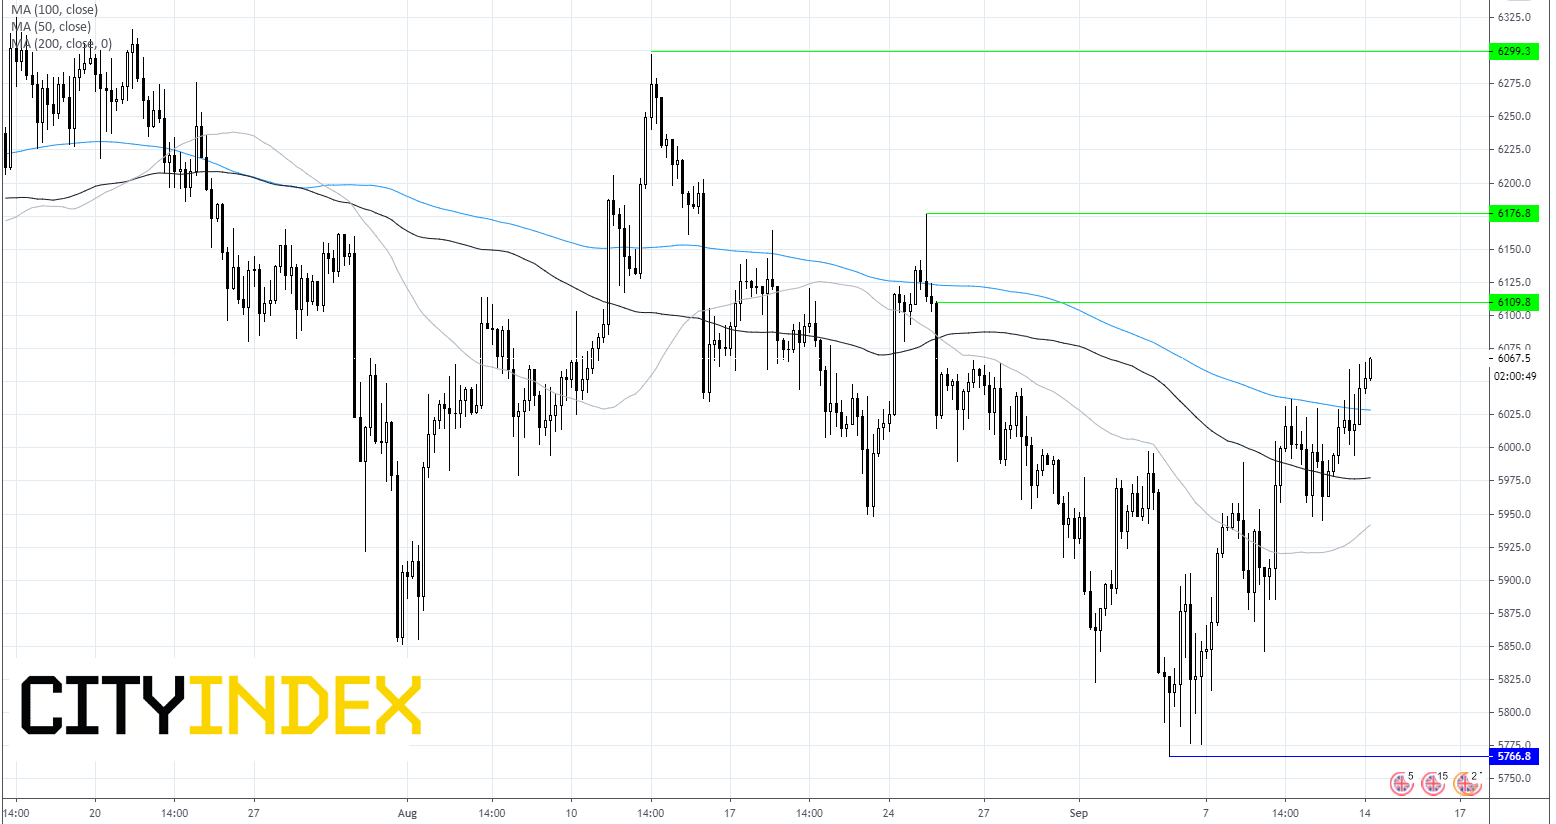
The FTSE is continuing its rebound from Sept 3rd lows, pishing above 50,100 and 200 sma on 4 hr chart. Immediate resistance can be seen at 6110 prior to 6180 (high 25th Aug).
Support can be seen at 6030 200 sma, prior to 5980 (100sma).
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.