



ASX200 Afternoon Wrap 23rd of March 2022
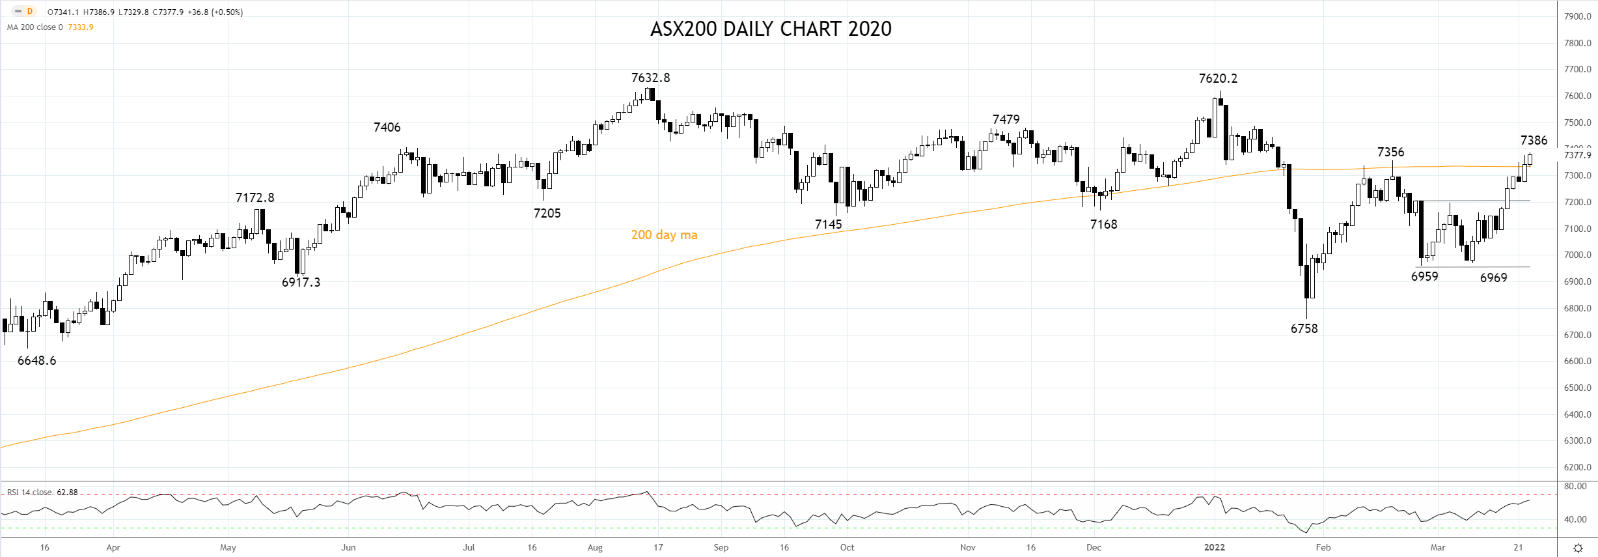
Fresh recovery highs for the ASX200 today as it added 37 points (0.50%) to close at 7378, just 3 ½ per cent below its all-time high from August last year.
Share this:
A sea of green also across regional equity markets led by the Japanese stock market, the Nikkei, which added 2.87% on expectations that an increasingly hawkish Federal Reserve has set its sights on taming rampant inflation.
Overnight St Louis Fed President Bullard reiterated his preference for the FOMC is to move “aggressively” to keep inflation under control and noted the FOMC could not wait for geopolitical risks to be resolved.
Bullard likened the current cycle to 1994 when the Federal Reserve lifted interest from 3.25% to 6% in response to a strong economy and an inflation rate ~2.50% vs 7.9% now.
After a strong reporting season, a staggering $24bn in dividend payments hits investor bank accounts next week. BHP alone is due to pay out $10b in dividends next Monday.
If today’s performance of the IT sector is anything to go by, the divvy dollars look to be finding a home.
Afterpay owner Block (SQ2) traded to its highest level since its ASX200 listing, adding 7.49% to $188.10, Zip Co (Z1P) added 7.52% to $1.65, Sezzle (SZL) lifted by 5.69% to $1.49, Appen added 3.51% to $7.07, and Xero (XRO) added 4.16% to $102.93.
Another ratchet higher in yields overnight provided support for the Financial Sector as it allows the big banks to increase profitability via higher Net Interest Margins.
Macquarie (MCQ) added 1.25% to $200.05, its highest close in six weeks as it bids for ASX listed firm Uniti. National Australia Bank (NAB) added 1.57% to $31.72, ANZ added 0.76% to $27.88, Westpac (WBC) added 0.76% to $23.80, and Commonwealth Bank (CBA) lifted by 1.30% to $107.45, closing in on its all-time high at $110.19.
Crude oil is trading back above $110/bbl despite it becoming increasingly unlikely the EU will join the U.S in a Russian oil embargo. Woodside Petroleum (WPL) added 0.44% to 32.30. Santos (STO) closed 0.26% lower at $7.77, while Beach Energy (BPT) lost 1.54% to $1.60.
A 1.2% fall in the iron ore price to $148.50 has weighed on the Materials sector. Mineral Resources (MIN) fell 1.55% to $48.33. BHP Group (BHP) lost 0.78% to $48.44. Rio Tinto (Rio) closed flattish at $113.68. Fortescue Metal Group (FMG) bucked the trend to trade 0.32% higher to $19.00.
A slump in the price of gold to $1922 (-0.75%) on improved risk sentiment and higher yields have weighed today on ASX200 listed goldies. Newcrest Mining (NCM) fell 2.04% to $25.45. Northern Star Resources (NST) lost 1.98% to $10.39, Evolution Mining (EVN) lost -1.57% to $4.38.
Onwards and upwards for the Australian dollar, trading at four-month highs at .7455, despite the broader commodity complex easing and higher U.S. yields.
Source Tradingview. The figures stated are as of March 23rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
A sea of green also across regional equity markets led by the Japanese stock market, the Nikkei, which added 2.87% on expectations that an increasingly hawkish Federal Reserve has set its sights on taming rampant inflation.
Overnight St Louis Fed President Bullard reiterated his preference for the FOMC is to move “aggressively” to keep inflation under control and noted the FOMC could not wait for geopolitical risks to be resolved.
Bullard likened the current cycle to 1994 when the Federal Reserve lifted interest from 3.25% to 6% in response to a strong economy and an inflation rate ~2.50% vs 7.9% now.
After a strong reporting season, a staggering $24bn in dividend payments hits investor bank accounts next week. BHP alone is due to pay out $10b in dividends next Monday.
If today’s performance of the IT sector is anything to go by, the divvy dollars look to be finding a home.
Afterpay owner Block (SQ2) traded to its highest level since its ASX200 listing, adding 7.49% to $188.10, Zip Co (Z1P) added 7.52% to $1.65, Sezzle (SZL) lifted by 5.69% to $1.49, Appen added 3.51% to $7.07, and Xero (XRO) added 4.16% to $102.93.
Another ratchet higher in yields overnight provided support for the Financial Sector as it allows the big banks to increase profitability via higher Net Interest Margins.
Macquarie (MCQ) added 1.25% to $200.05, its highest close in six weeks as it bids for ASX listed firm Uniti. National Australia Bank (NAB) added 1.57% to $31.72, ANZ added 0.76% to $27.88, Westpac (WBC) added 0.76% to $23.80, and Commonwealth Bank (CBA) lifted by 1.30% to $107.45, closing in on its all-time high at $110.19.
Crude oil is trading back above $110/bbl despite it becoming increasingly unlikely the EU will join the U.S in a Russian oil embargo. Woodside Petroleum (WPL) added 0.44% to 32.30. Santos (STO) closed 0.26% lower at $7.77, while Beach Energy (BPT) lost 1.54% to $1.60.
A 1.2% fall in the iron ore price to $148.50 has weighed on the Materials sector. Mineral Resources (MIN) fell 1.55% to $48.33. BHP Group (BHP) lost 0.78% to $48.44. Rio Tinto (Rio) closed flattish at $113.68. Fortescue Metal Group (FMG) bucked the trend to trade 0.32% higher to $19.00.
A slump in the price of gold to $1922 (-0.75%) on improved risk sentiment and higher yields have weighed today on ASX200 listed goldies. Newcrest Mining (NCM) fell 2.04% to $25.45. Northern Star Resources (NST) lost 1.98% to $10.39, Evolution Mining (EVN) lost -1.57% to $4.38.
Onwards and upwards for the Australian dollar, trading at four-month highs at .7455, despite the broader commodity complex easing and higher U.S. yields.
Source Tradingview. The figures stated are as of March 23rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.

Dow Jones Analysis: Is the DJIA Making a Comeback?
Recent trading sessions have become increasingly relevant for the Dow Jones, as the index has started to regain bullish momentum heading into the end of the week. Over the last three sessions, the DJIA has advanced by more than 0.6%, allowing buying pressure to regain prominence and raising the possibility of a more consistent short-term recovery.
ASX 200 Slides as Oil, Yields and Rate Risks Hit Sentiment
The ASX 200 suffered its worst week in six months as surging oil, higher bond yields and renewed rate-hike bets drove a broad risk-off move.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.