



Powell Pontificates but Pulls his Punches as Predicted
In yesterday’s article, we highlighted the crosswinds impacting today’s speech by Fed Chairman Powell at the Jackson Hole Symposium, eventually concluding that, “Powell [should] maintain the same optimistic perspective he espoused at his Congressional testimony last month”
Share this:

In yesterday’s article, we highlighted the crosswinds impacting today’s speech by Fed Chairman Powell at the Jackson Hole Symposium, eventually concluding that, “Powell [should] maintain the same optimistic perspective he espoused at his Congressional testimony last month” (see “Is EUR/USD Rolling Over Ahead of Powell?” for more). As it turns out, this prediction was accurate, though the initial market reaction did little to reassure dollar bulls.
First, the headlines from Powell’s speech were as follows (emphasis mine):
- POWELL SEES GOOD REASON TO EXPECT STRONG ECONOMY TO CONTINUE
- POWELL: GRADUAL HIKES LIKELY APPROPRIATE IF GROWTH STAYS STRONG
- POWELL: THERE DOESN'T SEEM TO BE ELEVATED RISK OF OVERHEATING
- POWELL: WILL DO WHAT IT TAKES IF INFLATION EXPECTATIONS DRIFT
- POWELL SAYS NO CLEAR SIGN OF INFLATION ACCELERATING ABOVE 2%
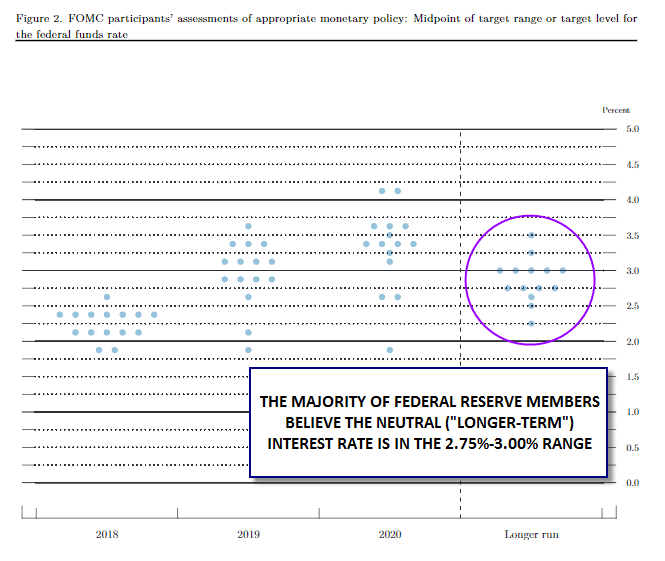
The headlines about strong economic growth and further “gradual” hikes were widely expected, and therefore fully discounted by the market. That said, the repeated emphasis on subdued inflationary pressures suggests that Powell sees no urgency to raise interest rates above the “neutral” rate, which the majority of Federal Reserve members believe is in the 2.75-3.00% range according to the central bank’s most recent Summary of Economic Projections.
Source: Federal Reserve, FOREX.com
In terms of market expectations, there’s been essentially no change to the market-implied odds of a rate hike in September (95%+) or December (~65%), as befits a mostly as-expected speech. With the Fed’s path seeming set for the next three months, shorter-term traders may now turn their attention to political and economic developments instead of central banker comments.
Market Reaction: Mixed
We’ve some interesting, if inconsistent, moves in the wake of the Powell’s comments. As of writing, US stock indices are trading higher on the day by about 0.5%, with the S&P 500 hitting a fresh record high. After an initial swoon, the US dollar index is stabilizing just above 95.00, where it opened the week. Both gold and oil are rising by about 2% on the day, and the yield on the benchmark 10-year Treasury bond has dropped 2bps back to 2.82%.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Outlook: Historic yield squeeze leaves Aussie bears in control
Australian bond yields have fallen below their US equivalents as the Fed's hawkish repricing gathers momentum. With the Aussie weakening broadly, technical signals suggest sellers remain in control.
GBP/USD approaches breaking point as US yields surge
A historic repricing of US interest rate expectations has propelled the dollar higher, leaving GBP/USD testing a crucial support level ahead of UK GDP.
EUR/USD, DXY, Silver Price Outlook: Bullish Rebounds on Hold?
EUR/USD, DXY, Silver Price Outlook: Bullish rebounds across currency markets, precious metals, and risk assets are facing renewed pressure as U.S. CPI comes in above expectations and oil-tanker attacks persist in the Strait of Hormuz.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.