



US open: Stocks edge higher after PPI falls again
Stocks are nursing the heavy selloff yesterday. Slightly cooler than expected PPI has helped prevent a follow through selloff, at least for now.
Share this:

US futures
Dow futures +0.16% at 31140
S&P futures +0.27% at 3940
Nasdaq futures +0.36% at 12080
In Europe
FTSE -1.4% at 7286
Dax -1.12% at 13051
Euro Stoxx -0.6% at 3560
PPI rises by 8.7%
US stocks are heading for a mildly higher start to the day after suffering the steepest one-day selloff in two years yesterday, as investors continue to mull over the inflation shock.
All three leading indices closed sharply lower, with the Nasdaq dropping over 5%, the S&P500 4.3%, and the Dow Jones 3.9%.
Investors had been hopeful that data would show clear signs of inflation cooling; CPI was strong than expected, paving the way for more aggressive Fed rate hikes ahead of the FOMC next week. The CME Fed watch shows that the market is now pricing in a 20% chance of a 1% rate hike this month. Although we still see 75 bps as the base case.
Today eyes remain on inflation data with the release of PPI, which showed that factory gate inflation rose 8.7% YoY in August, down from 9.8% in July. This marked the third straight month of falling PPI, a data point which is considered a lead indicator for consumer prices.
The data is brining at least a pinch of optimism after yesterday’s inflation surprise, which is helping stocks tick modestly higher and the USD lower.
Corporate news:
Alphabet will be under the spotlight after Europe’s second top-tier court upheld an EU anti-trust decision against Google. However, the record fine was trimmed to €4.12 billion from €4.34 billion.
Where next for the S&P500?
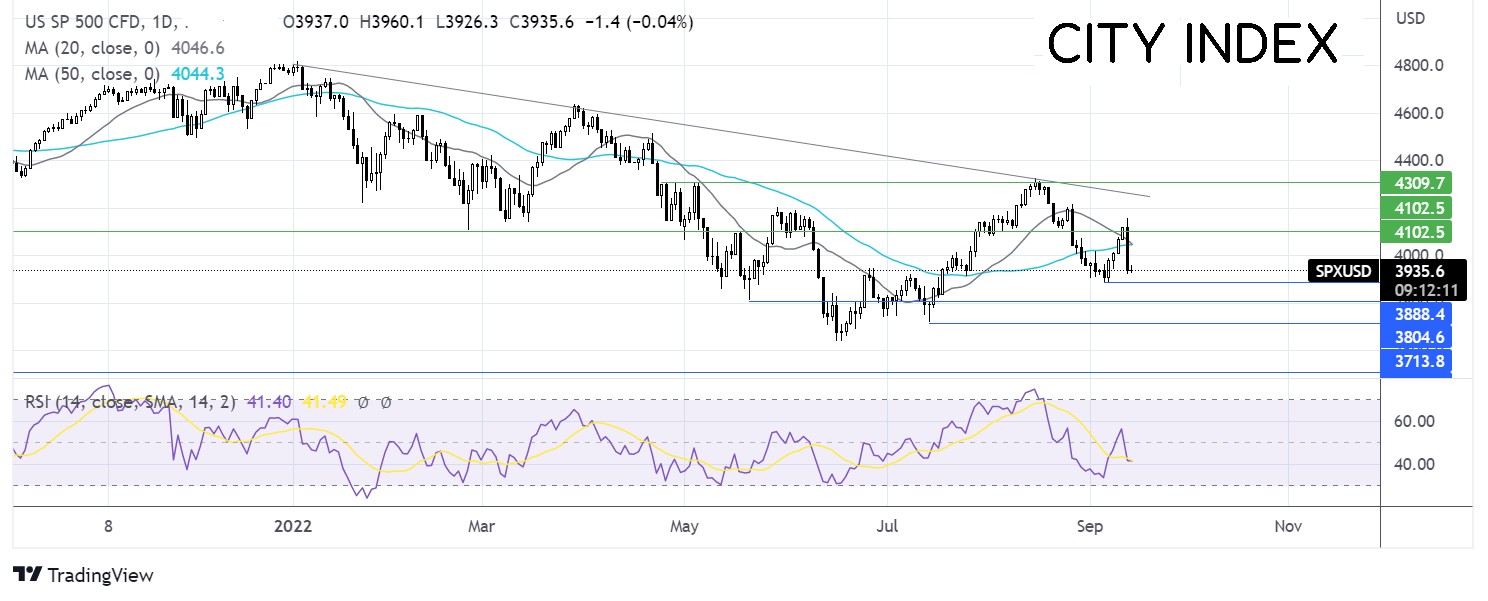
The S&P500’s rebound from 3880, the September low, ran into resistance at 4155, yesterday’s high. From here, the bearish engulfing candle, the break below the 20 & 50 sma, and the bearish RSI are keeping sellers hopeful of further downside. Sellers will look to break below 3880 the continue the bearish trend towards 3800, the May 20 low, and 3715, the July 14 low. Buyers will first eye a move over 4000 psychological level ahead of 4040 the 20 & 50 sma.

FX markets – USD falls, EUR rises
The USD is falling after solid gains yesterday following the hotter-than-expected inflation data. The USD jumped 1.2% yesterday after strong core inflation raised fears that the Fed will aggressively hike rates into the year's end.
EUR/USD is rising despite weaker than expected industrial production data. Industrial output fell -2.3% MoM after increasing 0.7% in June. In her state of the union speech, Ursula von der Leyen promised to overhaul the energy market.
GBP/USD is rising after an unexpected fall in UK inflation; UK CPI rose 9.9% YoY in August, down from 10.1% in July and short of forecasts of a rise to 10.2%. The data should ease some pressure on the BoE as it fights 40-year high inflation. The data also raises hopes that, with the help of Liz Truss’ energy plan, inflation may have peaked.
GBP/USD +0.6% at 1.1559
EUR/USD +0.4% at 1.005
Oil steadies
Oil prices are edging higher after small losses from the previous session. The hotter-than-expected US inflation raised concerns over more aggressive interest rate hikes, which will slow growth. This is hurting the demand outlook for oil.
The International Energy Agency (IEA) warned that oil demand would stall in the final three months of the year as global growth stumbles. Rising interest rates and COVID lockdowns in China paint a rather grim picture for demand.
The IEA slashed its demand forecast this year by 110,000 barrels per day to 2 million bpd, but expects demand to recover next year by leaving forecasts unchanged at 21 million bpd.
The data follows OPEC’s forecasts, which pointed to continued growth in demand in 2022 and 2023 despite the challenging economic backdrop. This appears to be a somewhat optimistic view.
WTI crude trades +0.6% at $87.00
Brent trades +0.7% at $93.20
Looking ahead
N/A
US futures
Dow futures +0.16% at 31140
S&P futures +0.27% at 3940
Nasdaq futures +0.36% at 12080
In Europe
FTSE -1.4% at 7286
Dax -1.12% at 13051
Euro Stoxx -0.6% at 3560
Learn more about trading indices
PPI rises by 8.7%
US stocks are heading for a mildly higher start to the day after suffering the steepest one-day selloff in two years yesterday, as investors continue to mull over the inflation shock.
All three leading indices closed sharply lower, with the Nasdaq dropping over 5%, the S&P500 4.3%, and the Dow Jones 3.9%.
Investors had been hopeful that data would show clear signs of inflation cooling; CPI was strong than expected, paving the way for more aggressive Fed rate hikes ahead of the FOMC next week. The CME Fed watch shows that the market is now pricing in a 20% chance of a 1% rate hike this month. Although we still see 75 bps as the base case.
Today eyes remain on inflation data with the release of PPI, which showed that factory gate inflation rose 8.7% YoY in August, down from 9.8% in July. This marked the third straight month of falling PPI, a data point which is considered a lead indicator for consumer prices.
The data is brining at least a pinch of optimism after yesterday’s inflation surprise, which is helping stocks tick modestly higher and the USD lower.
Corporate news:
Alphabet will be under the spotlight after Europe’s second top-tier court upheld an EU anti-trust decision against Google. However, the record fine was trimmed to €4.12 billion from €4.34 billion.
Where next for the S&P500?
The S&P500’s rebound from 3880, the September low, ran into resistance at 4155, yesterday’s high. From here, the bearish engulfing candle, the break below the 20 & 50 sma, and the bearish RSI are keeping sellers hopeful of further downside. Sellers will look to break below 3880 the continue the bearish trend towards 3800, the May 20 low, and 3715, the July 14 low. Buyers will first eye a move over 4000 psychological level ahead of 4040 the 20 & 50 sma.
FX markets – USD falls, EUR rises
The USD is falling after solid gains yesterday following the hotter-than-expected inflation data. The USD jumped 1.2% yesterday after strong core inflation raised fears that the Fed will aggressively hike rates into the year's end.
EUR/USD is rising despite weaker than expected industrial production data. Industrial output fell -2.3% MoM after increasing 0.7% in June. In her state of the union speech, Ursula von der Leyen promised to overhaul the energy market.
GBP/USD is rising after an unexpected fall in UK inflation; UK CPI rose 9.9% YoY in August, down from 10.1% in July and short of forecasts of a rise to 10.2%. The data should ease some pressure on the BoE as it fights 40-year high inflation. The data also raises hopes that, with the help of Liz Truss’ energy plan, inflation may have peaked.
GBP/USD +0.6% at 1.1559
EUR/USD +0.4% at 1.005
Oil steadies
Oil prices are edging higher after small losses from the previous session. The hotter-than-expected US inflation raised concerns over more aggressive interest rate hikes, which will slow growth. This is hurting the demand outlook for oil.
The International Energy Agency (IEA) warned that oil demand would stall in the final three months of the year as global growth stumbles. Rising interest rates and COVID lockdowns in China paint a rather grim picture for demand.
The IEA slashed its demand forecast this year by 110,000 barrels per day to 2 million bpd, but expects demand to recover next year by leaving forecasts unchanged at 21 million bpd.
The data follows OPEC’s forecasts, which pointed to continued growth in demand in 2022 and 2023 despite the challenging economic backdrop. This appears to be a somewhat optimistic view.
WTI crude trades +0.6% at $87.00
Brent trades +0.7% at $93.20
Learn more about trading oil here.
Looking ahead
N/A
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.


S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.